The Actual Ways This Works
Most people figure this out on their own and then forget it until they need to move a large sum. There are really only a few mechanisms in play here, and they operate on completely different timelines and cost structures. Understanding which one you're using matters more than people realize. The mechanics depend on which rails you choose. ACH transfers are the slow standard. You enter the routing number and account number of the destination bank, initiate the transfer through your online portal, and wait one to three business days. It costs nothing at your bank, though some third-party apps charge a small fee. The routing number is the nine-digit code that identifies your bank. The account number is yours. You'll find both on a check or in your banking app. Wire transfers are faster but more expensive. Domestic wires typically settle the same business day if initiated before the cut-off time, which varies by institution but is often around 3pm Eastern. You pay between twenty and forty-five dollars per outgoing wire. Incoming wires are usually free. The money moves directly between banks through the Federal Reserve's system. There's no going back once it's sent. I learned that the hard way.
Real-time payment networks like FedNow in the US or similar services elsewhere have changed the game somewhat. These settle within seconds, twenty-four seven. Not every bank participates yet, which is a frustrating gap. If your bank and the recipient's bank are both on the network, you can push money and it arrives before you finish confirming the details on your phone. I once wired ten thousand dollars to a contractor who gave me his account details over the phone during a renovation crisis. Everything looked right. The routing number matched his bank. The account number was eleven digits, which is normal for that institution. The transfer went through. Two days later, he called saying he never received it. His bank had rejected it because the name on the account didn't match the name I'd entered as the beneficiary. I'd abbreviated his middle name. The wire hadn't been returned to me—it had sat in limbo at his bank's processing queue. We spent four hours on hold between two banks untangling it. After that, I always verify the exact legal name on the account before initiating any wire larger than a few hundred dollars. ACH errors tend to resolve themselves within a few days because the system has reconciliation built in. Wires do not have that safety net. Third-party apps like Zelle, Venmo, or Cash App sit between these methods. Zelle works directly through participating banks and uses a real-time network. You need the recipient's email or phone number registered to their bank. The money arrives instantly. It's free. The catch is that Zelle has no dispute process. If you send money to the wrong person or get scammed, your bank will not reverse it. This is the single most common complaint I see, and it's the reason I caution people against using it for anything other than transferring money to someone they know personally and trust completely.
Setting Up The Transfer
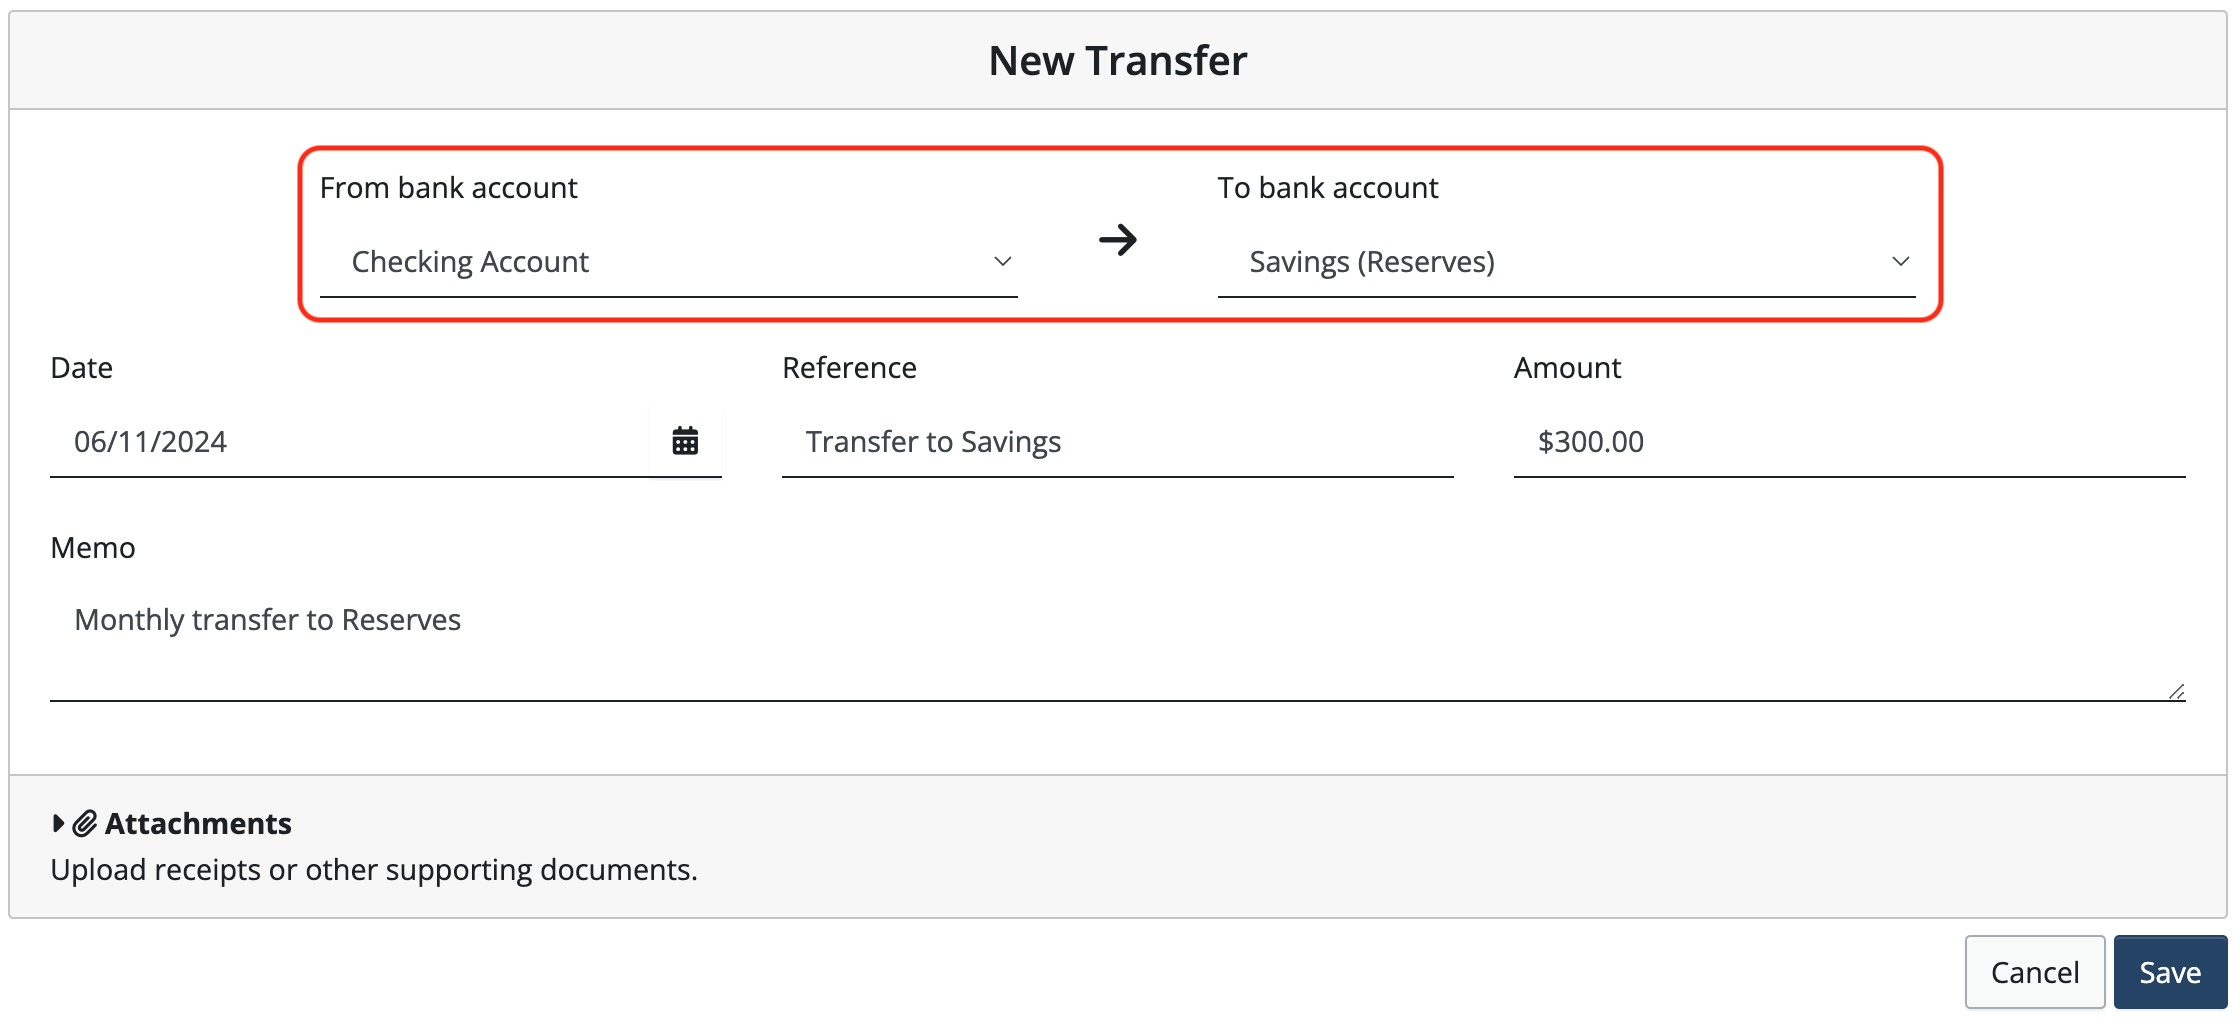
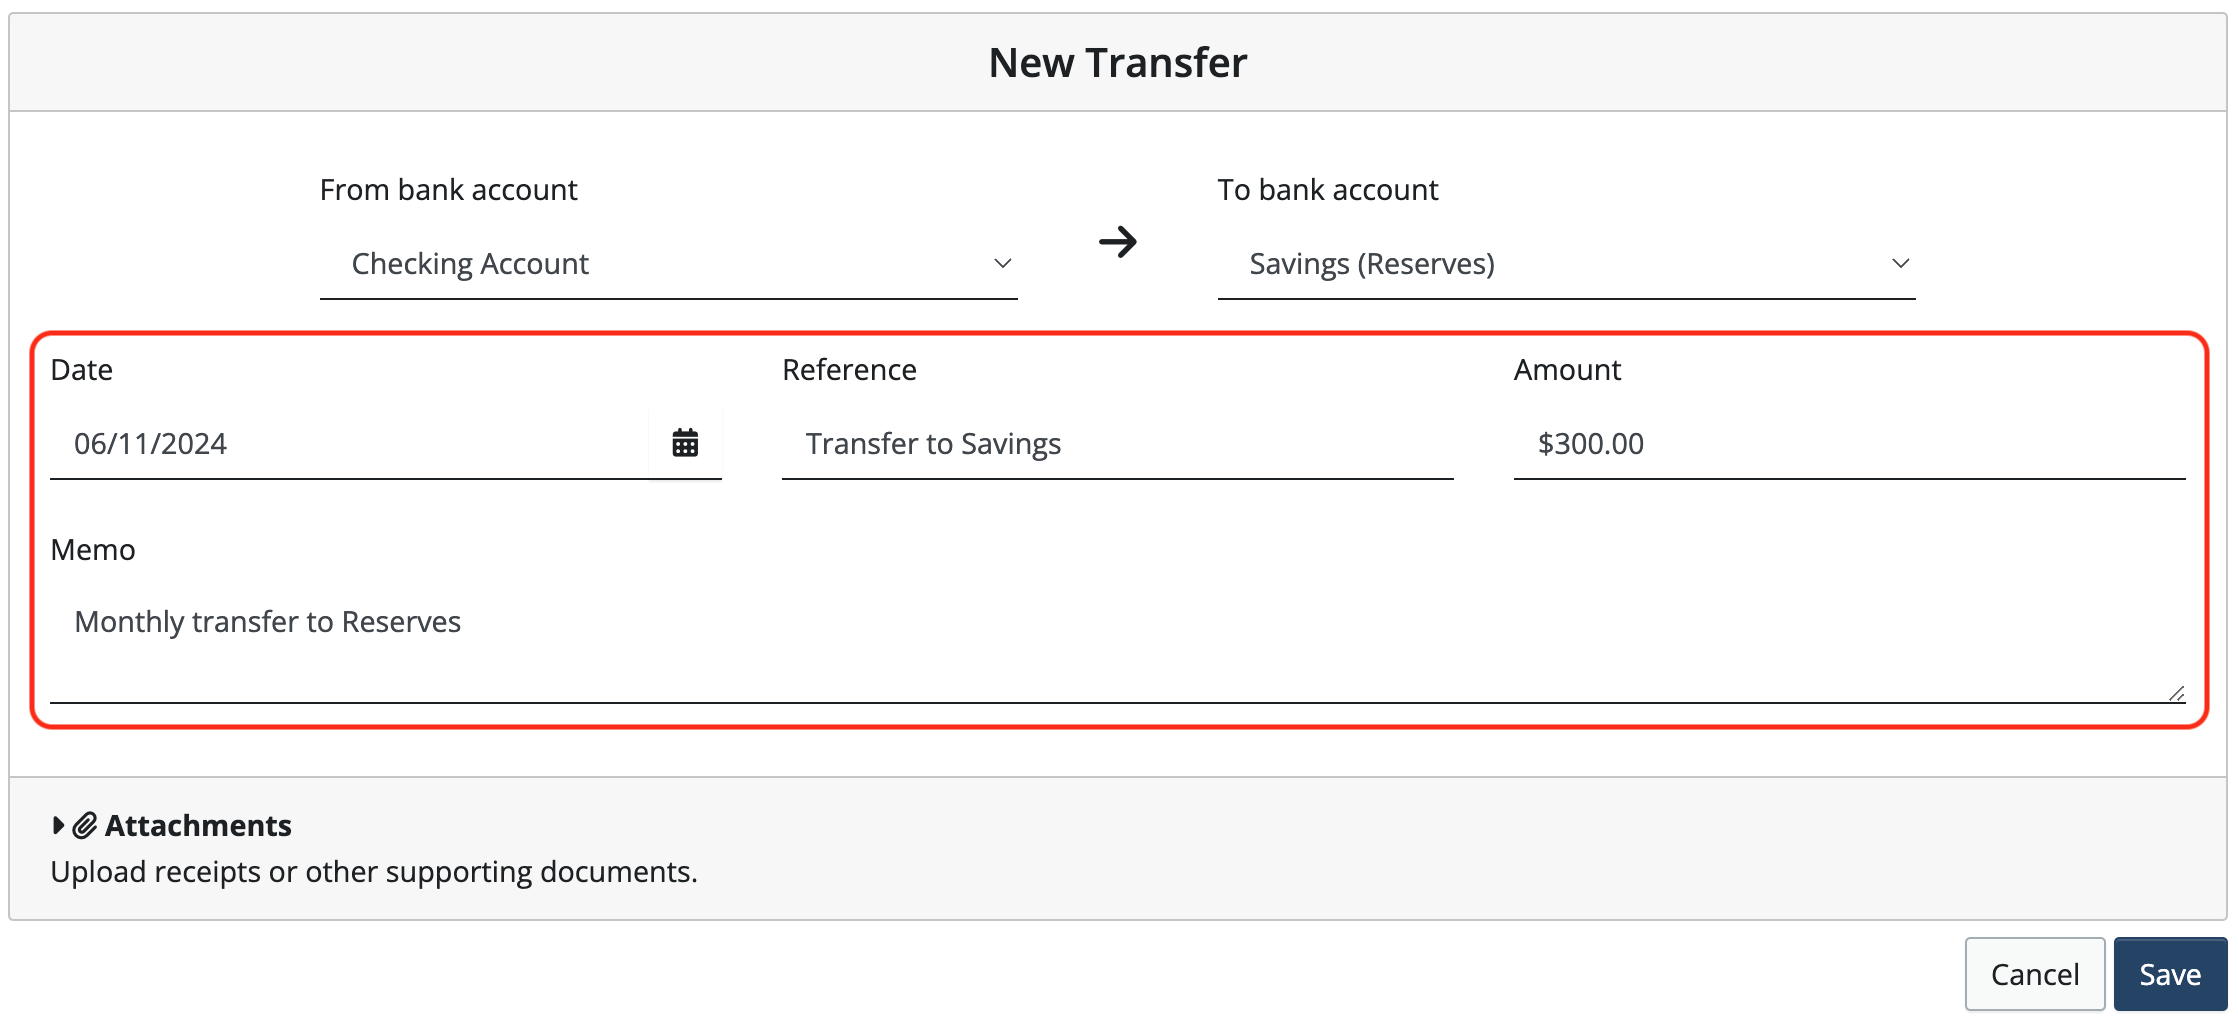
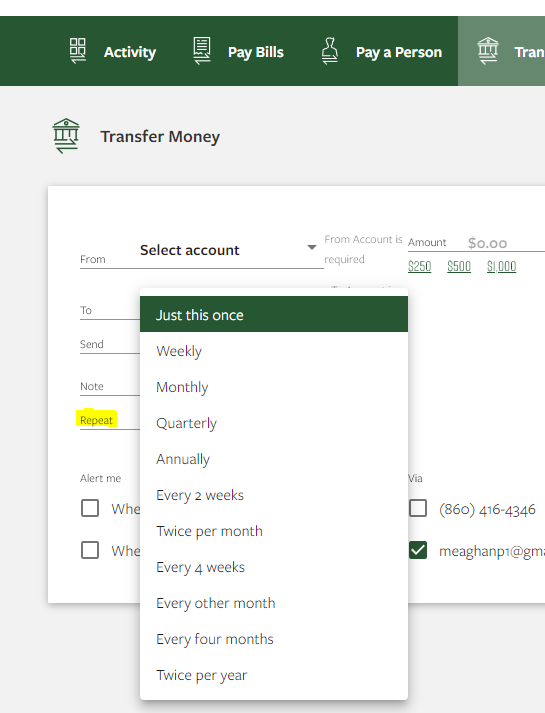
Log into your online banking. Look for a transfer or payments section. There will be options to transfer between your own accounts at the same bank, which is immediate and free, or to an external account, which is what you want for another bank. You'll add the external account first. This usually requires entering the routing number, account number, and account type—checking or savings. The bank will verify the account in one of two ways. Some institutions make instant micro-deposits. They send two small amounts, usually less than a dollar each, to the destination account. You look up those amounts in your online banking and enter them to confirm ownership. This takes about twenty minutes. Other banks take one to two business days and send a single verification deposit instead. The total setup time is minimal either way. Once the account is verified, you can initiate a transfer. Enter the amount, review the details, and confirm. For ACH, you can sometimes schedule it for a future date. Wires generally execute immediately upon confirmation. Real-time payments also execute immediately but are irrevocable in most cases.
Get the Full Details
There is a limit to how much you can move. Your bank sets daily and monthly transfer limits. Standard ACH limits are often ten thousand dollars per day. Wires can go much higher, sometimes up to a million or more, but the receiving bank may impose its own cap. If you need to move a sum that exceeds your limit, you have two options. You can request a temporary limit increase through your bank's customer service, which usually takes one business day to process. Or you can split the transfer across multiple days. ACH transfers do not stack—if you initiate three separate five-thousand-dollar transfers on the same day, your bank will likely batch them into a single ACH file, and the limit applies to the total.
What Goes Wrong
The most frequent issue is a mismatch between the name on the receiving account and the beneficiary name you entered. With ACH, this usually results in a return within two to five business days, and the money comes back to you. With wires, the funds may get stuck at the intermediary bank and require manual intervention to resolve. The second most common problem is entering the wrong routing number. Some community banks have different routing numbers for ACH versus wire transfers. If you use the ACH routing number to send a wire, the transfer fails or arrives at the wrong bank entirely. Always confirm which routing number applies to the transfer type you're using. Another pitfall is initiating a transfer on a Friday afternoon or a holiday. ACH networks do not process on weekends or federal holidays. A wire sent at 4pm on a Friday will not begin processing until the next business day. If you need the money there by Monday morning, a standard ACH is too slow. You need a wire or a real-time payment option if both banks support it. There is also the matter of hold times on the receiving end. Even after an ACH transfer posts to the recipient's account, some banks place a hold on the deposited funds for one to two business days before they become available for withdrawal. This is a policy decision by the receiving bank, not a technical limitation. If someone is expecting your transfer to cover a time-sensitive payment, tell them about this possibility upfront. An unexpected hold can cause missed payments on their end.
I have also seen people confuse IBANs with regular account numbers. IBANs are used in Europe and some other regions. They are longer, include country codes, and serve as both the account identifier and the routing information. If you are transferring internationally, you need the recipient's full IBAN along with their BIC or SWIFT code. Domestic transfers do not use IBANs. Using an IBAN format on a domestic transfer will cause the transfer to fail, and in some cases it can delay the entire batch file your bank is processing.
Choosing The Right Method
If speed does not matter and the amount is under your daily ACH limit, use ACH. It is free and has built-in error correction. If you need the money today and the amount is within your wire limit, use a domestic wire. You will pay the fee, but the money is there the same business day. If both your bank and the recipient's bank support real-time payments and the amount is modest, use that option for instant settlement at zero cost. International transfers are a separate category entirely. They involve SWIFT networks, intermediary banks, and currency conversion. Expect to pay fifteen to fifty dollars in fees plus a markup on the exchange rate. Settlement takes one to five business days. If you are moving money across borders regularly, look into specialized services like Wise or Revolut, which typically offer better rates and lower fees than traditional banks. A standard bank wire is fine for an occasional international transfer. It is not competitive if you do this regularly. The bottom line is that the infrastructure exists and it is straightforward to use. The complexity comes from edge cases, timing, and not understanding the differences between the rails. Pick the right one for your situation, verify the account details before you hit submit, and keep a record of the transaction confirmation number. That number is your only proof if something goes wrong.