Most people start by assuming the facility will handle their insurance. That assumption costs them time and money, usually both. I have sat across from patients who were referred to a hyperbaric clinic, signed the paperwork, showed up for three sessions, and then got a bill for $3,600 because nobody verified coverage before treatment began. The facilities are not always configured to do that verification correctly either. They operate on scheduling assumptions. You have to be the one pushing back.
The first thing I learned is that insurance coverage for hyperbaric oxygen therapy is extremely condition-specific. Medicare covers decompression sickness, carbon monoxide poisoning, radiation tissue damage, diabetic wounds that refuse to heal, and a handful of other indications. Most private plans mirror Medicare but add their own restrictions. If your condition falls outside those categories, coverage drops off sharply. Compensatory therapies like treating Lyme disease or autism with HBOT almost never get approved by any standard insurer. Do not expect a prior authorization for those.
What Hyperbaric Oxygen Therapy Covered By Insurance Actually Looks Like
Getting covered requires a specific sequence. Your physician has to document medical necessity with ICD-10 codes that match a covered indication, the facility has to submit a prior authorization request through the correct portal, and you often have to provide records spanning several months showing that conventional treatments were attempted and failed. That last part is where most applications get denied on the first try.
I once had a patient whose application was denied because the referring doctor had only documented that the wound was slow-healing. Slow-healing is not a covered diagnosis. The fix was straightforward but inconvenient. We pulled wound culture results, tissue biopsy reports, and a timeline showing two years of failed debridements and negative pressure therapy. The second submission, sent to a different utilization management company, got approved within four business days. The denial had been entirely administrative, not clinical.
You should also know that many plans require the treatment to happen at an ACCE-accredited facility. If you are getting this done at a non-accredited center, your insurer may deny the claim even if the indication is valid. That is not a negotiation point. It is a hard gate.
How the Sessions Actually Work in Practice
A typical session involves lying in a chamber pressurized to two to three atmospheres while breathing 100% oxygen. Most treatments last 90 to 120 minutes. The number of sessions varies wildly depending on the condition. Diabetic foot ulcers might need forty sessions. Radiation cystitis might resolve in twelve. Decompression sickness can be treated in just a few. Your insurance plan will usually cap the number of covered sessions, sometimes at twenty per benefit year. Pushing for more requires another prior authorization with new clinical evidence, which resets the clock.
The cost difference between in-network and out-of-network is brutal. An in-network session might carry a $30 copay. An out-of-network session can hit $400 or more per visit. Some plans cover nothing at all for out-of-network HBOT, leaving you with the full bill. I always tell people to confirm network status with the insurer directly, not with the clinic. The clinic's list of accepted plans is often outdated.
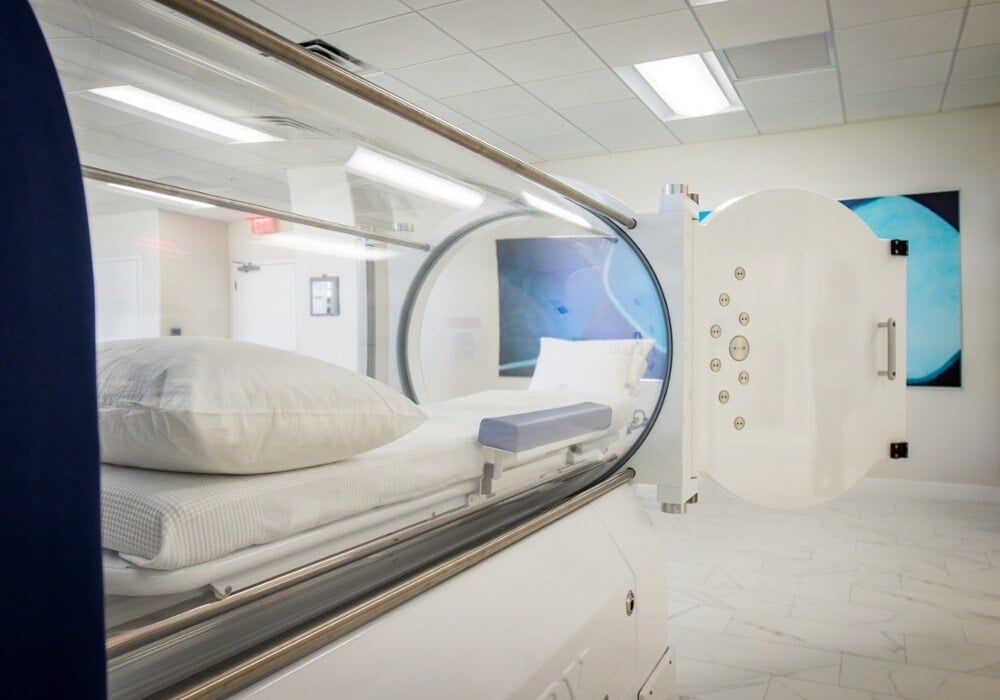
One detail that trips people up is the difference between monoplace and multiplace chambers. Multiplace chambers, where you share space with others and breathe oxygen through a mask, are the standard for most covered indications. Monoplace chambers, which are smaller glass tubes, are often used in alternative medicine settings and are rarely covered by insurance. If your treatment plan involves a monoplace chamber, assume it will be self-pay unless you have a very unusual policy.
Common Pitfalls That Lead to Denials
The most frequent denial reason is insufficient documentation of failed conservative treatment. Insurers want to see that you tried antibiotics, wound care, and offloading before they approve hyperbaric treatment. Skip that paper trail and the claim gets rejected. A secondary common reason is coding errors. HCPCS code G0298 is for monoplace chamber treatment. HCPCS code G0321 is for multiplace. Using the wrong one gets the claim sent back or denied outright.
Another issue is that some plans require treatment to occur in a hospital-based unit rather than a standalone clinic. If your plan has that restriction, a standalone facility will not be covered even if it is accredited. Check your summary plan description for that language. It is easy to miss.
I also learned the hard way that some insurers treat HBOT differently depending on whether it is delivered as part of a hospital stay or as outpatient care. If you are admitted to the hospital and receive HBOT during that stay, your plan may cover it under your inpatient benefits with a much lower coinsurance rate. Getting admitted for HBOT is not always possible since it is usually an outpatient procedure, but in cases where your condition requires concurrent hospital care, combining the two can significantly reduce your out-of-pocket cost.
What You Should Do Before Scheduling
Call your insurance company. Ask for the specific medical policy number that governs hyperbaric oxygen therapy. Request a copy of that policy in writing if they will send it. Read it. It will tell you exactly which indications are covered, how many sessions are allowed, whether accreditation is required, and what documentation triggers approval. Do not skip this step. The policy document is the only thing that matters, not what a receptionist tells you on the phone.
Then call the clinic and ask them point blank whether they have successfully obtained prior authorization for your specific diagnosis under your specific plan. If they hesitate or give you a generic answer, that is your signal that they do not have a reliable process for this. Find a different facility. The right clinic will have submitted these prior auths before and know the exact workflow. The wrong clinic will make you wait three weeks and then ask you to pay upfront while they figure it out.
Pre-authorization does not guarantee payment. It guarantees that the insurer has reviewed the request and found it medically necessary under their criteria. You can still get a denial after the fact if they audit the claim and decide the documentation was insufficient. Keep copies of everything your doctor submits. Every note, every image, every lab result. If the claim gets contested, you need that file immediately.
Gallery Hyperbaric Oxygen Therapy Covered By Insurance
Is Hyperbaric Oxygen Therapy Covered by Insurance? - YouTube
Is Hyperbaric Oxygen Therapy Covered by Insurance?
Is Hyperbaric Oxygen Therapy Covered by Insurance? - R3 Wound Care & Hyperbarics
Insurance coverage for hyperbaric oxygen therapy in acutely compromised tissues
Is a Hyperbaric Chamber Covered by Insurance in 2026?