The Numbers Are Unkind But Not Always Final
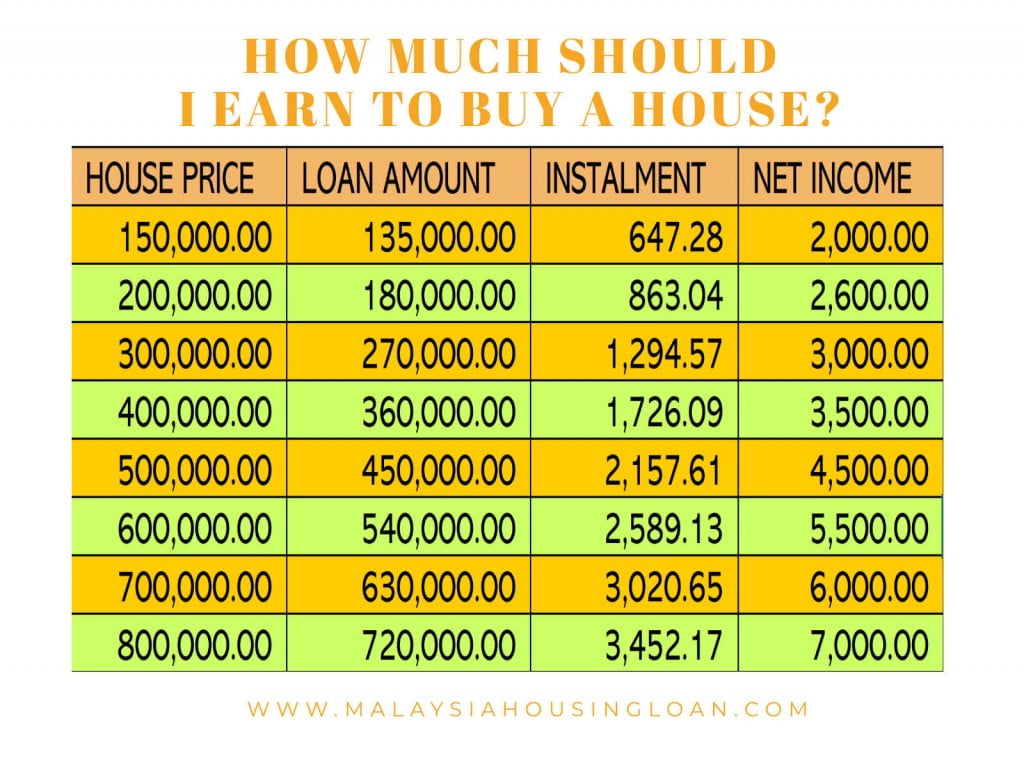
A $25,000 annual salary translates to roughly $2,083 per month before taxes, or about $1,600 take-home depending on your state and deductions. Conventional lending guidelines say your housing payment should not exceed roughly 28% of gross income, which puts you around $485 a month max for principal, interest, taxes, and insurance. That range typically buys a $60,000 to $80,000 home in most American cities, assuming a 3% to 5% down payment and a reasonable interest rate. In a lot of places, that house doesn't exist anymore, and even where it does, the condition is usually rough. Short answer: yes, technically. The longer answer involves a handful of program pathways that don't follow conventional underwriting logic. FHA loans are the most common route at this income level because they allow a 3.5% down payment and accept credit scores down to 580 with that minimum. You can also look at USDA loans if you're in an eligible rural area, which offer zero down payment options, though the income limits for those programs vary by county and cap at certain thresholds. Many states and local municipalities have first-time homebuyer programs with down payment assistance, closing cost grants, or tax credit programs stacked on top of your primary loan. Those programs are what actually make this scenario workable, not the base mortgage product itself. The tricky part is that lenders look at your debt-to-income ratio holistically. If you have $400 a month in car payments, student loans, or credit card minimums, that eats directly into the amount they will lend you. I worked with a client last year whose reported income was exactly in this bracket. She had a $220 monthly student loan payment and a $180 auto loan. Her PITI estimate came in well above the 28% front-end ratio, but her back-end DTI sat at 43%, which is near the FHA ceiling. We resolved it by having her pay down the auto loan before applying, which dropped her DTI to 35% and immediately unlocked about $25,000 more in qualifying purchase power. That one move changed everything about what she could consider.
How Underwriters Actually Evaluate Low Income Buyers
Most people assume the underwriter only looks at gross annual salary. That's wrong. They look at your actual monthly obligations and compare them against your verified monthly income. Two things confuse buyers constantly. The first is that not all income counts equally. Overtime, bonuses, and commission income often require two years of documentation to be counted. If your $25,000 includes $4,000 in irregular overtime, the underwriter may only count your base salary, which effectively lowers your qualifying income. The second is that some assistance funds don't need to be repaid, and that changes the math in a way most first-time buyers miss entirely. I discovered this the hard way with a buyer in Ohio who was excited about a local down payment assistance grant. He applied through a conventional loan track and got denied because the grant funds weren't structured correctly for that loan type. He switched to FHA, the same grant became acceptable, and the entire process moved forward within ten days of the switch. The loan program mattered more than his credit or income. Most people don't realize that FHA, conventional 97, VA, and USDA all have different rules about what assistance sources they accept, and using the wrong one is a common reason low-income applications stall out before they ever reach the appraisal stage.
The Programs That Actually Work At This Income Level
FHA loans remain the workhorse here. They allow 3.5% down with a 580 credit score, and the mortgage insurance premium structure is predictable enough that you can calculate your total monthly payment before you start house hunting. The upfront MIP is 1.75% of the loan amount and gets rolled into the balance. On a $75,000 loan, that's roughly $1,313 added to your principal. The annual MIP runs 0.55% of the original balance, split into monthly payments. For a $75,000 loan at 6.5% interest over 30 years, your principal and interest would be about $474 per month, plus the annual MIP of roughly $34, bringing your total PITI to approximately $560 to $600 once property taxes and homeowners insurance are factored in. USDA loans deserve serious attention if you qualify geographically. They require no down payment, which eliminates the biggest barrier for someone at this income level. The annual fee is 0.5% of the loan amount and the guarantee fee is 1% at closing. Property eligibility can be checked on the USDA website by address, and a surprising number of suburban areas qualify. The downside is that USDA has income caps. For most counties, the 2024 to 2026 income limit for a single borrower is around $103,000 to $115,000 depending on location, so a $25,000 salary fits comfortably under that threshold. The catch is that USDA properties often have stricter appraisal requirements than FHA, and some sellers and real estate agents don't understand the program well enough to give it a fair shot. State and local first-time homebuyer programs vary wildly. Some offer deferred second liens with zero interest that are forgiven after ten years of occupancy. Others provide matching grants up to $10,000 or $15,000 for down payment and closing costs. Michigan's Home Ready program, Tennessee's H.O.M.E. program, and California's DHAP assistance are examples of programs that have helped buyers in this exact income range close successfully. The application process for these programs often requires a homebuyer education course, which costs between $100 and $200, but that cost is usually recouped in the first month of home ownership through better financial decisions. I recommend completing the education course before you start looking at properties because some programs require proof of completion at the time of application.
Get the Full Details
What Most People Get Wrong About Buying Below 30K
The biggest mistake is starting the house hunt before getting fully pre-approved with the right program. A pre-approval letter from a lender who specializes in conventional loans is almost useless for someone making $25,000 a year. You need a pre-approval from someone who understands FHA and has access to local down payment assistance programs. I've seen buyers make offers on homes they couldn't actually qualify for because their pre-approval was based on optimistic assumptions about income calculation or unavailable assistance funds. Another mistake is ignoring the total cost of ownership. A $70,000 FHA loan might look affordable until you add property taxes, homeowners insurance, HOA fees, and maintenance. Older homes in affordable price ranges often need a new roof, updated electrical, or repaired plumbing within five years of purchase. I had a client in Texas who bought a $65,000 home with no money left over for immediate repairs. The water heater failed three months later, and she had to choose between replacing it or skipping mortgage payments. Budget at least $3,000 to $5,000 in a reserve fund after closing, even if you think the house is move-in ready. That reserve will prevent a single repair from derailing your entire homeownership plan. Credit score expectations at this income level are also misunderstood. You don't need 740 to get a good rate, but the difference between a 620 score and a 680 score on an FHA loan can be 0.5% to 0.75% in interest rate. On a $75,000 loan at 6.5% versus 7.0%, that's roughly $30 to $40 more per month over the life of the loan, which adds up to nearly $1,500 in extra interest. Paying off a single collections account or bringing one credit card below 30% utilization can sometimes move the score enough to make that difference worthwhile. It's worth running the numbers before you spend money on credit repair, because not every point gained will translate into a rate improvement.
The Reality Check
Buying a home on $25,000 a year is possible but narrow. Your options are limited to FHA, USDA, or state assistance programs. Your purchasing power is constrained to older or smaller properties in lower-cost markets. You will need to minimize existing debt before applying. You will need a reserve fund for immediate repairs. You will need a lender and real estate agent who understand these programs, because a conventional-focused professional will steer you toward options that won't work and waste months of your time. The process typically takes three to four months from pre-approval to closing if everything goes smoothly, and six to nine months if you're waiting for assistance program approval or credit issues to resolve. It's slower than most people expect, but the alternative to this path is usually renting forever, which costs significantly more over the same timeframe.