What The Book Actually Teaches
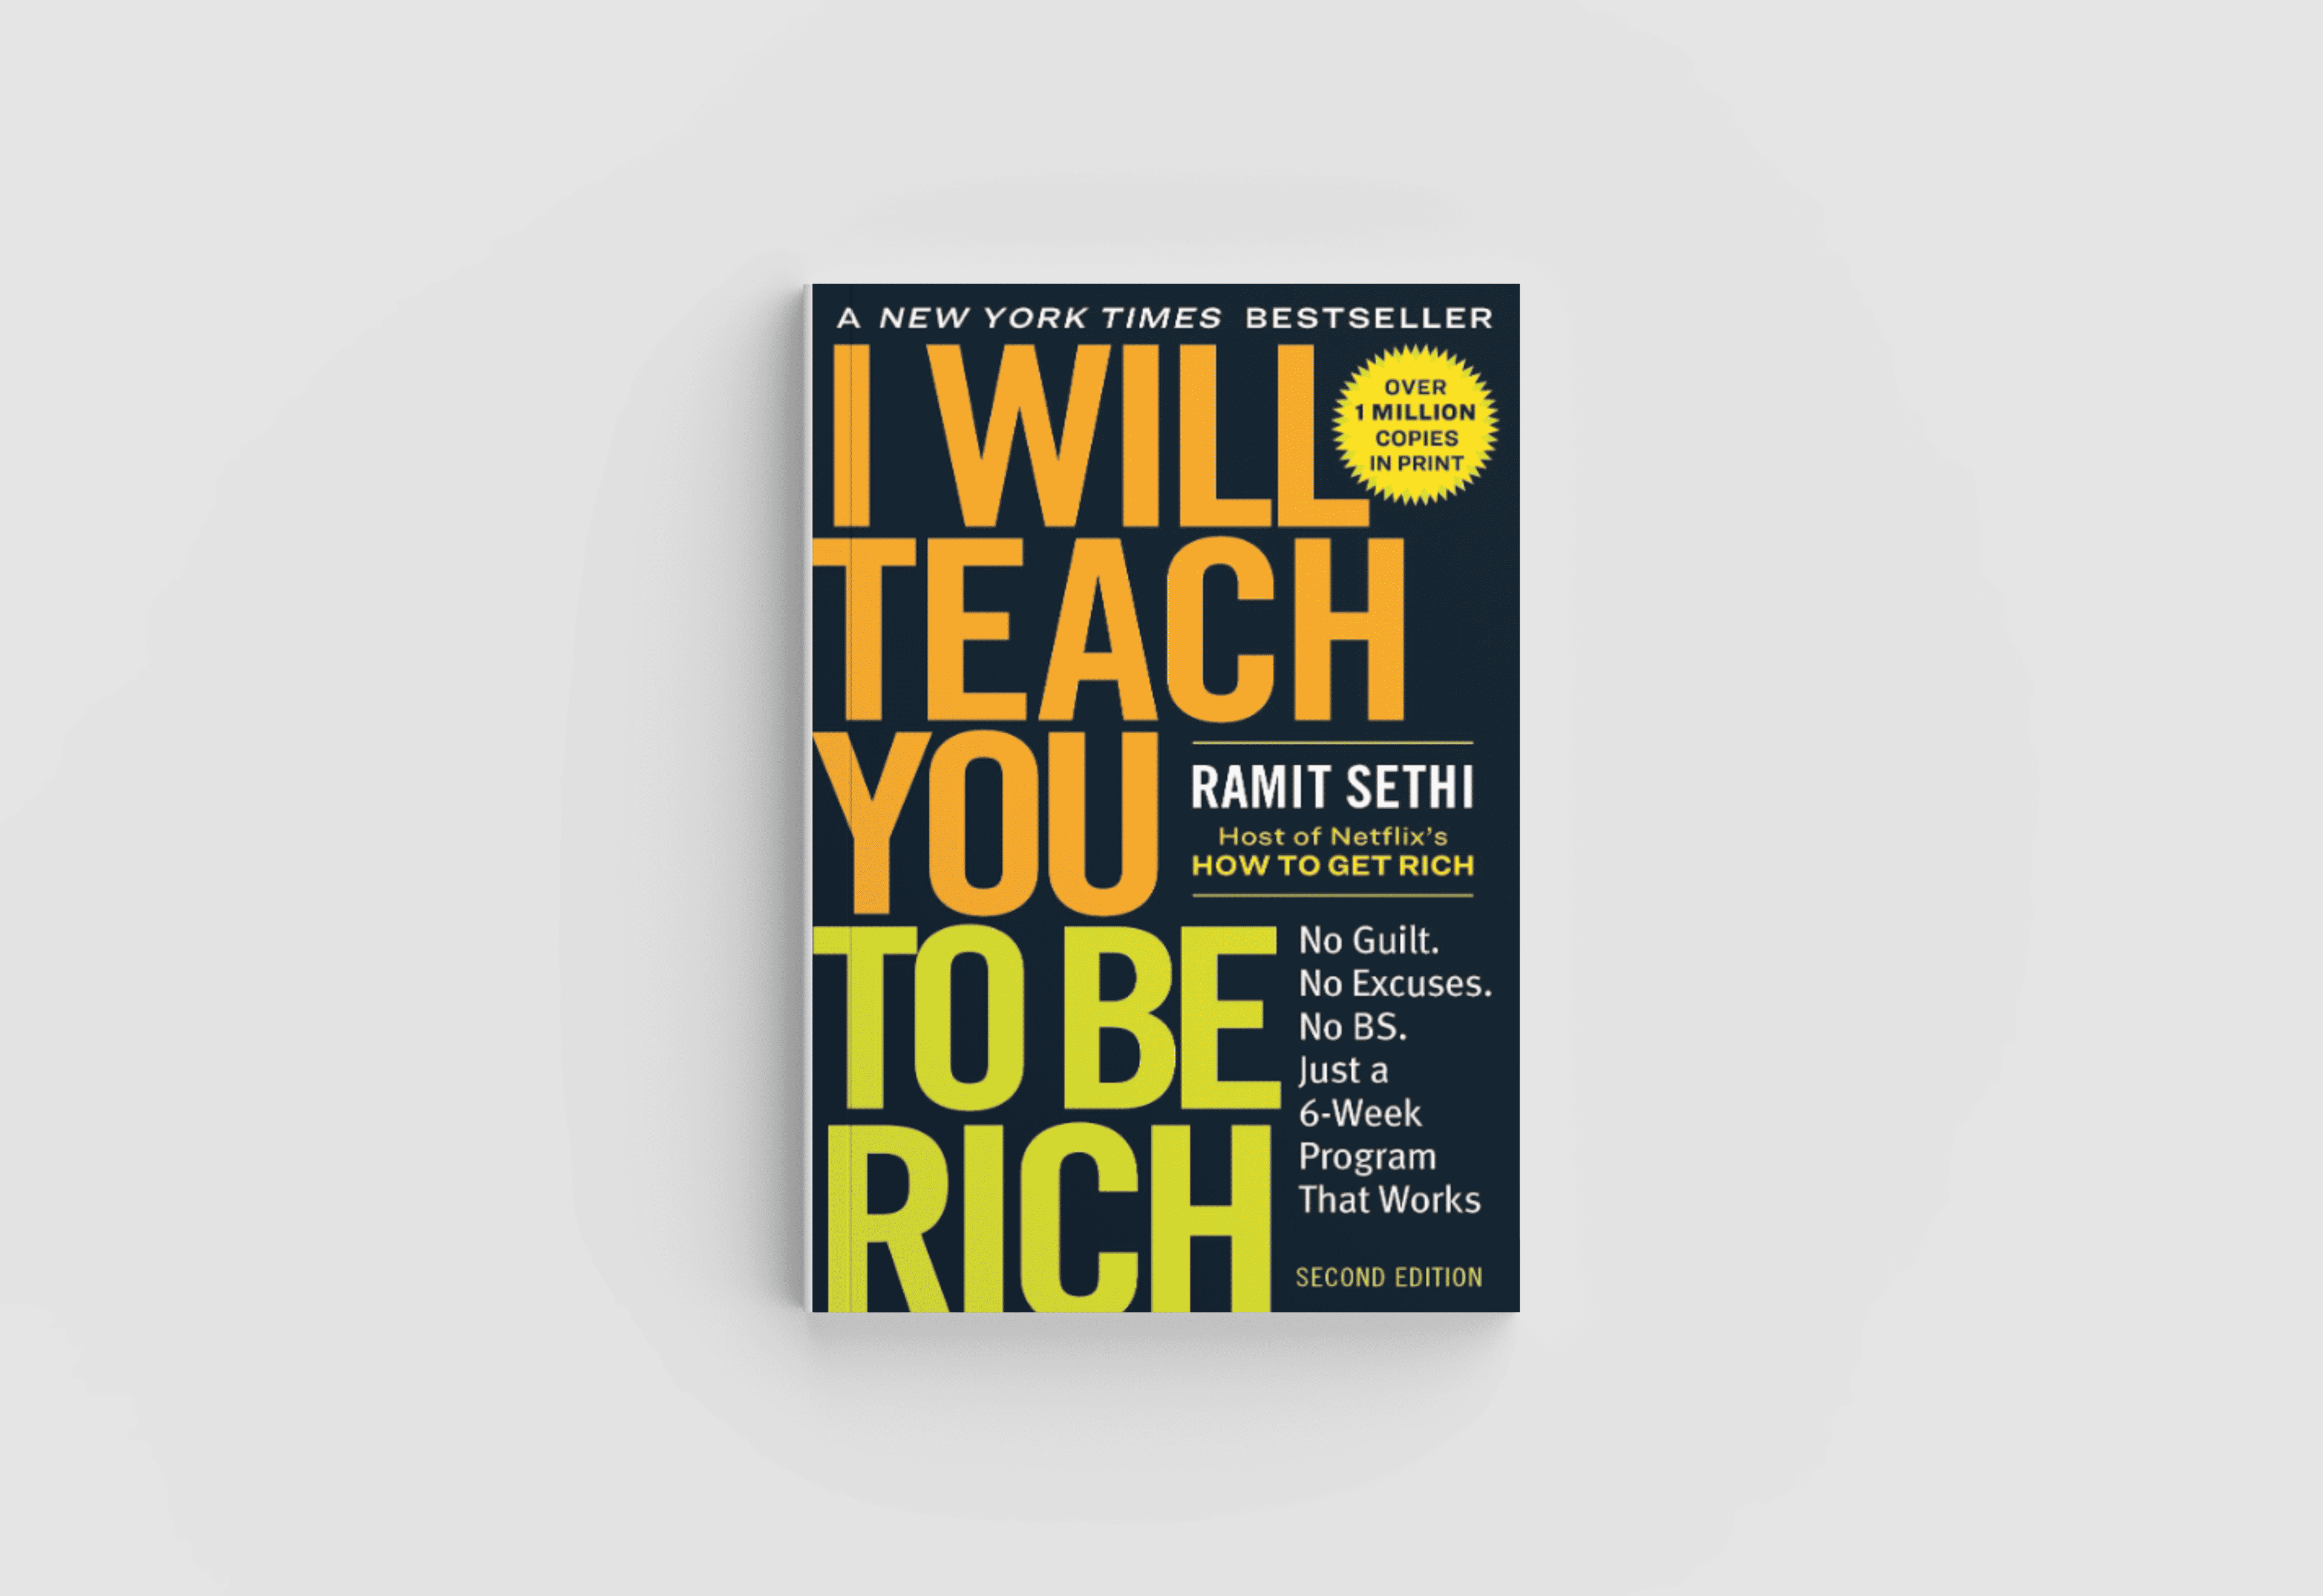
The core idea is that most personal finance advice focuses on cutting lattes and missing out. Ramit's approach is different. He calls it conscious spending instead of budgeting. You decide where your money goes upfront, then spend guiltlessly on the things you genuinely value while automating everything else. The book is structured around six-week programs. Each week covers a specific topic — setting up accounts, negotiating salary, investing in index funds, conscious spending plans, building your "rich life" definition, and scaling your wealth. The framework is straightforward enough that you can work through it without needing a finance background.
I Will Teach You To Be Rich By Ramit Sethi Download Options
You can pick up the book in paperback, Kindle, or audiobook format from most major retailers. The latest edition includes updated tax information and some newer investment options since the original 2009 release. I'd recommend the Kindle version if you want to annotate it, or the audiobook if you prefer listening during commutes. The content is essentially the same across formats. If you just want the PDF version, it circulates on various file-sharing sites, but supporting the author by purchasing it directly is the straightforward choice and ensures you get the updated edition.
How The System Works In Practice
The automation piece is where most people stall. Ramit walks you through setting up a specific account structure — checking, savings, investing, and bills — all with automatic transfers. The logic is that if your money moves on its own, you don't need willpower. You remove the decision entirely. Here's the part beginners consistently mess up. The four-account setup he recommends sounds clean on paper, but in reality most banks don't support perfect sub-account segmentation. I had to work around this by using a primary checking account with labeled sub-savings through my credit union's internal budgeting tool, then setting up automatic transfers on payment dates. It added maybe 10 minutes per month of manual oversight but achieved the same result. If your bank situation is similarly clunky, don't abandon the framework. Adapt it to your bank's actual capabilities. The negotiation chapter is probably the highest-ROI section. Ramit gives you actual scripts to use when asking for a raise or countering a job offer. I've used his framework twice — once for a salary discussion and once when an employer presented a counteroffer. Both times the approach worked because it frames the conversation around value and market data rather than personal need. Employers respond better to "based on my research, this role commands X" than "I need more money because rent went up." The script in the book gives you language for both scenarios.
Get the Full Details
What The Book Gets Wrong Or Misses
The biggest limitation is that the book assumes a certain income floor. If you're making less than roughly $40,000 a year, some of the strategies — particularly the investment and automation pieces — don't land the same way. You're not going to optimize your way out of a cash flow problem at that level. The book acknowledges this somewhat but doesn't give enough attention to the early-stage survival phase. For people in that position, paying down high-interest debt should come before any of the investing frameworks. The credit card strategy is another area where context matters heavily. Ramit recommends getting a rewards credit card and paying it off monthly. This works perfectly if you have the discipline to never carry a balance. I know plenty of people who tried this and ended up with balance transfer fees and interest charges that wiped out any rewards. If you've ever struggled with credit card debt, skip the rewards card phase entirely and focus on building a spending floor first. His investment guidance centers on low-cost index funds through providers like Vanguard and Schwab. This is sound advice for most people. But it doesn't address situations like self-employment where you might benefit more from a SEP IRA or Solo 401(k) before touching a regular brokerage account. The book's one-size-fits-all approach to investing vehicles is its weakest point.
What You Should Actually Take Away
The book's real value isn't in any single tactic. It's in the psychological shift from scarcity thinking to conscious allocation. Most people I talk to who've actually read and applied it report that the biggest change was deciding what "rich" means to them personally rather than following someone else's template. That definition drives every other decision — how much to save, what to splurge on, whether to rent or buy. If you're looking for a detailed step-by-step manual with financial spreadsheets, this isn't quite that. It's more of a mindset framework with tactical chapters you can dip into as needed. The six-week structure is useful if you want to move through it methodically, but you don't need to follow it rigidly. Work through the sections that address your current bottleneck and circle back later. The audiobook version runs about nine hours. The paperback is around 280 pages. Either way, you're looking at a weekend read if you move through it quickly, or a month-long project if you apply each chapter before moving forward. The second approach usually produces better results because the automation changes require actual setup time.
Most people finish the book and immediately try to implement everything at once. That's a mistake. Pick one or two systems — the account automation and the conscious spending plan are the highest impact — and set those up properly before touching the investment or negotiation material. Getting the foundation right matters more than speed.