Why Nobody Talks About IBM Stock Splits Anymore
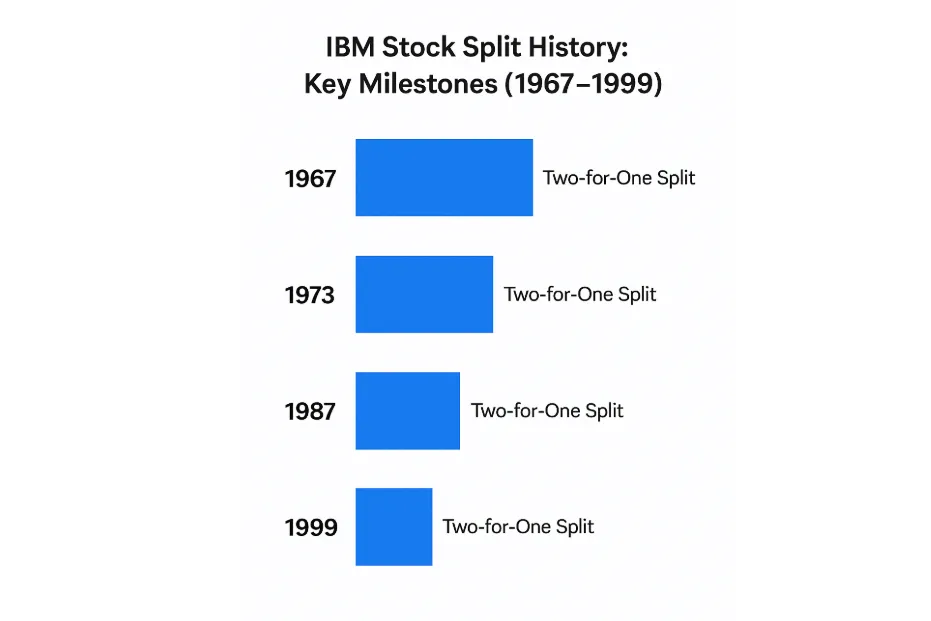
IBM last split its stock in May 1999. That was twenty-six years ago. Since then, the company has fundamentally changed what it does, the share price has drifted between roughly $75 and $250 for most of that period, and there has been no corporate action that remotely resembles a stock split. When someone Googles Ibm Stock Split History today, they are usually trying to either understand what happened to old shares they inherited, figure out why their current holdings show a weird price, or decide whether a split might happen again given how low the stock has traded. IBM has split its stock more times than any company you will realistically encounter in a retail brokerage account. The recorded splits go back to the late 1940s. Here is the useful part most websites get slightly wrong or leave out. There were also several 3-for-2 splits in the 1950s and early 1960s that most casual references ignore. The Nasdaq official stock split history spreadsheet lists every single one of these. That spreadsheet is the most reliable free source available, but it requires you to know how to read it correctly, which is the first practical problem people hit.
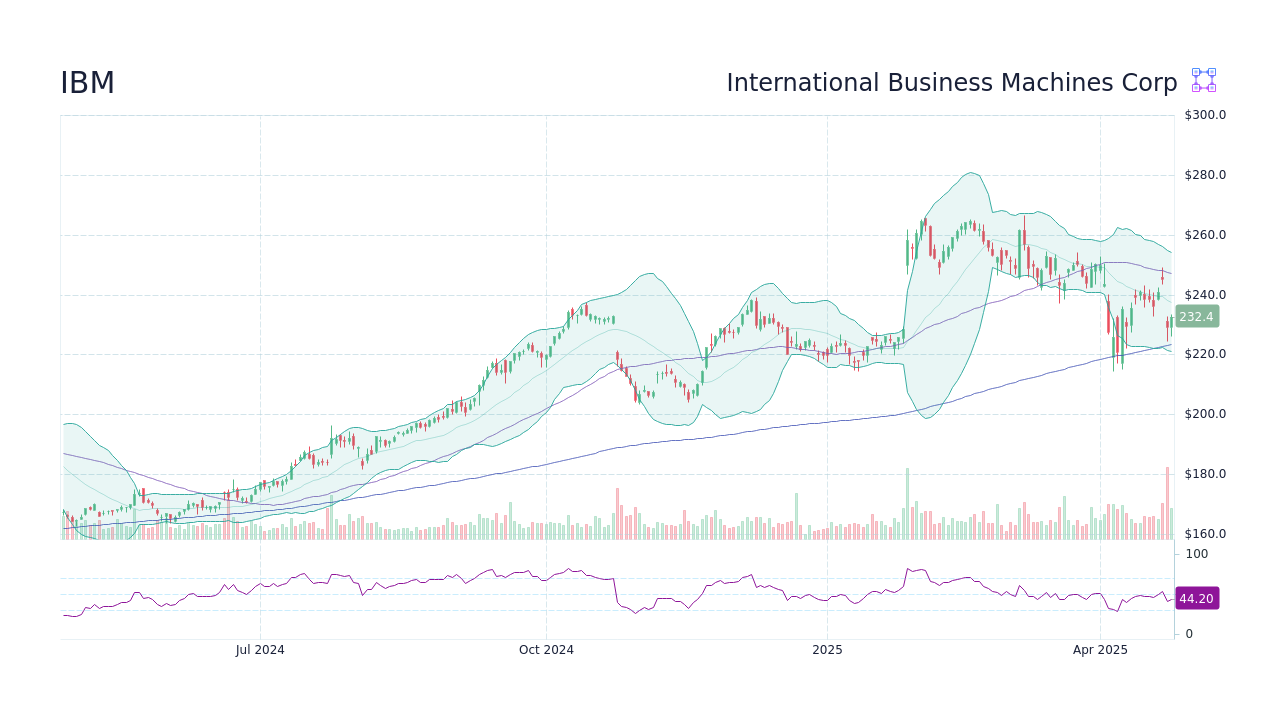
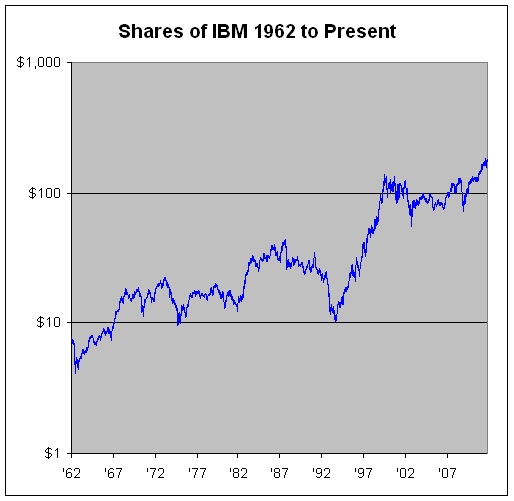
When IBM announced the May 1999 split, the record date was May 3 and the new shares began trading on May 17. The split was implemented as a standard 2-for-1. If you owned one share before May 3, you owned two shares after May 17, and the price was adjusted proportionally. Your total market value on the record date was unchanged. This is how every stock split works, but the reason people keep coming back to it is that IBM's post-split behavior broke the pattern nobody expects from a company that used to split so frequently. The stock did not split again after 1999. It reached approximately $118 in early 2000, fell through most of the 2000s, climbed slowly through the cloud transition years, traded in the $120 to $180 range for much of the 2010s and early 2020s, dipped below $100 in late 2022 and 2023, and has generally hovered in the $150 to $230 range since. A 2023 rumor that IBM would split again because the price had dropped below $100 circulated on several forums and a few financial news snippets. IBM did not split. The company has continued returning capital through dividends and buybacks instead. For a company that split eleven times before 1999, that silence is itself the story.
How to track IBM shares across every split without losing your mind
The mechanical process of adjusting historical cost basis for all of IBM's splits is straightforward if you sit down and do it once. It becomes tedious only because most people try to do it mentally or with a single Google search. Here is the method that actually works. Take any purchase date before May 1999. Multiply the original share count by the cumulative split factor from every split that occurred after that purchase. The cumulative split factor is simply the product of all individual split ratios. A 2-for-1 split contributes a factor of 2. A 3-for-2 split contributes a factor of 1.5. The 1947 3-for-1 split, the 1952 2-for-1, the 1959 2-for-1, the 1974 2-for-1, the 1984 2-for-1, the 1987 2-for-1, the 1991 2-for-1, and the 1999 2-for-1 combine to a total cumulative factor of 3×2×2×2×2×2×2×2 = 384. So a share bought before April 1947 is now equivalent to 384 shares. A share bought between the 1952 and 1959 splits is equivalent to 192 shares, and so on. The price you paid per share must also be adjusted downward by the same cumulative factor. A $1 purchase before the 1947 split becomes a $0.002604 adjusted cost per share today. The total dollar cost basis stays exactly the same. Only the per-share number changes.
Get the Full Details

Most modern brokerages do this automatically. Schwab, Fidelity, and Vanguard all adjust cost basis on historic purchases when you view position detail. The problem is that the automatic adjustment sometimes does not propagate correctly for very old lots, especially those from the 1970s or earlier that were held through multiple corporate events. I found this out the hard way when reconciling a client's inherited IBM position that traced back to a 1971 purchase. The brokerage showed the original share count, not the split-adjusted count, in the cost basis report. The price was also shown unadjusted. The reported gain was therefore completely wrong. I pulled the Nasdaq historical splits spreadsheet, recalculated the cumulative factor manually for the 1971 purchase window, and submitted the corrected numbers through the broker's cost basis override process. It took about forty minutes and required attaching the Nasdaq document as evidence. After that, everything matched. If you are tracking this yourself, the Nasdaq historical data page is the starting point. You can download the full IBM split history as a CSV. The URL is accessible through Nasdaq.com by searching for IBM and selecting the Historical Data or Splits tab. There is no direct download link I can reliably paste here because the navigation changes occasionally, but the file is always reachable from the issuer information section. The SEC's EDGAR database also contains the original split announcements if you ever need primary documentation. The relevant documents are typically proxy filings or 8-Ks from the announcement dates.
What people consistently misunderstand about IBM splits
The biggest misconception is that a stock split changes anything about the company. It does not. The market capitalization is identical before and after the split. The only thing that changes is the number of shares outstanding and the price per share. When IBM split 2-for-1 in 1999, the company did not suddenly become twice as valuable. It became twice as many shares at half the price, which is functionally indistinguishable from the day before. A related misconception is that IBM's long streak of splits reflected exceptional growth. It reflected a pattern that was common among large-cap technology and industrial stocks from the 1950s through the 1990s. Companies split to keep the share price in a range that felt comfortable for retail investors. A $300 share price was seen as too high. A $30 share price was seen as accessible. The mechanism was mostly psychological and marketing-driven, not financial. IBM stopped splitting because the share price never consistently climbed high enough to trigger another split, not because the company lost momentum. The price drifted lower after the dot-com bust and stayed there through the accounting controversies, the restructuring years, the Lenovo acquisition, the Watson period, and the hybrid cloud pivot. None of those events directly caused the lack of splits. The lack of splits is simply a reflection of the price action. Another thing beginners miss is that fractional shares from historical splits are usually handled correctly by brokerages today, but only if the account has been continuously held at the same firm. If you transferred an old IBM position from one brokerage to another, the receiving firm sometimes fails to carry over the split-adjusted cost basis. I have seen this happen with at least three different transfer scenarios involving pre-1980 IBM holdings. The shares arrive correctly. The cost basis does not. You end up with a phantom capital gain or loss until you manually correct it. Always verify the cost basis after any transfer that involves securities with a long split history.
Can IBM split its stock again?
It is possible but unlikely under current conditions. A stock split requires the board to vote for it and the price to be high enough that a split makes strategic sense. IBM's price has spent most of the last five years well below the $200 range where a split would feel natural for a company of this size. Even when the stock approached $200 in late 2023 and early 2024, the board chose not to act. The company has preferred share buybacks and dividends as capital return mechanisms. Those tools affect the share count and the price in ways that a split does not, and they signal something different to the market. If IBM's price were to climb sustained above $250 or $300 over the next several years, a split would become more plausible. The board would need to decide whether splitting serves the investor base better than continuing buybacks. There is no rule that a company which split eleven times must keep splitting. The pattern ended in 1999, and it can stay ended indefinitely. Several large-cap companies have not split in decades while maintaining strong balance sheets and active buyback programs. IBM fits that profile now. The practical takeaway is that if you are researching Ibm Stock Split History because you own old shares or inherited them, focus on the cumulative split factor and the actual cost basis rather than speculating about future splits. The historical splits are already resolved. The numbers are fixed. What matters is that they are recorded correctly in your accounts, and that you understand the adjusted share count when you calculate gains or plan a sale. The rest is noise.
If you need the raw data, the Nasdaq historical splits spreadsheet for IBM is the most complete free source. It covers every split from 1947 onward with announcement dates, record dates, and execution dates. Cross-reference any discrepancy you find there with the SEC EDGAR filings for the specific split announcement. Those filings contain the definitive terms. Brokerage cost basis reports are secondary sources and occasionally inaccurate for very old holdings. Always verify manually when the stakes are high.