Let me walk you through how to Identify The Causes Of The Economic Panic Of 1819 without the usual textbook fluff.
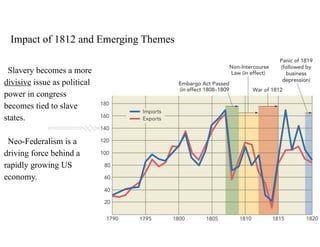
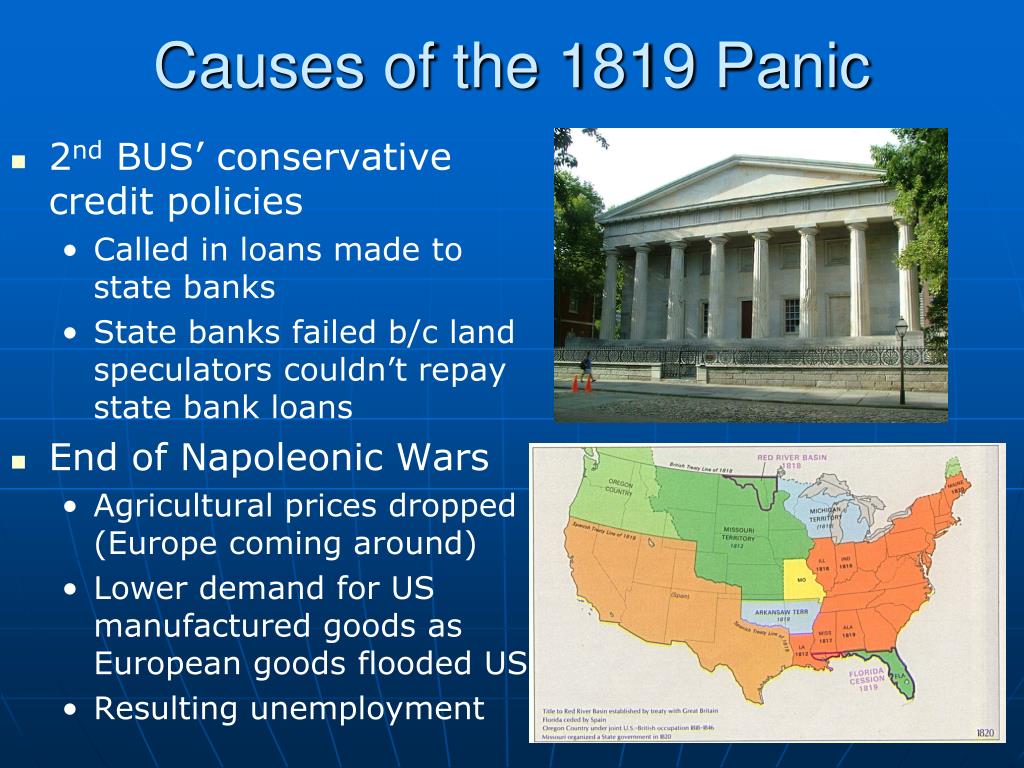
The Panic of 1819 was the United States first peacetime financial crisis, and most people who try to summarize it miss the actual mechanics. They reduce it to speculation and bank policy. That is technically correct but not useful if you want to understand what happened or apply similar analysis to other periods. The real picture is messier. The crisis started when three separate pressures converged in the same window. The United States had just finished the War of 1812. During the war, British goods flooded back into Europe once Napoleon fell, and European demand for American agricultural exports dropped sharply. Prices for cotton and tobacco fell by roughly a third between 1816 and 1818. Farmers in the western states especially felt this because they had been borrowing against land they assumed would keep increasing in value. At the same time, the Second Bank of the United States had expanded credit aggressively throughout 1816 and 1817. The bank issued notes freely, state banks multiplied their own paper money in response, and land speculation became almost universal in Kentucky, Tennessee, and Ohio. When the panic hit, the Second Bank decided to contract. It demanded that state banks redeem their notes in specie, which meant gold or silver. State banks did not have enough reserves. They called in loans. Farmers and merchants who had borrowed during the boom could not refinance. Defaults multiplied.
The presidential election of 1820 happened during this period, and the political fallout was immediate. President Monroe won nearly unanimously partly because nobody wanted to be associated with the downturn. The panic also exposed a structural weakness in the banking system. The Second Bank had no real mechanism to coordinate policy with state banks. It could demand specie payments, but it could not stop state banks from collapsing along the way. I spent more time than I care to admit trying to reconcile the data on land sales with the actual default rates, and here is the thing nobody puts in the textbooks. The land office receipts show speculation happening at the federal land offices in the West, but the actual default numbers are scattered across county court records and state bank ledgers. Most of the primary sources are still in regional archives. If you are trying to pin down the severity by state, you are going to hit dead ends fairly quickly. The workaround I found useful was cross-referencing the Second Bank annual reports with the newspapers of the affected states. Local papers like the Nashville Whig and the Western Intelligencer in Louisville reported on foreclosures and bank suspensions in real time. Those reports are messy but they contain details you will not find in secondary sources. There is one nuance that tends to get glossed over. The panic was not solely a monetary event. It was also a terms-of-trade shock. British manufacturing recovered faster after the Napoleonic Wars than economists at the time expected, which meant American farmers faced stiffer competition in European markets. The drop in export prices happened before the bank contraction tightened credit. That sequence matters because it explains why the panic spread so quickly into the real economy. It was not just that banks called in loans. It was that the income supporting those loans disappeared at the same time liquidity vanished.
Another thing people miss is how much the panic was shaped by the federal land policy. The government allowed purchases on credit with only a twenty percent down payment. When prices fell, the real value of the debt stayed the same while the collateral value shrank. Debtors were underwater in a way that felt arbitrary to them because the policy had seemed generous when it was written. This is why the panic generated such strong political resentment. It was not an abstract financial event. It felt personal. If you are researching this period, I would recommend starting with the official records of the Second Bank of the United States. You can find the annual reports and correspondence on microfilm at the Library of Congress and through several digitized archives. Then move to the state-level sources. The bank records from Kentucky and Tennessee are particularly informative, though incomplete. The National Archives holds some of the land office records, but access varies by facility. A limitation you need to accept upfront is that the data is fragmentary. There is no single comprehensive dataset for the Panic of 1819. You are working with partial records, local newspapers, and retrospective accounts. Any analysis you build will contain gaps. Do not pretend otherwise. The best you can do is triangulate between sources and be honest about what you cannot prove.
Get the Full Details
The political consequences of the panic lasted well beyond 1819. It reshaped the relationship between western farmers and eastern financial institutions. It also influenced the debate over the recharter of the Second Bank, which came up again later in the decade. Andrew Jackson used the memory of the panic against the bank in his political career, even though the timeline was complicated. If you read primary sources from the era, you will see how quickly the economic episode became a moral argument about banking power rather than a discussion of monetary policy. For anyone trying to map this to modern financial crises, the closest parallel is probably the 2008 housing collapse in structure rather than in scale. Both involved a credit expansion backed by collateral that lost value simultaneously with a liquidity crunch. The mechanisms differ. The 1819 crisis was driven by agricultural exports and land speculation instead of mortgage-backed securities, but the pattern of easy credit followed by sudden contraction is recognizably the same. I mention this because it helps with analysis, but it does not mean the two events are interchangeable. The institutional context was entirely different. If you want to go deeper, the works by historians like Joseph P. Reidy on the early republic and the collections from the University of Kentucky Press on western economic history contain useful primary source material. The Pennsylvania Gazette and the Commercial Advertiser in New York also covered the panic extensively, though their coverage was colored by the editorial positions of the time. Read those accounts with the appropriate skepticism.
The bottom line is that the Panic of 1819 was caused by a combination of falling export prices, excessive credit expansion, speculative land purchases, and a sharp monetary contraction. The interaction of those factors is what made the crisis worse than any single element alone. Understanding that interaction requires looking past the simple narrative and into the actual records, which are uneven but worth the effort if you are willing to deal with the gaps.