How to Actually Use an Illinois Wage Garnishment Worksheet Without Losing Your Mind
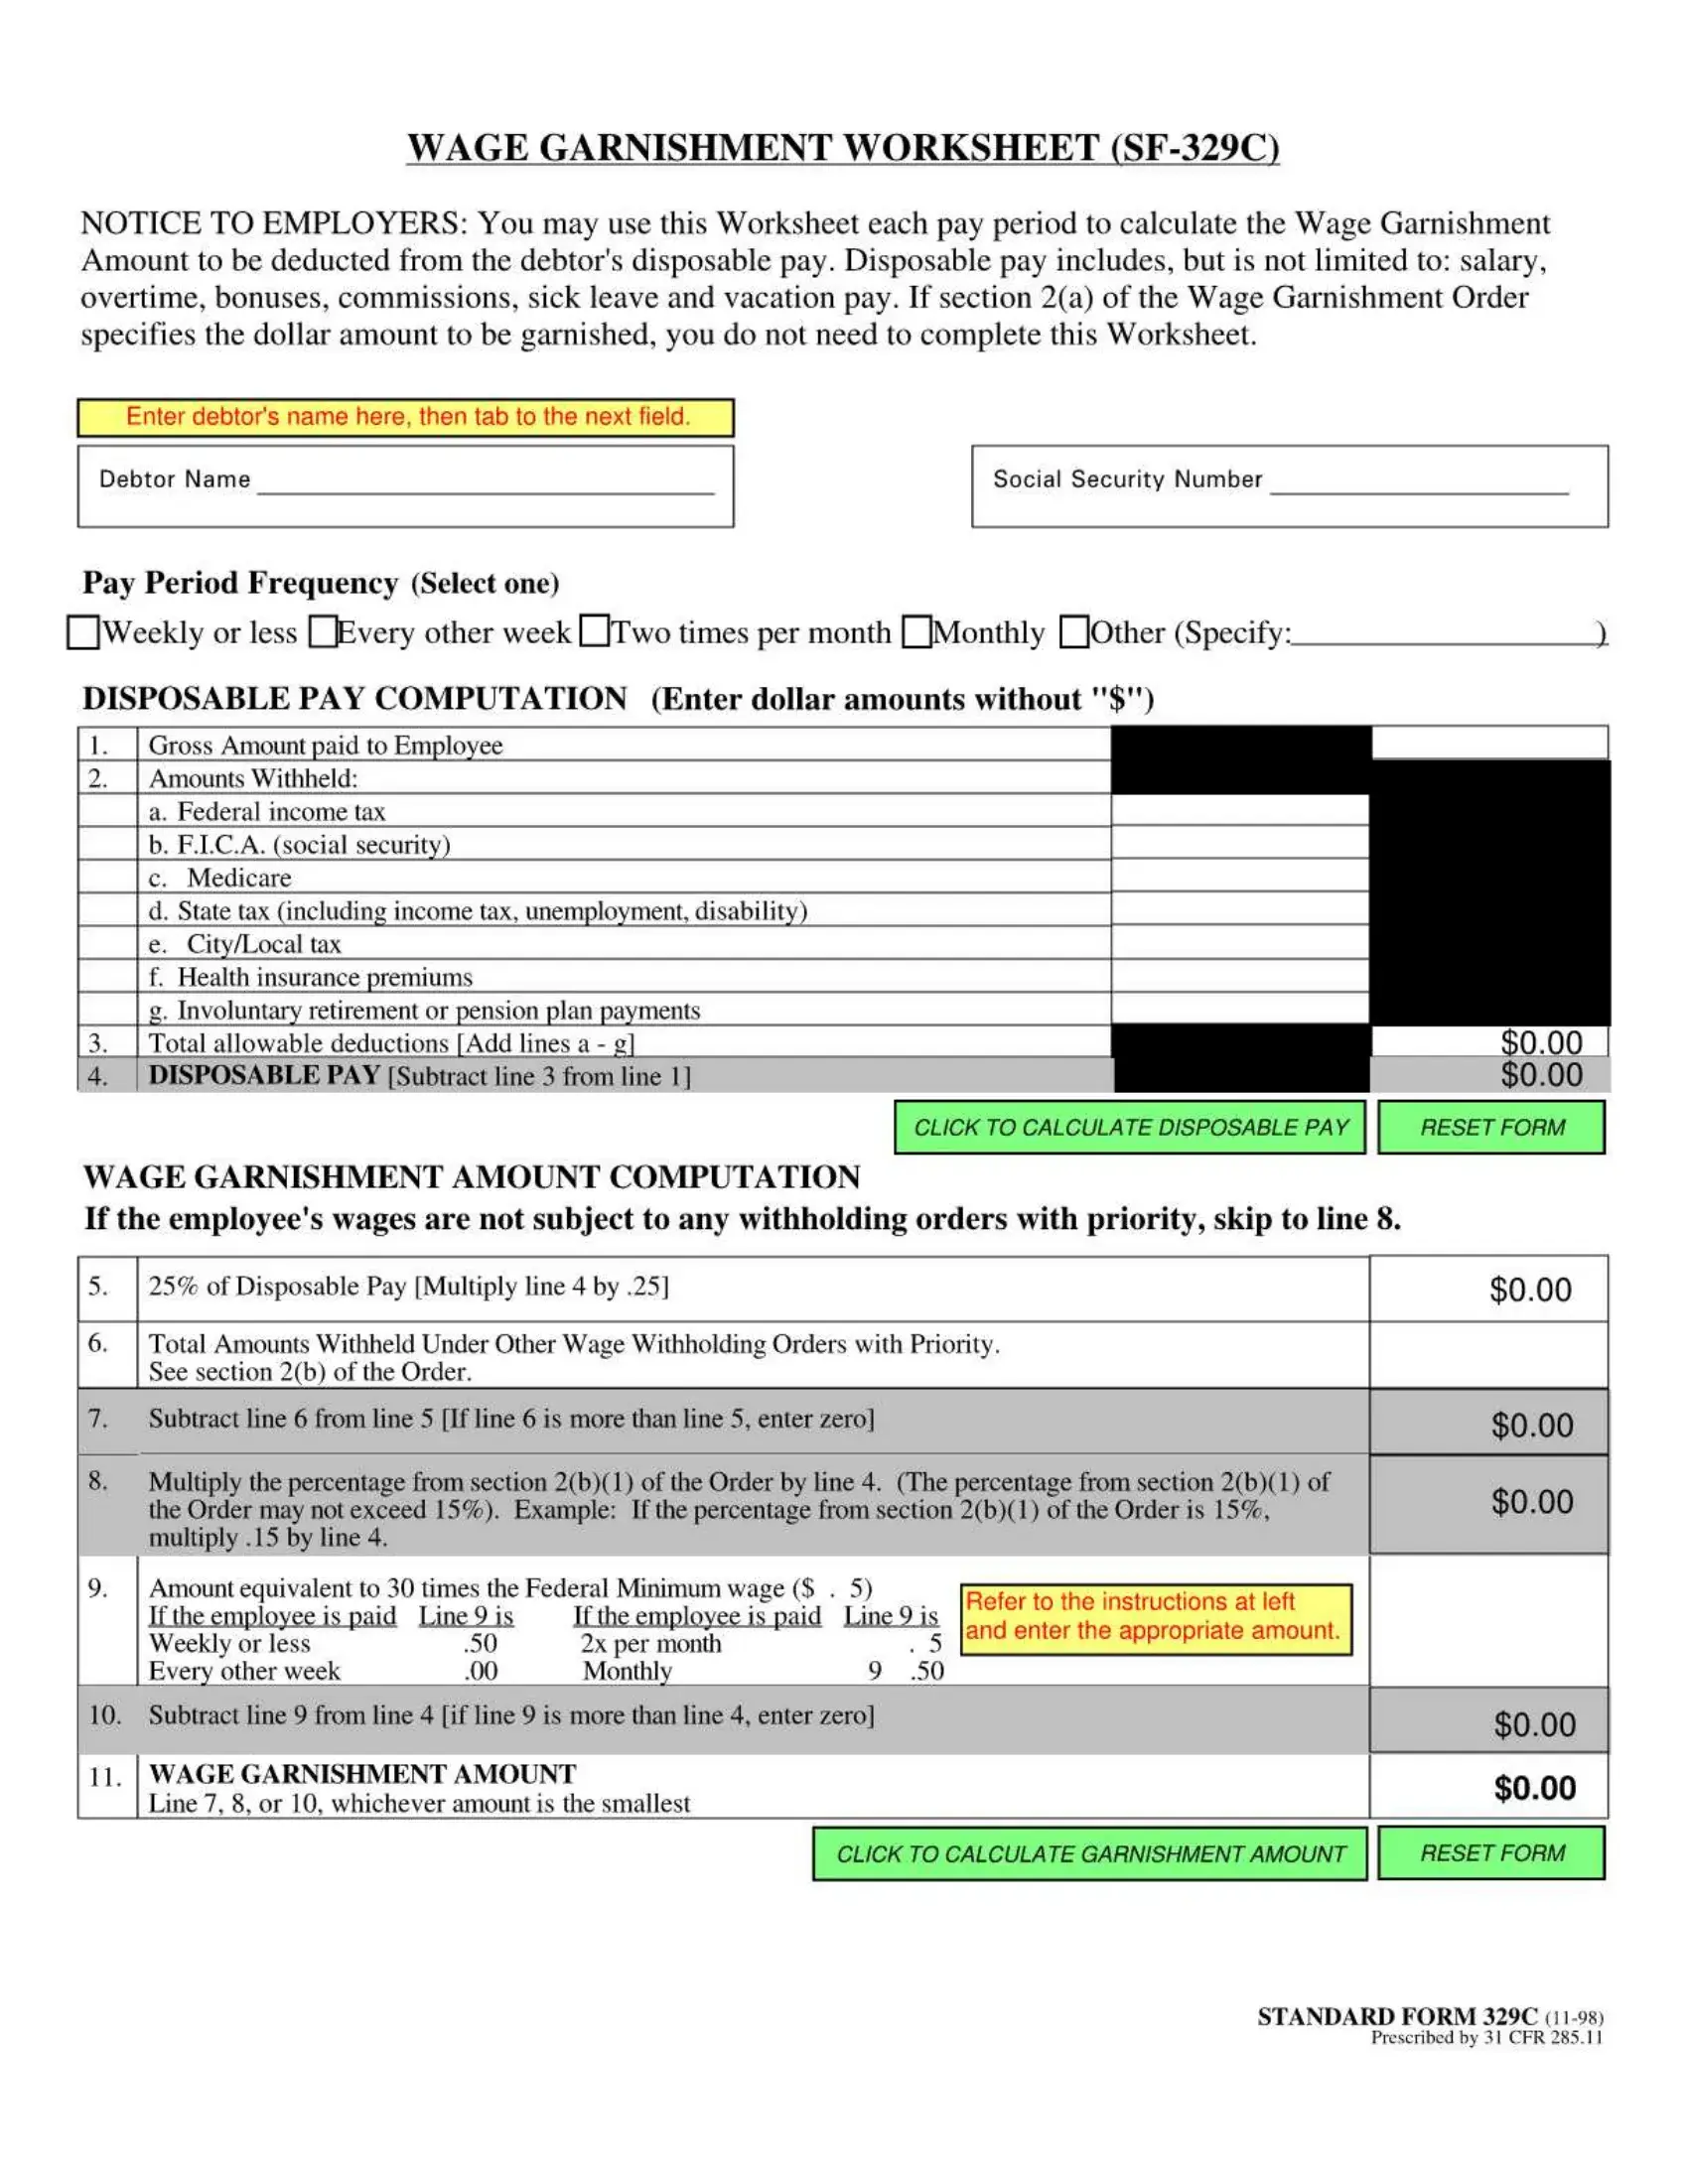
The Illinois Wage Garnishment Worksheet is the form employers and payroll processors use to figure out how much of an employee's disposable earnings can legally be withheld to satisfy a court-ordered garnishment. It sounds straightforward, but the interaction between federal limits, Illinois-specific protections, and multiple concurrent orders creates enough edge cases that most people get it wrong on the first try. I spent eight years running payroll for a mid-size company and processed probably two thousand of these. The ones that cause problems are never the simple ones. You start with the employee's gross pay for the current pay period. From that, you subtract all court-mandated deductions first: federal and state taxes, Social Security, Medicare. Then you subtract permitted voluntary deductions like health insurance premiums and 401(k) contributions if the plan documents allow garnishment offsets. What remains is disposable earnings. That number is your starting point for the worksheet calculations. Under federal law, which Illinois follows for most consumer debts, the maximum garnishment is the lesser of 25% of disposable earnings or the amount by which disposable earnings exceed thirty times the federal minimum wage. Right now at $7.25 per hour, that threshold works out to $217.50 per week. So if someone makes $500 a week in disposable earnings, 25% is $125, but their excess over $217.50 is $282.50, meaning the garnishment would be capped at $125. If they make $300 a week, 25% is $75 but the excess is only $82.50, so the garnishment is $82.50. The worksheet tracks both numbers and takes the smaller one each pay period.
Illinois has its own overlay on top of the federal baseline. Under the Illinois Wage Garnishment Law (820 ILCS 117/1 et seq.), certain types of debts get different treatment. Child support and alimony obligations fall under Title IV-D of the Social Security Act, which allows up to 50% of disposable earnings if the employee is supporting a second family, or 60% if they are not. Those percentages apply to the excess over the federal minimum wage threshold, not the full disposable earnings figure. A tax levy from the IRS or Illinois Department of Revenue follows different rules entirely and isn't bound by the same consumer garnishment caps. Here is where I ran into the problem that almost no one anticipates. We had an employee with two concurrent garnishments: a child support order from one jurisdiction and a creditor judgment from another. The creditor order came in first and was calculated at 25% of disposable earnings. Two months later, the child support enforcement agency served us with a new order. The problem is that both orders were claiming against the same disposable earnings pool, and the total could not exceed the federal or state maximum for that income level. I had to recalculate the original creditor's attachment downward to make room for the child support order, which was entitled to priority under both federal and Illinois law. The worksheet doesn't have a field for multiple orders. I built a separate tracking log that listed each order's priority date, the percentage it claimed, and the running total of withheld amounts per pay period. Without that log, I would have over-withheld by roughly $40 per paycheck and exposed the company to potential liability from the creditor. Another detail that trips people up involves the definition of a "pay period." The worksheet calculations change depending on whether the employee is paid weekly, biweekly, semimonthly, or monthly. The thirty-times-minimum-wage threshold is computed per pay period, not per year. For a semimonthly paid employee, the threshold is 30 × $7.25 × (26/12), which comes to approximately $467.42 per pay period. Some payroll systems mistakenly annualize the threshold and divide it by the number of periods, which produces the same number mathematically but introduces rounding errors across pay cycles. Over a year, those rounding errors can add up to enough discrepancy that an audit reveals the garnishment was slightly under-collected or over-collected.
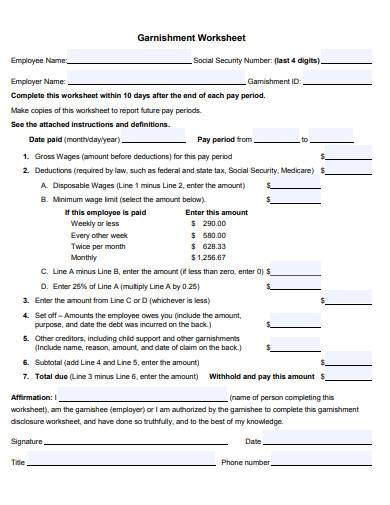
The Illinois Wage Garnishment Worksheet itself is not a single mandatory form published by the state. Different courts may provide their own versions, and many attorneys and process servers use worksheets adapted from the federal forms provided by the Department of Labor. The substance is what matters: you need to compute disposable earnings, apply the correct percentage cap based on the type of debt and the employee's family situation, account for any prior orders, and document everything. When a creditor's attorney sends you a garnishment order for an Illinois-based employer, they typically include a completed worksheet or at least a computation showing their calculated withholdable amount. You should verify their math independently rather than accepting it at face value. I have seen several cases where the serving attorney miscalculated disposable earnings by including pre-tax retirement contributions that should have been deducted first, inflating the garnishment amount by $60 to $90 per pay period. If you are an employee trying to understand what is being taken from your check, request a copy of the original court order and the most recent wage statement showing the garnishment line item. Compare the withheld amount against your disposable earnings using the 25% and excess-over-threshold tests I described. If the numbers do not reconcile, you have grounds to file a claim of exemption or object to the garnishment in the court that issued the order. The Illinois courts accept pro se filings for garnishment disputes, though the process moves slowly. Most employees resolve incorrect garnishments by contacting the creditor's attorney directly and pointing out the computation error, which usually results in a corrected withholding order within one or two pay cycles. There are situations where the worksheet approach breaks down completely. If the employee works for multiple employers simultaneously, each employer only sees the wages it pays and has no way to know about garnishments being served on other employers. The aggregate income might push the employee above the threshold that would protect part of their earnings from a single-employer perspective, but each employer independently calculates without knowledge of the other income stream. This is a genuine gap in the system. The employee bears the burden of informing each employer about existing garnishments, which most do not do.
Get the Full Details

For employers who need a reliable tool, I recommend building a spreadsheet model that automates the disposable earnings calculation, applies the correct percentage based on order type, tracks multiple concurrent orders with priority dates, and flags when the total withheld approaches the legal maximum. Hand-computing these worksheets for more than a handful of garnished employees per quarter introduces unnecessary error risk. The time investment to build the model pays for itself after the third or fourth garnishment order you process. The core takeaway is that the Illinois Wage Garnishment Worksheet is not just a calculation exercise. It is a compliance document that sits at the intersection of federal law, state statute, and individual court orders. Getting it right requires understanding the hierarchy of claims, computing disposable earnings correctly, and maintaining accurate records. Getting it wrong can result in legal exposure for the employer and financial harm for the employee. Treat it with the attention it deserves.