Working Through the Illinois Withholding Allowance Worksheet
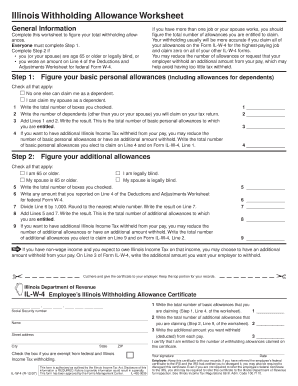
The Illinois withholding allowance worksheet is Part 2 of the IL-W-4V employee worksheet, and it determines how many allowances you claim for state income tax purposes. Most people skip right past it because federal W-4s don't have an equivalent, but Illinois calculates its tax differently. You need to understand what each section does before you fill it out, otherwise you'll end up with an underwithheld refund bill or money too aggressively taken from every paycheck. Illinois uses a flat tax rate now — currently 4.95% — but it still relies on an allowance system modeled after the old federal method. Each allowance reduces your taxable wages by a set dollar amount before the flat rate is applied. For 2024, one withholding allowance equals roughly $4,050 of annual income, matching the federal personal exemption amount that Illinois still references. I learned the hard way that this number matters more than most employees realize. I had a contractor in 2022 who claimed zero allowances on his IL-W-4 and asked to see his projections. He was making about $82,000 a year. With zero allowances, the flat rate hit his full salary, pulling roughly $4,059 in annual state tax. If he had claimed just two allowances, his taxable income would drop by about $8,100, saving him roughly $400 a year. That's not a lot to most people, but it came out of every paycheck throughout the year instead of as a lump-sum refund in April. The cash flow difference was real for someone living check to check.
How the Worksheet Actually Works in Practice
The worksheet has four parts, and they build on each other. Part A asks whether you have more than one job or are married filing jointly with a spouse who also works. This is where people make mistakes. If you and your spouse both earn over $30,000 each, the standard approach of having each employee claim allowances individually on their own W-4 doesn't work well. The Illinois Department of Revenue explicitly says you should use the Combined Income Worksheet instead, which is a separate document attached to the same form packet. Part B covers your standard deduction. Illinois allows you to claim the standard deduction on your withholding rather than itemizing, and the default assumption is that you will. The worksheet calculates this by taking the standard deduction amount for your filing status and dividing it by the allowance value. So if you're single and the standard deduction is $12,550, you'd divide that by $4,050 and get about 3.1, which you round to 3 allowances for this line. Part C is where the actual nuance lives. You list any additional deductions you expect to claim — mortgage interest, charitable contributions, retirement plan contributions — and these get converted into extra allowances. One thing nobody warns you about: if you're contributing to a 401(k) or similar employer retirement plan, those contributions reduce your Illinois taxable income dollar for dollar. A $6,000 401(k) deferral is essentially another 1.5 allowances right there. I've seen employees completely miss this step because they assumed the retirement contribution was already handled by their federal withholding election.
Part D is the total line. You add up Parts A through C and round down to the nearest whole number. That number goes on line 4 of your IL-W-4. It becomes your official withholding allowance count for the year.
Get the Full Details

Common Pitfalls and Edge Cases
The biggest issue I see is people treating the allowance count as static. Life changes mid-year — you get married, buy a house, have a child, start paying student loan interest. The worksheet is designed to be completed fresh whenever a qualifying life event happens. If you don't update it, your withholding stays at the old level. There's no automatic adjustment mechanism in Illinois like there is with some employer payroll systems for federal taxes. Another problem: the worksheet assumes you'll file either single or married filing jointly. If you're married but filing separately, the standard deduction shrinks to zero for withholding purposes in Illinois, which means you lose those allowances in Part B entirely. I ran into a situation where a client was filing separately due to a complicated divorce arrangement and his withholding spiked by nearly $800 annually because nobody recalculated the worksheet after the filing status change. His paystub didn't reflect the new amount until the next quarter when we audited his filings together. There's also the issue of side income. The worksheet only accounts for wage and salary income from your W-2 employers. If you have freelance work, rental income, or investment gains, those aren't factored in at all. The allowance system will underwithhold in that scenario unless you voluntarily add extra withholding on line 6 of the IL-W-4. I recommend anyone with significant non-wage income complete the Additional Withholding Worksheet instead, which gives you a dollar amount to request per paycheck rather than playing with allowances.
When the Worksheet Fails You
The allowance system itself has real limitations. It was designed for a world with bracketed tax rates and phase-outs, not a flat-rate structure. Once Illinois moved to 4.95% across the board in 2017, the whole concept of allowances became somewhat theoretical. You're still using the framework, but the math behind it doesn't align as cleanly with how your actual tax liability works. The allowance system overcorrects for middle-income earners and undercorrects for high earners who benefit from the lack of brackets. If your annual Illinois taxable income exceeds about $150,000, the allowance method tends to underwithhold. I'd recommend switching to the Percentage Method or the Additional Withholding option instead. The Percentage Method lets you calculate withholding based directly on your wage bracket tables rather than trying to approximate your tax through allowance counts. It's more accurate for higher incomes and takes about the same amount of time to complete once you understand the tables. There's also the question of residency. If you work in Illinois but live in a different state, or vice versa, the worksheet doesn't apply the same way. Many employees in that situation end up double-withheld or underwithheld because they fill out the Illinois form assuming it covers their full liability. If you're a nonresident working in Illinois, you generally only owe Illinois tax on income earned within the state, and your home state may have a credit for taxes paid to Illinois. In those cases, claiming zero allowances on the Illinois form and handling everything through your resident state is often simpler and more accurate.
Where to Get the Form
The current IL-W-4 and the accompanying withholding allowance worksheet are available directly from the Illinois Department of Revenue website. You can download and print them, or complete them electronically if your employer participates in the e-FW4 program. Make sure you're using the latest version — the 2024 revision — because prior years had slightly different rounding instructions and the allowance value changed when the inflation adjustments were applied. When you finish the worksheet, sign and date the form before submitting it to your employer. An unsigned IL-W-4 defaults to single with zero allowances, which means maximum withholding. If you're unsure about anything on the form, the Illinois Department of Revenue publishes a separate instruction booklet that walks through each line with examples for common filing situations.