Understanding Settlements Under the Illinois Workers Compensation Act
The Illinois workers compensation system operates differently than most people expect. When a claimant and an insurer agree on a resolution, it goes through arbitration rather than a judge in a courtroom. The arbitrator reviews the settlement, but they're not rubber-stamping everything you send their way. I've seen deals rejected because the medical documentation didn't clearly support the permanence allegations, or because the calculation formula for temporary total disability payments had rounding errors that threw the whole award off. Let me walk you through how this actually works in practice, starting with what most attorneys get wrong on day one.
Illinois Workers Compensation Settlement Guide
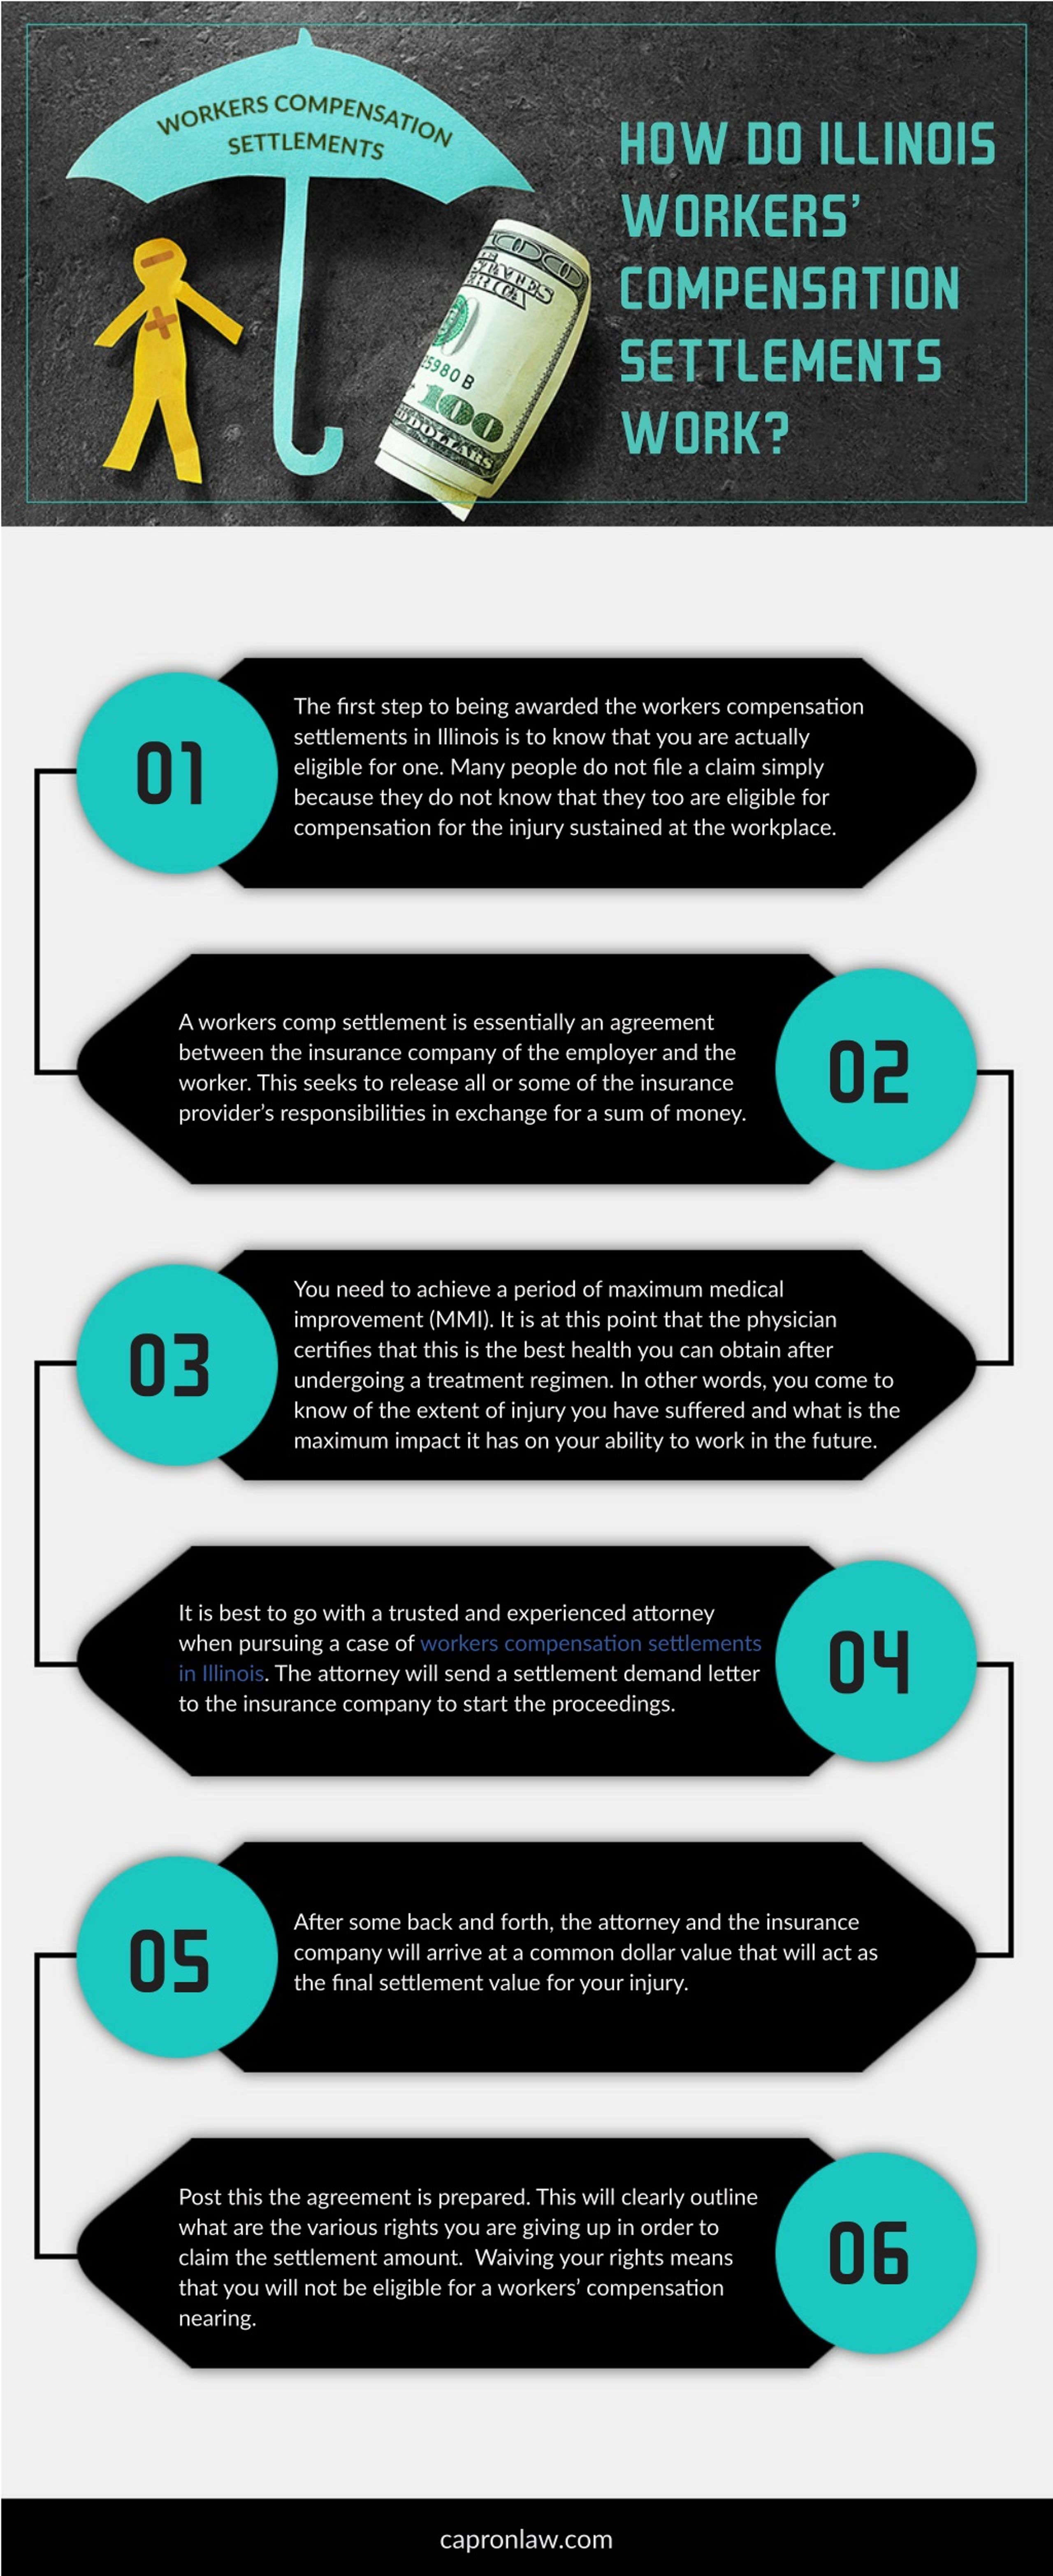
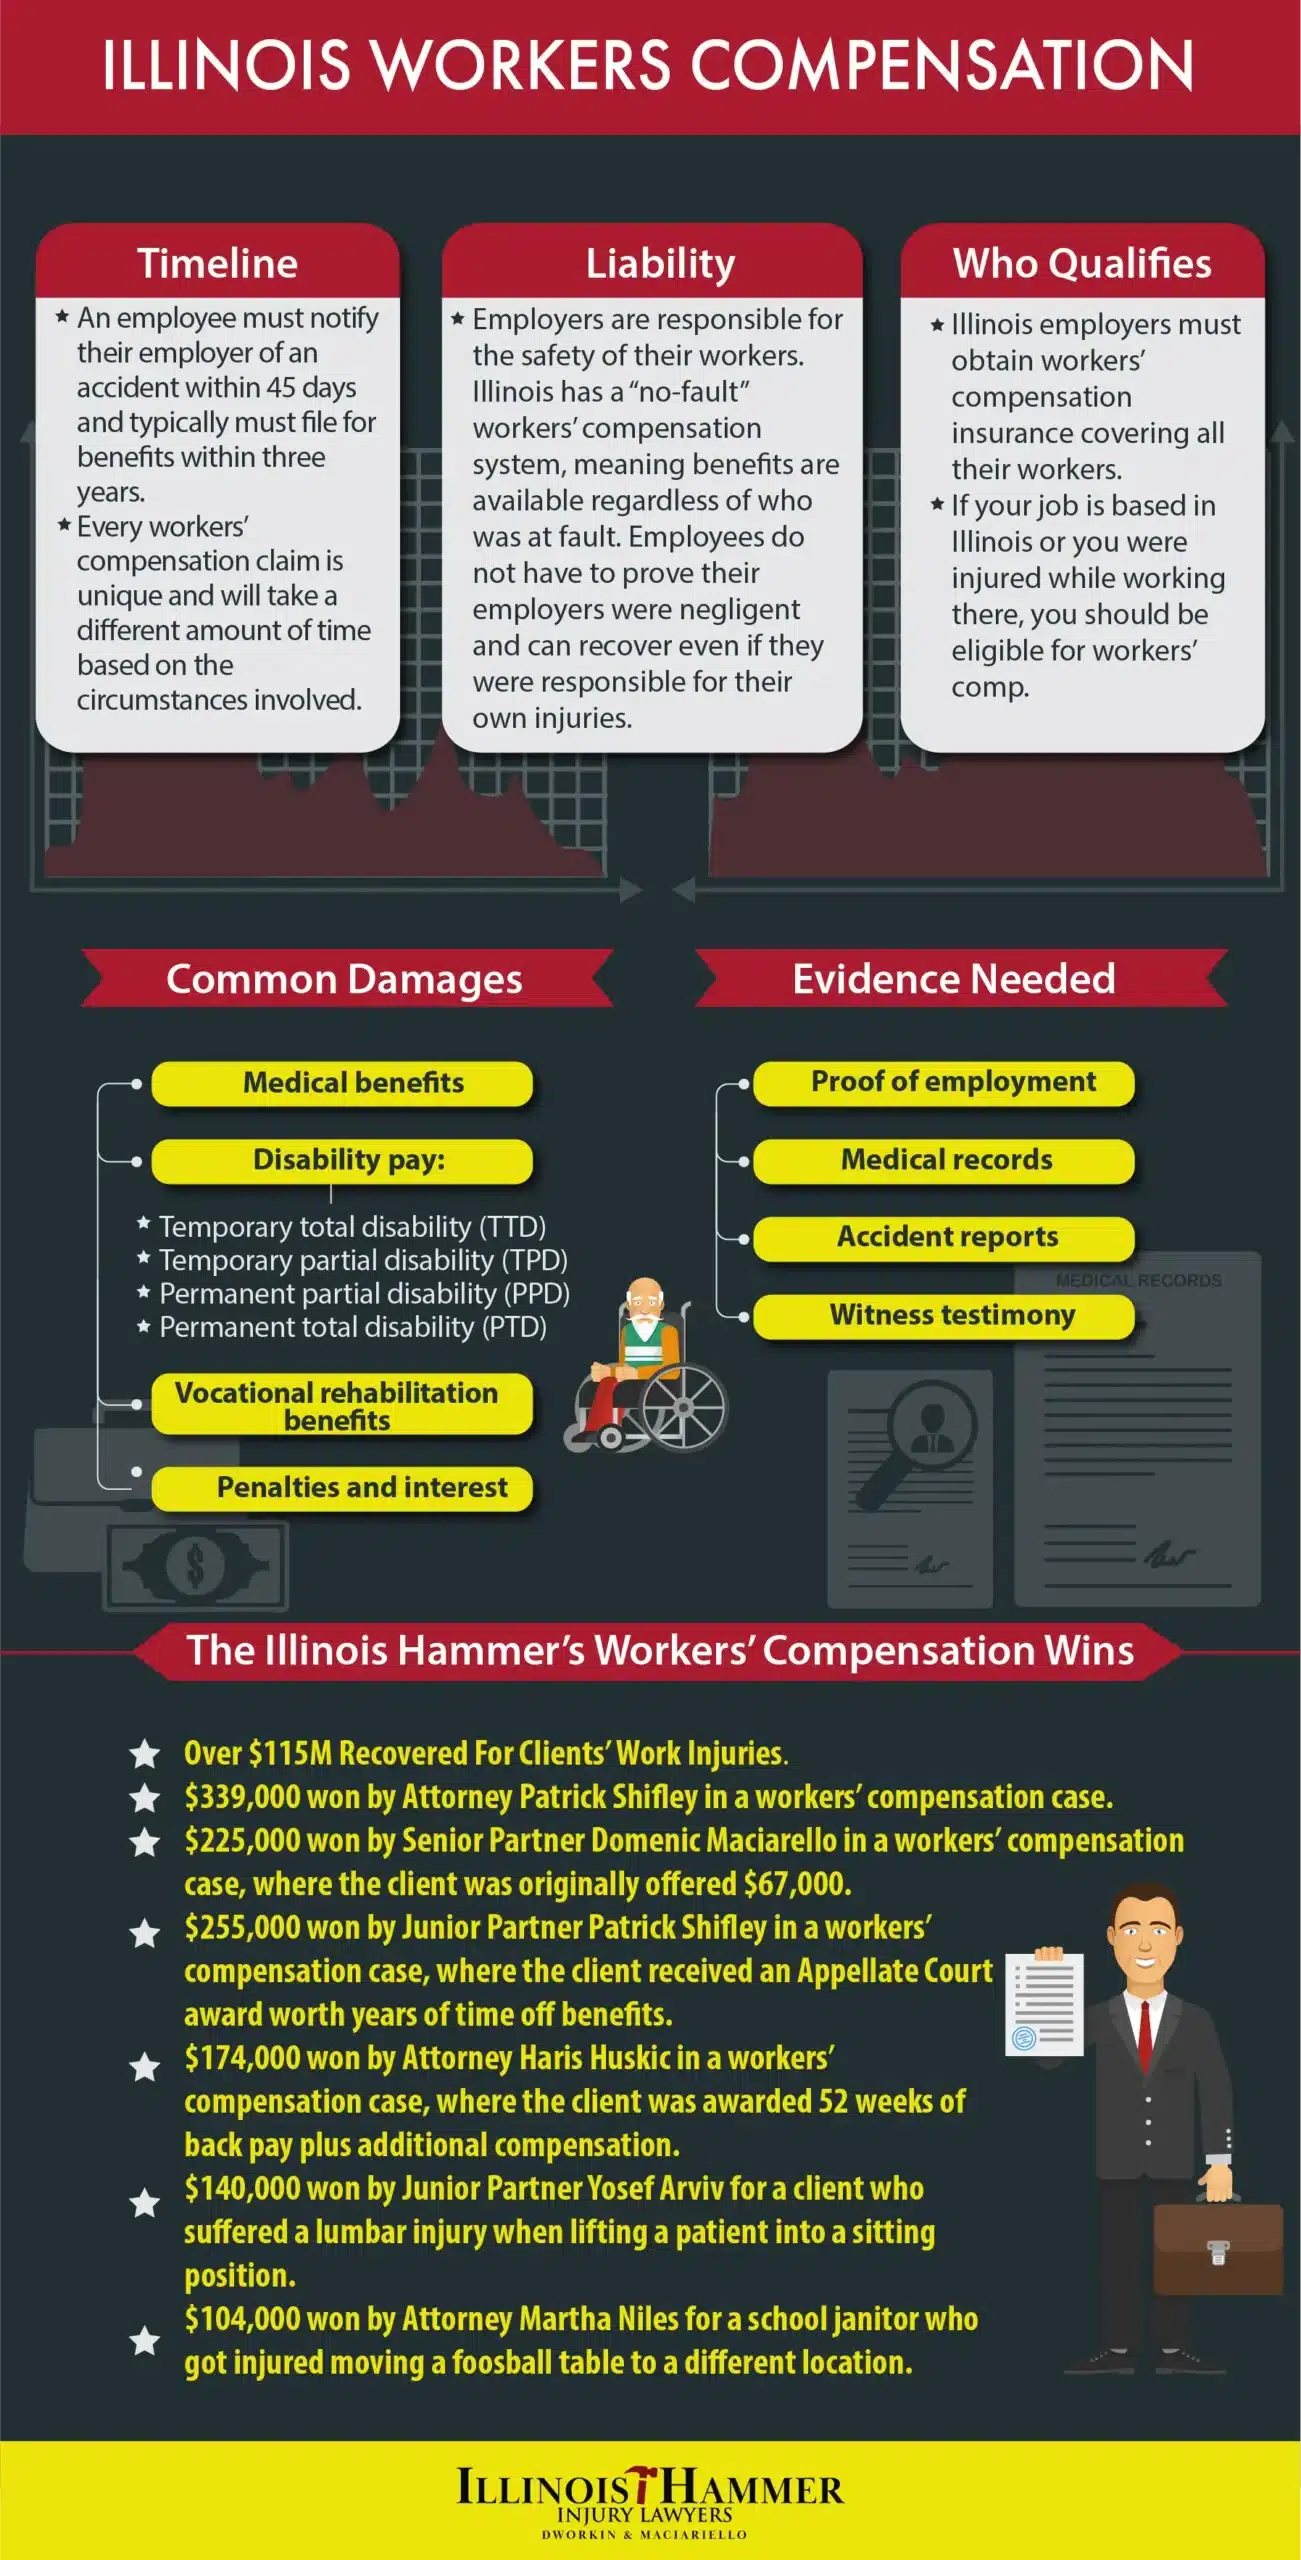
You can download a working PDF version of this guide here. It includes the arbitration submission checklist, the standard settlement agreement template, and the calculation worksheets for the three main types of settlements under the Act. The core framework you need to understand is that Illinois uses a schedule-based system for permanent partial disabilities. Section 4-2 of the Act lists specific body parts and the number of weeks of compensation assigned to each injury type. A lost finger might be 16 weeks. Total permanent loss of use of an arm is 160 weeks. But the real world rarely maps neatly onto these schedules, which is where things get complicated. There are three primary settlement mechanisms available to you. First, there's a full settlement agreement under Section 6 of the Act. This releases all claims, known and unknown, and requires mutual agreement on every category of benefit. Second, you have the impairment settlement agreement, which caps the claim at a specific dollar amount related to permanent impairment but leaves other issues like future medical care potentially open depending on how you draft it. Third, there's the stipulated findings and award, which is essentially a binding arbitration order that comes from negotiated terms but carries the force of a formal decision.
Here's the part nobody tells you upfront: insurance adjusters in Illinois know that claimants often prefer certainty over maximum possible value. This asymmetry matters. A fully executed settlement agreement locks in your numbers now, which protects the insurer from future open medical liability. That gives them leverage to offer less than the case might be worth if you were to litigate through to a hearing on the record. You need to know the difference between what the statute entitles you to and what the current market dynamics will actually pay, because those two numbers are rarely identical. I worked a case a few years back involving a warehouse worker who suffered a lumbar strain. The treating physician rated it at 15% permanent partial impairment to the back. Under the Illinois schedule, that calculation gets messy because back injuries don't have a fixed week value the way limb losses do. The statute treats them under the general disability provisions, which means the award depends on wage loss, age, and occupation. The adjuster offered a flat $28,000 based on a rough formula. I ran the numbers properly using the employee's pre-injury weekly wage of $892, his age at injury of 47, and the projected five-year wage differential post-injury, and the math came out closer to $47,000. The adjuster didn't budge until I sent a formal arbitration filing with the supporting wage documentation. Then the number changed. The arbitration process itself has requirements that trip people up. You need to file the settlement agreement with the Illinois Workers Compensation Commission along with a proposed order. The arbitrator must approve it before it becomes enforceable. There's no automatic processing. If you submit a draft that doesn't comply with the Act's wording requirements, the arbitrator will return it with notes, and you're looking at delays that cost everyone time and sometimes money.
Get the Full Details
One specific compliance issue I see constantly: the settlement agreement must contain a clear statement about whether future medical treatment is being reserved or settled. If the language is ambiguous, the Commission may refuse to approve it, or worse, approve it in a way that creates a dispute down the line about whether a future surgery is covered. I've seen this happen where the phrase "all present and future medical expenses" was used without specifying whether it capped the obligation or left it uncapped. The resulting litigation took two years to resolve. When calculating the actual settlement figure, start with the temporary total disability payments already made. Those are typically two-thirds of the pre-injury wage, subject to the state average weekly wage caps that change annually. For 2024, the maximum weekly compensation rate under the Act is $1,033.60. Multiply that by the number of weeks the employee was off work, then add the permanent partial impairment component. For scheduled injuries, you multiply the statutory weeks by two-thirds of the weekly rate. For non-scheduled injuries like back injuries, you use the impairment rating multiplied against the remaining useful earning capacity, adjusted for age and occupation. The vocational rehabilitation aspect is another area where claimants walk away with less than they should. Under Section 8 of the Act, if an employer fails to provide suitable reinstatement or vocational services when required, the compensation period can be extended. I encountered a situation where an adjuster tried to include a broad release of all Section 8 claims in a standard settlement agreement without specifically itemizing the vocational rehabilitation exposure. The worker had been out of his occupation for eight months and had no retraining offer from the employer. That Section 8 exposure alone was worth an additional $12,000 to $18,000 in the settlement, depending on how long the extended compensation period would run.
Here's a practical workflow I recommend for anyone preparing a settlement. First, gather the complete medical file including all imaging reports and physician statements with impairment ratings. Second, pull the wage history from the employer covering the 52 weeks preceding the injury. Third, calculate the temporary total disability amount with exact dates, noting any periods of partial disability. Fourth, determine the permanent impairment value using the appropriate schedule section. Fifth, assess any open medical needs and Section 8 exposure separately. Sixth, draft the agreement with explicit language on each category. Seventh, submit to arbitration with a cover letter summarizing the key terms and highlighting compliance with all statutory requirements. There are scenarios where a settlement is genuinely not the right move. If the injury is still evolving and the treating physician hasn't reached maximum medical improvement, locking in a settlement now means you could be trading future medical care for a fixed sum that doesn't account for a worsening condition. I had a construction worker with a knee injury settle for $35,000 on the strength of a 10% impairment rating. Six months later he needed arthroscopic surgery that the insurer refused to cover because the settlement agreement contained a blanket release of all medical obligations. He came back to me six months later with a much more complicated case and significantly fewer options. Another edge case worth noting involves independent medical examinations. Insurance carriers frequently request IMEs before agreeing to a settlement figure. The problem is that different evaluators can assign significantly different impairment ratings for the same injury. A spine specialist might rate a lumbar condition at 12% WPI while a different evaluator rates it at 18% WPI. That 6% difference on a $900 weekly wage translates to roughly $7,000 to $9,000 in settlement value. I usually advise clients to wait for the treating physician's final rating before entering settlement discussions, or to negotiate based on a range rather than a single number.
The Arbitration Review Process
Once you file the settlement with the Commission, the arbitrator reviews it for compliance. This isn't a negotiation round. The arbitrator checks whether the agreement meets the statutory requirements, whether the consideration is adequate, and whether the language is clear enough to be enforced. Most settlements get approved within 30 to 45 days if they're drafted correctly the first time. If the arbitrator identifies issues, they'll send back a recommendation for modification, and you'll need to submit an amended agreement. The approval order itself is what makes the settlement binding. Without it, you're just sitting on a piece of paper that neither party can reliably enforce. The order converts the private agreement into a Commission decision, which means it has the same enforceability as any other award issued through the workers compensation system. That includes the ability to seek collection through the Commission's enforcement mechanisms if payment doesn't come through. Payment timing is another practical concern. The statute requires payment within a specific window after the arbitration approval order is entered. For lump sum settlements, the adjuster typically has 14 days to issue the payment. Miss that deadline and you may be entitled to additional penalties, though pursuing those penalties usually requires a separate enforcement filing. I keep track of these deadlines in a spreadsheet for every active case, because the administrative burden of chasing a late payment is disproportionate to the effort it takes to monitor it proactively.
Common Mistakes That Cost Claimants Money
The biggest mistake I see is accepting the first offer without understanding the full scope of what's being traded away. Settlement agreements are contracts, and the release language determines exactly which claims you're giving up. Vague releases that don't explicitly address future medical care, Section 8 violations, or known but unfiled injuries create ambiguity that benefits whoever drafts the document, which is almost always the insurer's side. Another frequent error is miscalculating the tax implications. Workers compensation settlements are generally not taxable income under federal law, but that protection only applies if the settlement is properly structured. If the agreement lumps in damages for pain and suffering or emotional distress without clear allocation, the IRS could treat portions of the payment as taxable. I've seen cases where the entire settlement got flagged for tax reporting because the drafting attorney didn't separate the workers compensation components from any ancillary damages. Get this wrong and your net recovery shrinks significantly. The third common mistake involves ignoring the election of remedies. In Illinois, if you accept a settlement that includes indemnity benefits, you may be forfeiting your right to pursue certain other claims, including potential third-party liability actions if the injury was caused by someone other than your employer. I worked with a truck driver who was hit by a negligent motorist while making a delivery. His workers compensation case was straightforward, but he settled his workers comp claim without reserving his third-party rights. That third-party claim could have yielded an additional $150,000 or more in a civil suit. Settling the workers comp case first without addressing the third-party exposure is one of those regrets that doesn't go away easily.
If you're navigating this on your own without legal representation, the Commission provides self-help resources and the settlement templates are available through their website. The process is designed to be accessible, but the stakes are high enough that having someone who understands the nuances of the statute and the local arbitration culture makes a substantial difference in the outcome. The guide I referenced at the beginning of this article covers the standard forms and includes annotated examples showing both correct and problematic drafting approaches, so you can see what good compliance looks like in practice.