What an Income Verification Letter Actually Is
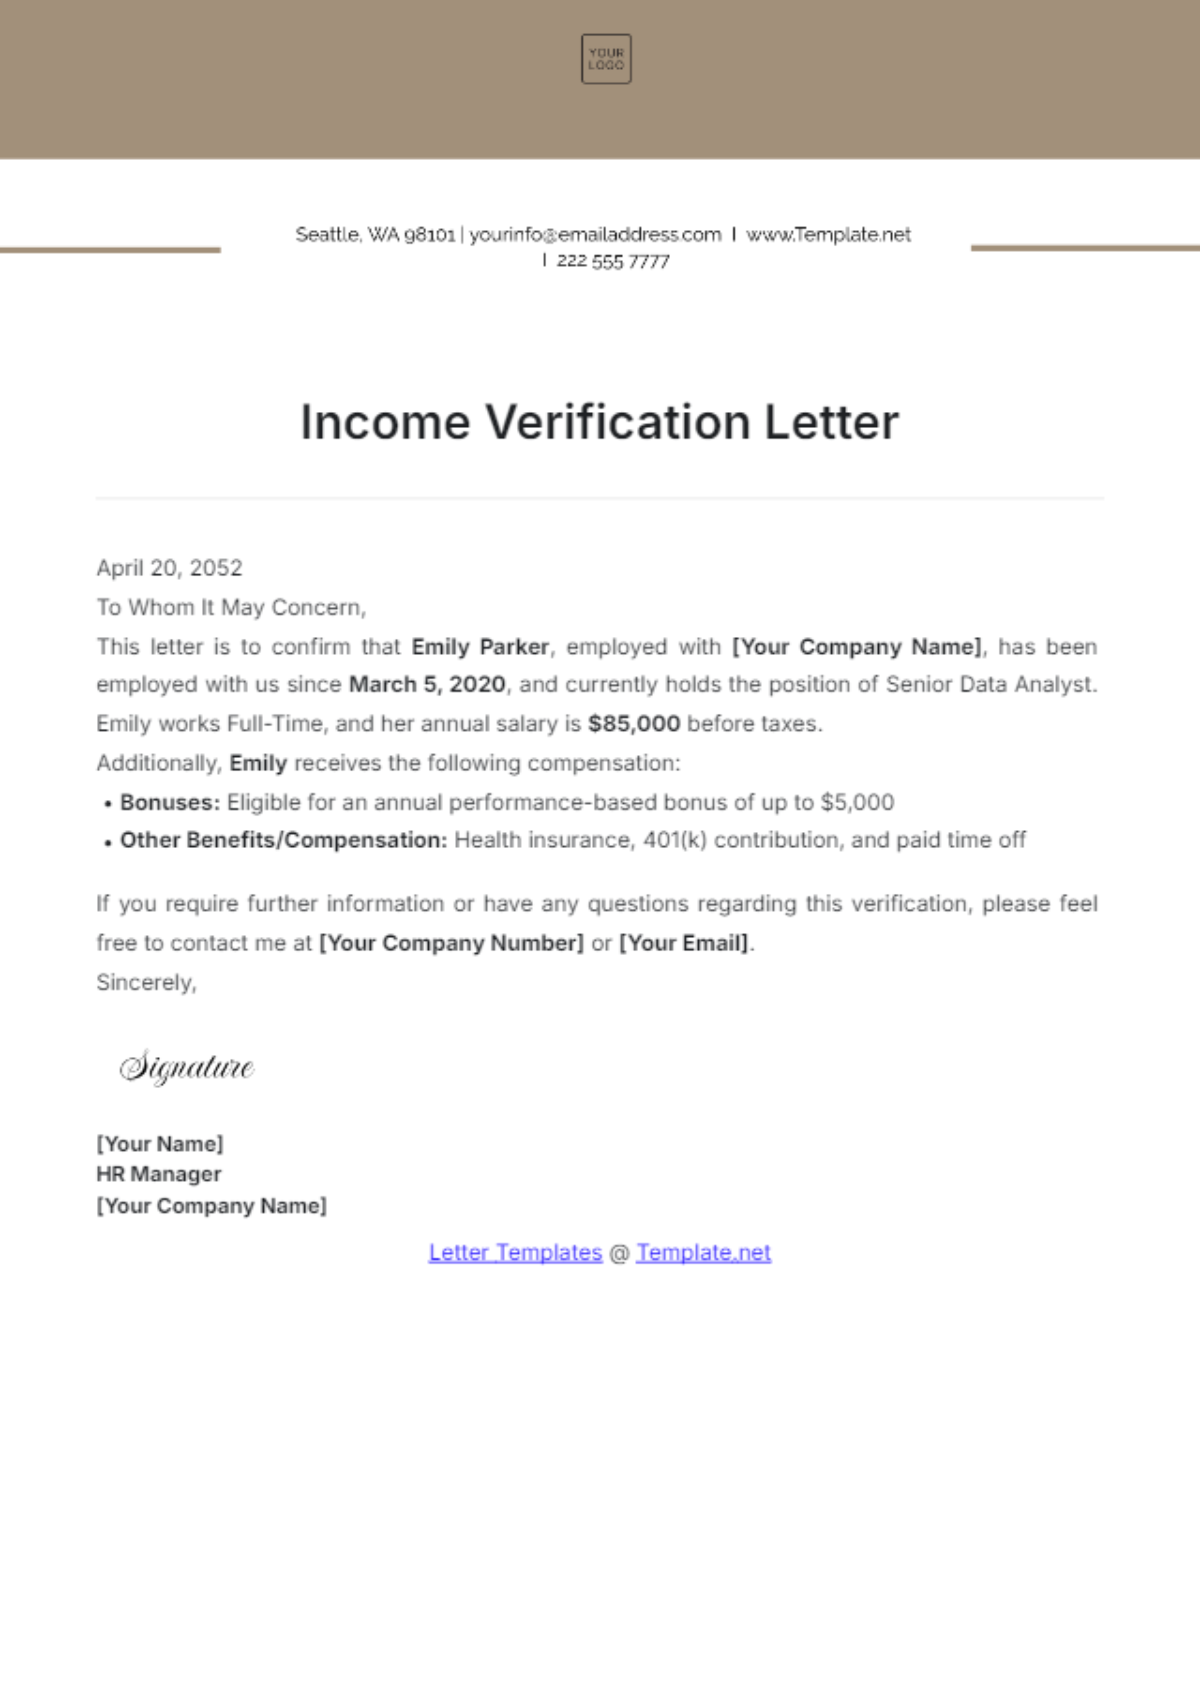
It is a document issued by an employer, payroll provider, or financial institution confirming that someone earns a specific amount of money over a set period. That is it. Nothing dramatic about it. Landlords use them. Mortgage lenders require them. Some visa applications need them too. The letter typically states the employee name, job title, hire date, annual or monthly income, and sometimes employment status. It is usually signed by a manager or HR representative and printed on company letterhead. Most people think they just need to ask their employer and walk away with a clean PDF. In practice it is often messier than that. I learned this the hard way when a borrower had 18 months of documented income from a gig platform. The Income Verification Letter from the platform only showed aggregated quarterly totals, not year-by-year breakdowns. The underwriter rejected it outright because the lender's policy required month-by-month verification tied to W-2 equivalents. We ended up pulling direct bank statements showing every deposit for 18 months, then cross-referenced them against the quarterly payout reports and manually built a timeline that satisfied the underwriter. That took three days and two frustrated phone calls with the platform's support desk.
How to Obtain an Income Verification Letter
Start by identifying exactly who needs to sign it. For salaried employees this is usually HR or a direct manager. For hourly workers the same rule applies but some companies route it through a third-party payroll processor like ADP or Gusto. If you are self-employed there is no employer to ask, which changes the entire process. You are looking at CPA-verified tax returns or bank statements instead. Request the letter in writing. Email is fine, but keep a record. Include your full legal name, Social Security number or tax ID, your employment dates, and the specific income figure you need verified. Lenders and landlords sometimes reject letters that omit your SSN because they cannot match it to your application. Also specify whether they need annual or monthly income. A letter that states "salary not yet determined" is worthless to anyone reviewing a loan file. Turnaround time varies. Most employers produce one within 3 to 5 business days. Some small businesses take two weeks because the person who signs these letters also handles receivables and benefits enrollment. If you are on a deadline, call the office after submitting the request. A polite follow-up usually cuts the clock by a few days.
Common Formats and What Underwriters Actually Look For
There are roughly three formats you will encounter. The first is a company-issued letter on letterhead. The second is a payroll stub export from an automated system. The third is a verification of employment form completed by HR and faxed or uploaded directly to the lender. Only the first two are commonly accepted as standalone proof. The third is usually tied to a specific lender's portal and is not portable. Underwriters scan for five things in order: letterhead authenticity, matching name and ID, income consistency, date validity, and authorized signature. If any one of those is off the file goes to secondary review. I have seen letters rejected because the email address on the letterhead belonged to the company's marketing department rather than HR. It sounds ridiculous. It happens. Another time a perfectly valid letter was returned because the printed date was on a weekend and the receiving office treated it as potentially backdated. They asked for a reissue with a business-day date. Just something to keep in mind.
Get the Full Details

Income Verification Letter for Self-Employed Individuals
This is where most people run into trouble. There is no employer to generate the letter. A self-employed person cannot produce one from thin air. Instead, you compile an income verification package that functions the same way. It typically includes the last two years of tax returns with all schedules, year-to-date profit and loss statements if available, and 12 to 24 months of business bank statements. Some lenders will accept a CPA letter in place of a formal Income Verification Letter, but not all of them do. Check the lender's guidelines before you spend hours assembling documents. A practical edge-case I ran into involved a contractor who worked as an independent subcontractor for a large firm. He had a steady stream of payments but no W-2. The subcontracting company agreed to issue an Income Verification Letter on their letterhead confirming his average monthly earnings. The lender initially accepted it, then six weeks later during underwriting they flagged that the letter came from a company that was not his legal employer. The letter was treated as insufficient because the payor entity and the contracting entity were different. We resolved it by attaching the subcontract agreement and a separate confirmation from the firm's accounting department stating that payments were processed directly to him. It added a week to the timeline but saved the file from being declined.
Pitfalls That Will Slow You Down
Income figures in letters do not always match what appears on pay stubs. Some employers list gross income. Others list net. A few list base salary and exclude bonuses or overtime entirely. If the letter omits variable compensation that makes up a meaningful portion of your income, the underwriter may adjust your qualifying income downward. This is one of the most common sources of surprise. Ask your employer upfront whether the letter includes all forms of compensation or just base pay. Another issue is expiration. An Income Verification Letter is rarely considered valid past 30 to 60 days by most lenders. If your file is slow-moving, the letter can expire before closing. I have watched files stall because a borrower requested the letter two months before applying and then spent another six weeks waiting on appraisal and title work. The letter expired during that window and had to be reissued. Request it no earlier than two weeks before you intend to submit it. If the process drags, a quick reissue takes most employers less than a day. Not all employers will issue these letters. Smaller companies, especially those with fewer than 20 employees, sometimes refuse because they do not want to be drawn into third-party disputes. In those cases you fall back to pay stubs, tax transcripts, or bank deposit histories. Knowing this ahead of time prevents panic when HR tells you they cannot help.
What to Do When the Letter Is Not Enough
Sometimes the letter is correct but incomplete. This happens frequently with commission-based roles, seasonal workers, or people who changed jobs mid-year. A single Income Verification Letter will not capture fluctuating income. You need supplemental documentation. Pay stubs covering the last 30 days fill gaps in recent history. Tax returns fill gaps in older history. Bank statements fill gaps when neither of the above is sufficient. Layer them in chronological order and include a brief cover note explaining any discrepancies. Underwriters appreciate clarity more than perfection. If you are dealing with non-traditional income sources such as rental income, alimony, or investment dividends, the standard letter format will not apply. You need additional forms or affidavits. Rental income usually requires a schedule E from your tax return plus lease agreements. Alimony requires a divorce decree or court order showing the obligation and payment history. Investment income requires year-to-date statements from the brokerage or financial institution. Do not assume a generic employer letter covers these categories. It does not.

Using an Income Verification Letter Template
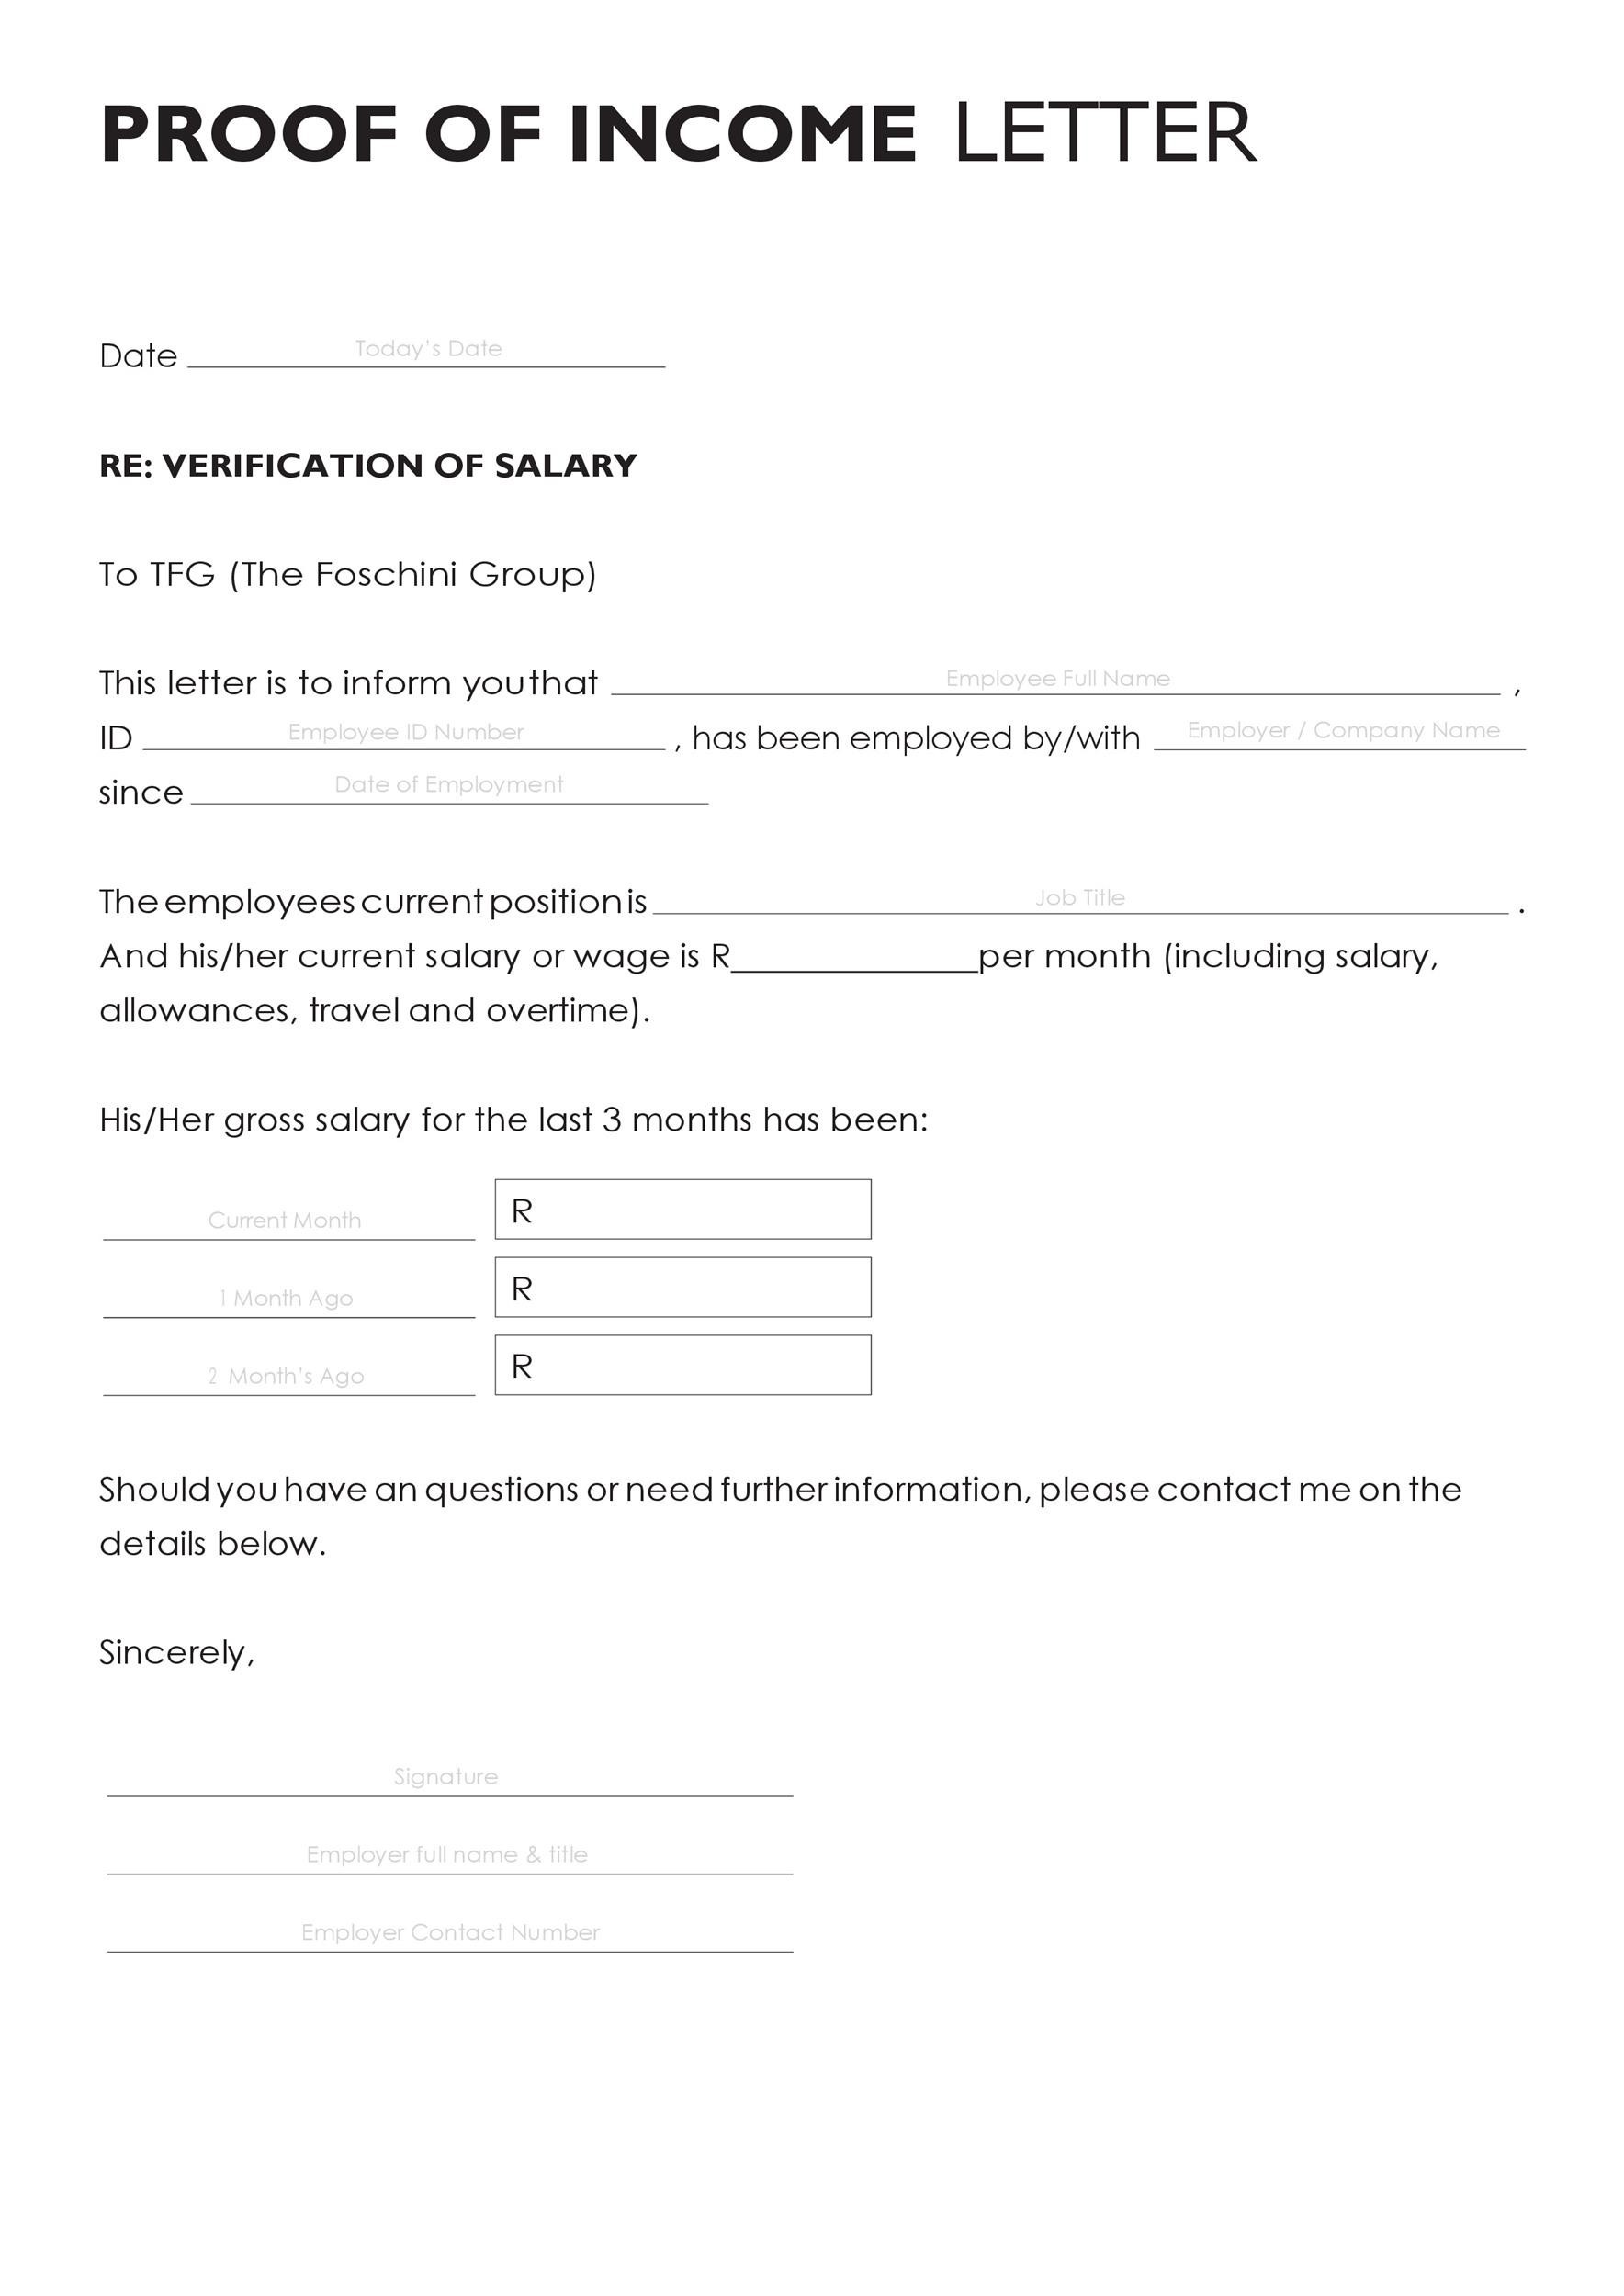
Many employers use internal templates rather than drafting from scratch. If you are the one issuing the letter and need a starting point, a basic template should include the company letterhead, date, employee name and address, SSN or tax ID, position title, start date, employment type, annual or monthly income figure, signature of an authorized representative, and contact information for verification follow-up. Keep it concise. Extra commentary does not help and sometimes hurts by introducing ambiguity. Some third-party services offer generated Income Verification Letter templates for a fee. These are functional but not universally accepted. A template is only as good as the signature behind it. A self-prepared letter without a credible signatory is ignored by most institutions. If your employer has no HR department and you need to request a letter from a bookkeeper or managing partner, make sure that person has the authority to verify employment on the company's behalf. Titles like "operations lead" or "project coordinator" do not carry the same weight as "HR director" or "chief financial officer" in the eyes of an underwriter. The process itself is straightforward. The friction comes from mismatches between what the letter says and what the receiving party needs to see. Knowing the difference early saves time.