What an Income Verification Letter Actually Is
An income verification letter is a straightforward document confirming how much someone earns. Lenders, landlords, loan officers, and government agencies request these routinely. They exist to reduce risk. A bank wants to know you can pay a mortgage. A property manager needs proof that rent won't be late. That's basically it. People overcomplicate this because the template looks deceptively simple. The form itself takes maybe five minutes to fill out once you know what goes where. The problem usually comes later, when the receiving party sends it back asking for supporting documents or a different format. You've lost more time on revisions than you ever will on getting the initial draft right.
Income Verification Letter Template
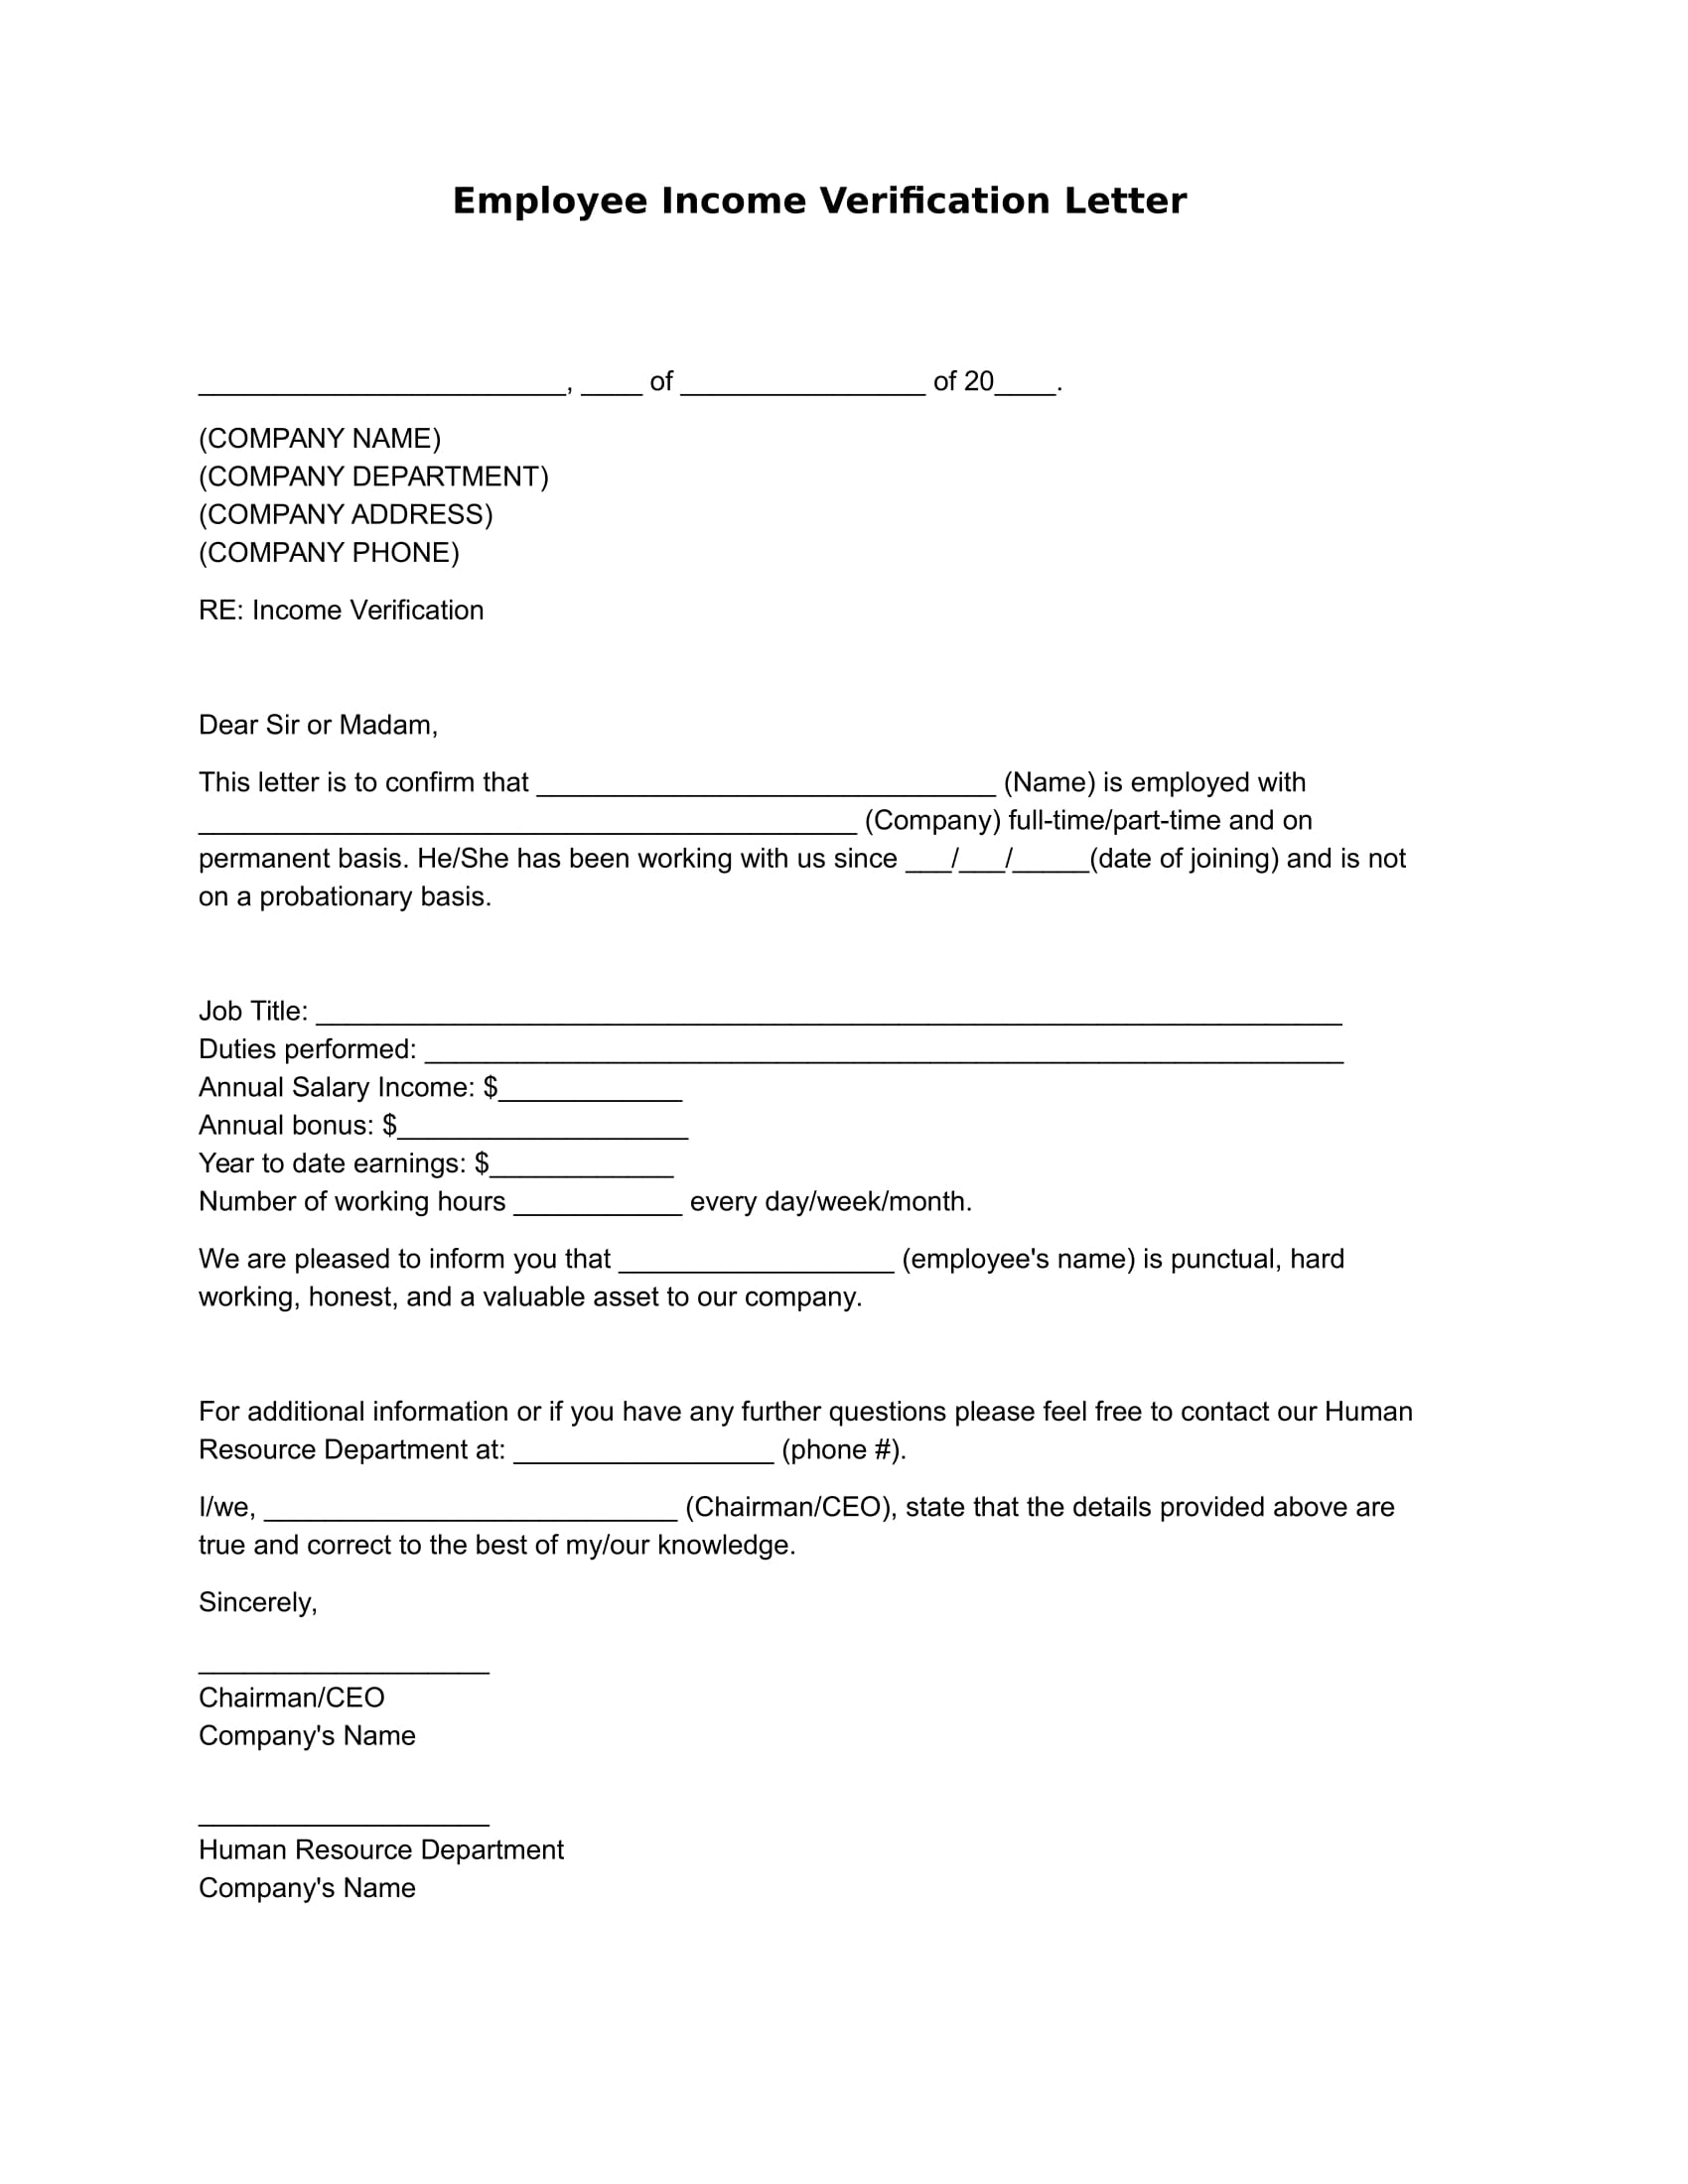
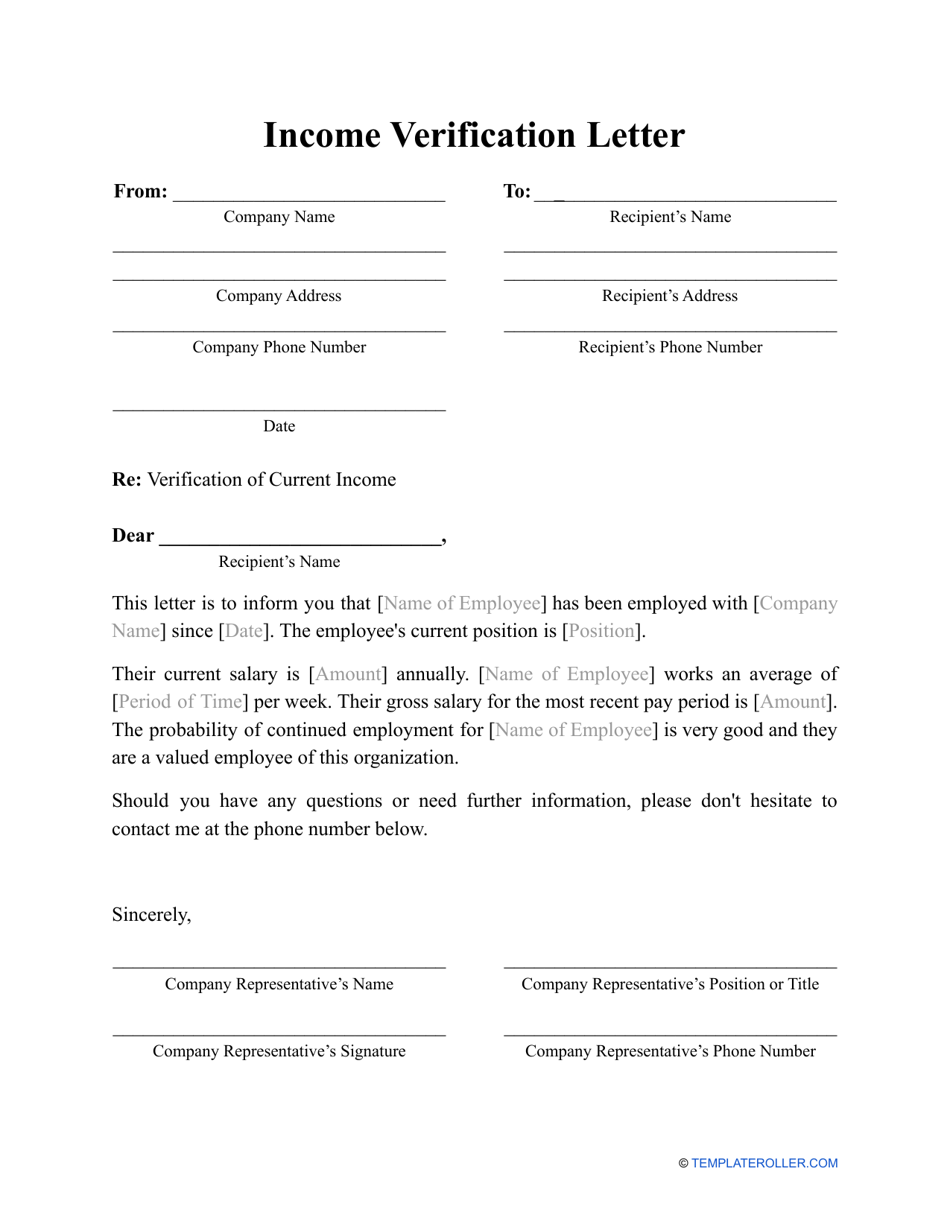
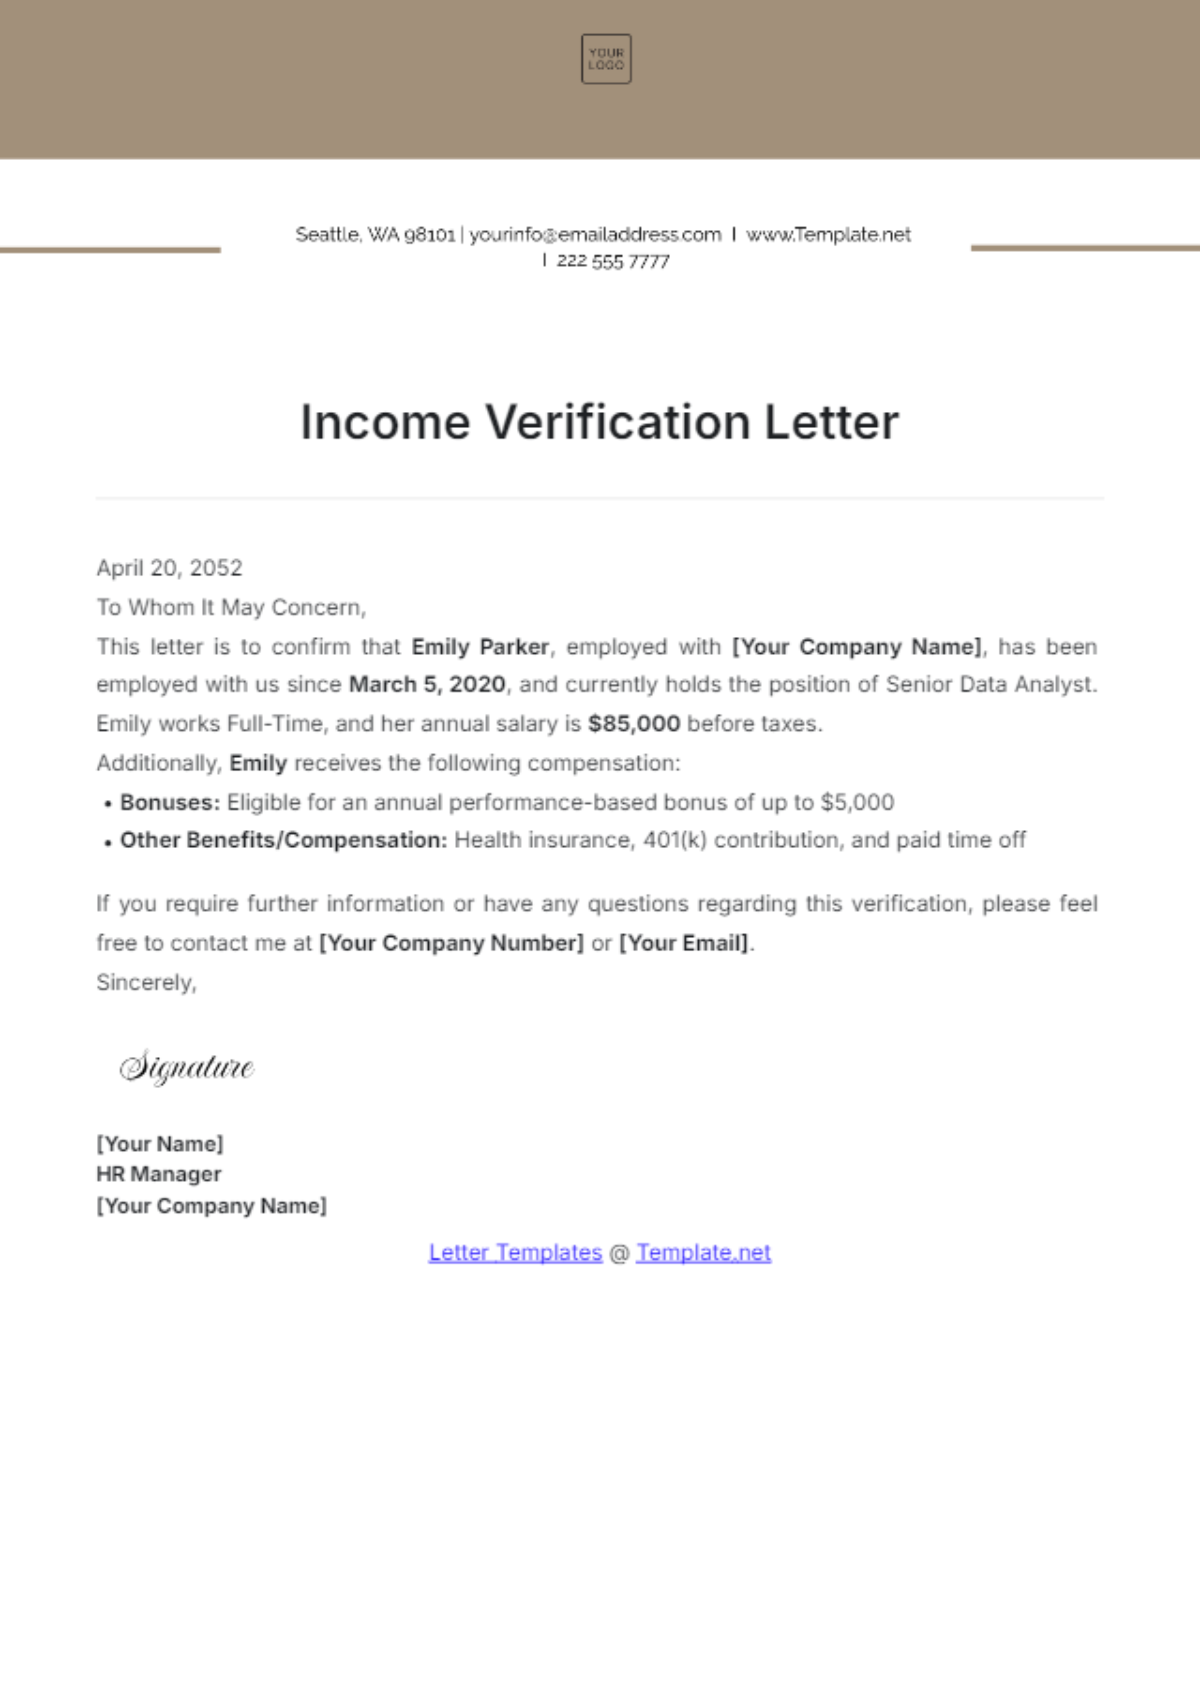
Here is a version you can adapt. Nothing fancy, just what works in most situations. That structure covers the requirements for roughly 80% of requests you'll encounter. Mortgage applications and rental approvals are the two big ones that show up most often. Government benefit applications tend to ask for slightly more detail, which I'll get to in a moment. The biggest mistake is skipping the "at-will" or permanent employment language. Some HR departments write "employed since January 2023" and leave it at that. The lender has no way to know whether that person is likely to stay or if this is temporary staffing disguised as employment. Always specify the nature of the engagement. It takes one extra sentence and prevents three weeks of back-and-forth.
The second mistake is being vague about compensation. "$75,000 plus bonuses" sounds fine until the underwriter asks what percentage of that total is guaranteed versus variable. If you don't know the exact figures, find out before you write the letter. Making a guestimate and putting a number down is worse than not including it. I had a case where I listed a sales commission range that turned out to be the outlier quarter, not the annual average. The underwriter flagged it as unreliable income. We ended up pulling three years of W-2s instead, which added about two weeks to the processing timeline.
Get the Full Details
When a Simple Letter Isn't Enough
Some institutions have their own forms. Fannie Mae uses Form 1003, which includes an income verification section. VA loans sometimes require a separate VA-specific verification. The Social Security Administration asks for pay stubs alongside any letter you provide. IRS verification usually needs a wage and income transcript pulled directly from their system rather than a letter on company letterhead. If you're unsure which path applies, ask the requesting party before sending anything. They'll typically tell you their preferred format within a day or two. Waiting for that clarification upfront saves you from redoing the work later.
What Counts as Reliable Proof
A letter on company letterhead signed by someone with authority to verify employment carries weight. That means HR, a direct manager, or a designated payroll contact. Not the office intern who "helps out with paperwork." The signature should include a phone number and title so the verifier can be reached independently. Pay stubs are usually requested alongside the letter, not as a replacement. They corroborate the numbers in the letter. Most verifiers want to see at least the most recent 30 days of pay history. Some want two full years if you're self-employed or on commission.
Processing Time Realities
From my experience, a well-prepared letter comes back with questions about 15% to 20% of the time. The requests are usually minor: missing pay frequency, no direct phone number, or a signature that doesn't match any public records on file. Having the letter and pay stubs ready simultaneously cuts the back-and-forth cycle significantly. If you send the letter alone, expect to wait another few business days for the follow-up request on documentation. For self-employed individuals, this template doesn't apply directly. You'll need profit-and-loss statements, tax returns, and sometimes a letter from your CPA. That process is longer by design. Lenders want to see two years of consistent income patterns, not a single snapshot.

Quick Checklist Before Sending
Company letterhead is present. Employee name matches government ID exactly. Dates are accurate and verifiable through payroll records. Contact information is current and someone actually answers the phone. Compensation figures align with what appears on recent pay stubs or W-2s. The signatory has the authority to verify employment on behalf of the company. If any of those items feel uncertain, hold the submission until you can confirm them. A letter with a wrong date or a dead phone number triggers the same kind of delays that a missing letter does. It's not faster to send something incomplete and fix it later. It's slower.