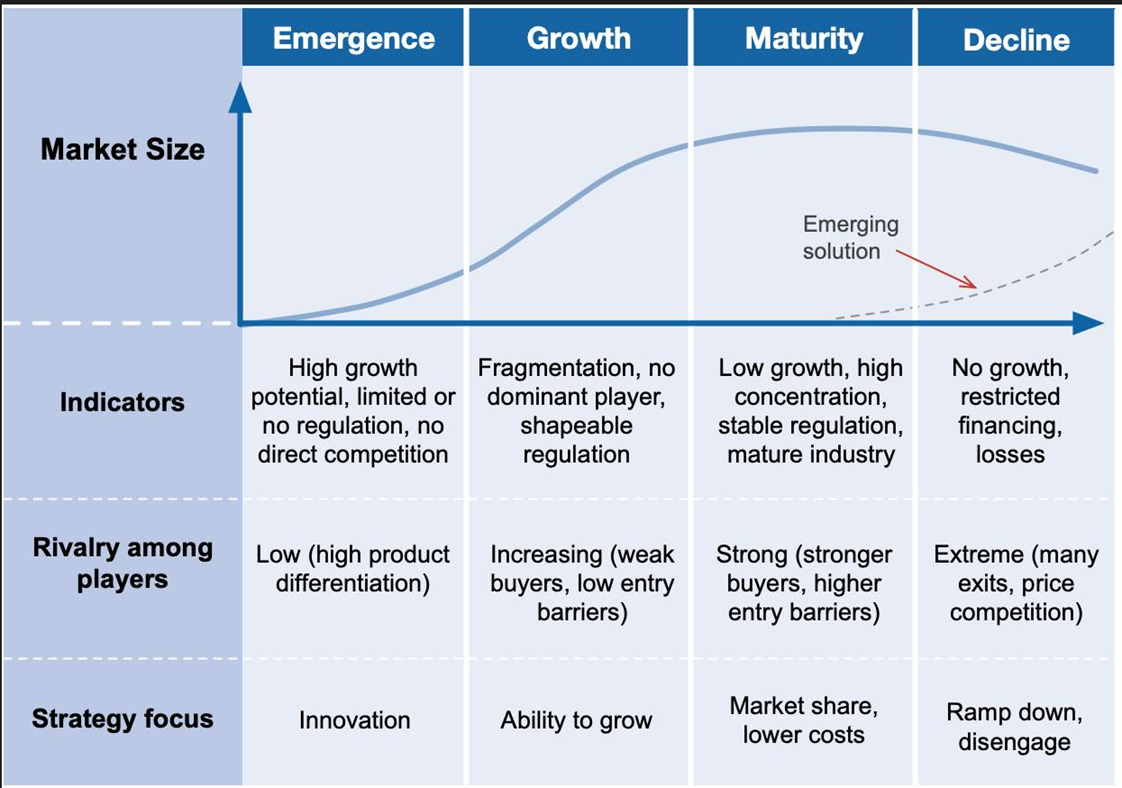
How to Actually Do Industry Life Cycle Analysis Without Losing Your Mind
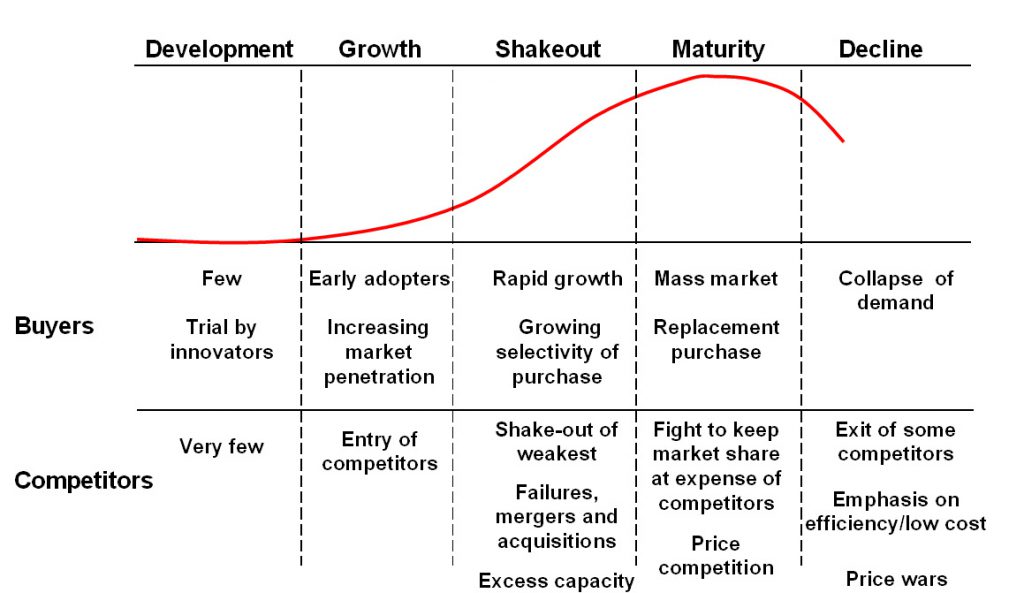
Most people approach Industry Life Cycle Analysis as if it's a straightforward classification exercise. Map some data points to a curve, call it done, and move on. The reality is considerably messier. You're trying to compress years of market dynamics, competitive behavior shifts, and technological disruption into a single framing model, and the model was never designed to be precise. The first step is picking the right boundaries. If you define the industry too broadly, the lifecycle shape disappears into noise. If you define it too narrowly, you're just tracking a single company's trajectory and calling it an industry. A few years ago I was working on a project for a mid-market industrial sensors manufacturer, and the initial scope we used was "IoT sensors." The lifecycle data came back looking like a flat line because smart home sensors and precision agriculture sensors were in the same bucket. They were completely different adoption curves, different buyer psychology, different pricing pressure. We re-scoped to "agricultural moisture sensors for large-scale farming," which gave us a much cleaner pattern. It took about three extra days of segmentation work, but the rest of the analysis that followed it was roughly twice as fast because the data wasn't fighting itself. Once the boundaries are set, you need five data series at minimum: total addressable market size over time, number of competitors year over year, average deal size trends, patent filings per quarter, and customer concentration metrics. You can pull TAM from vendor reports like Gartner or IDC if you're lucky enough to have budget for them, otherwise you build it from the bottom up using public financials and shipment data where available. Competitor counts come from trade directories, government registrations, and LinkedIn headcount trends. Patent data is on Google Patents or the USPTO bulk database. Customer concentration you derive from top-10 customer revenue percentages in annual reports.
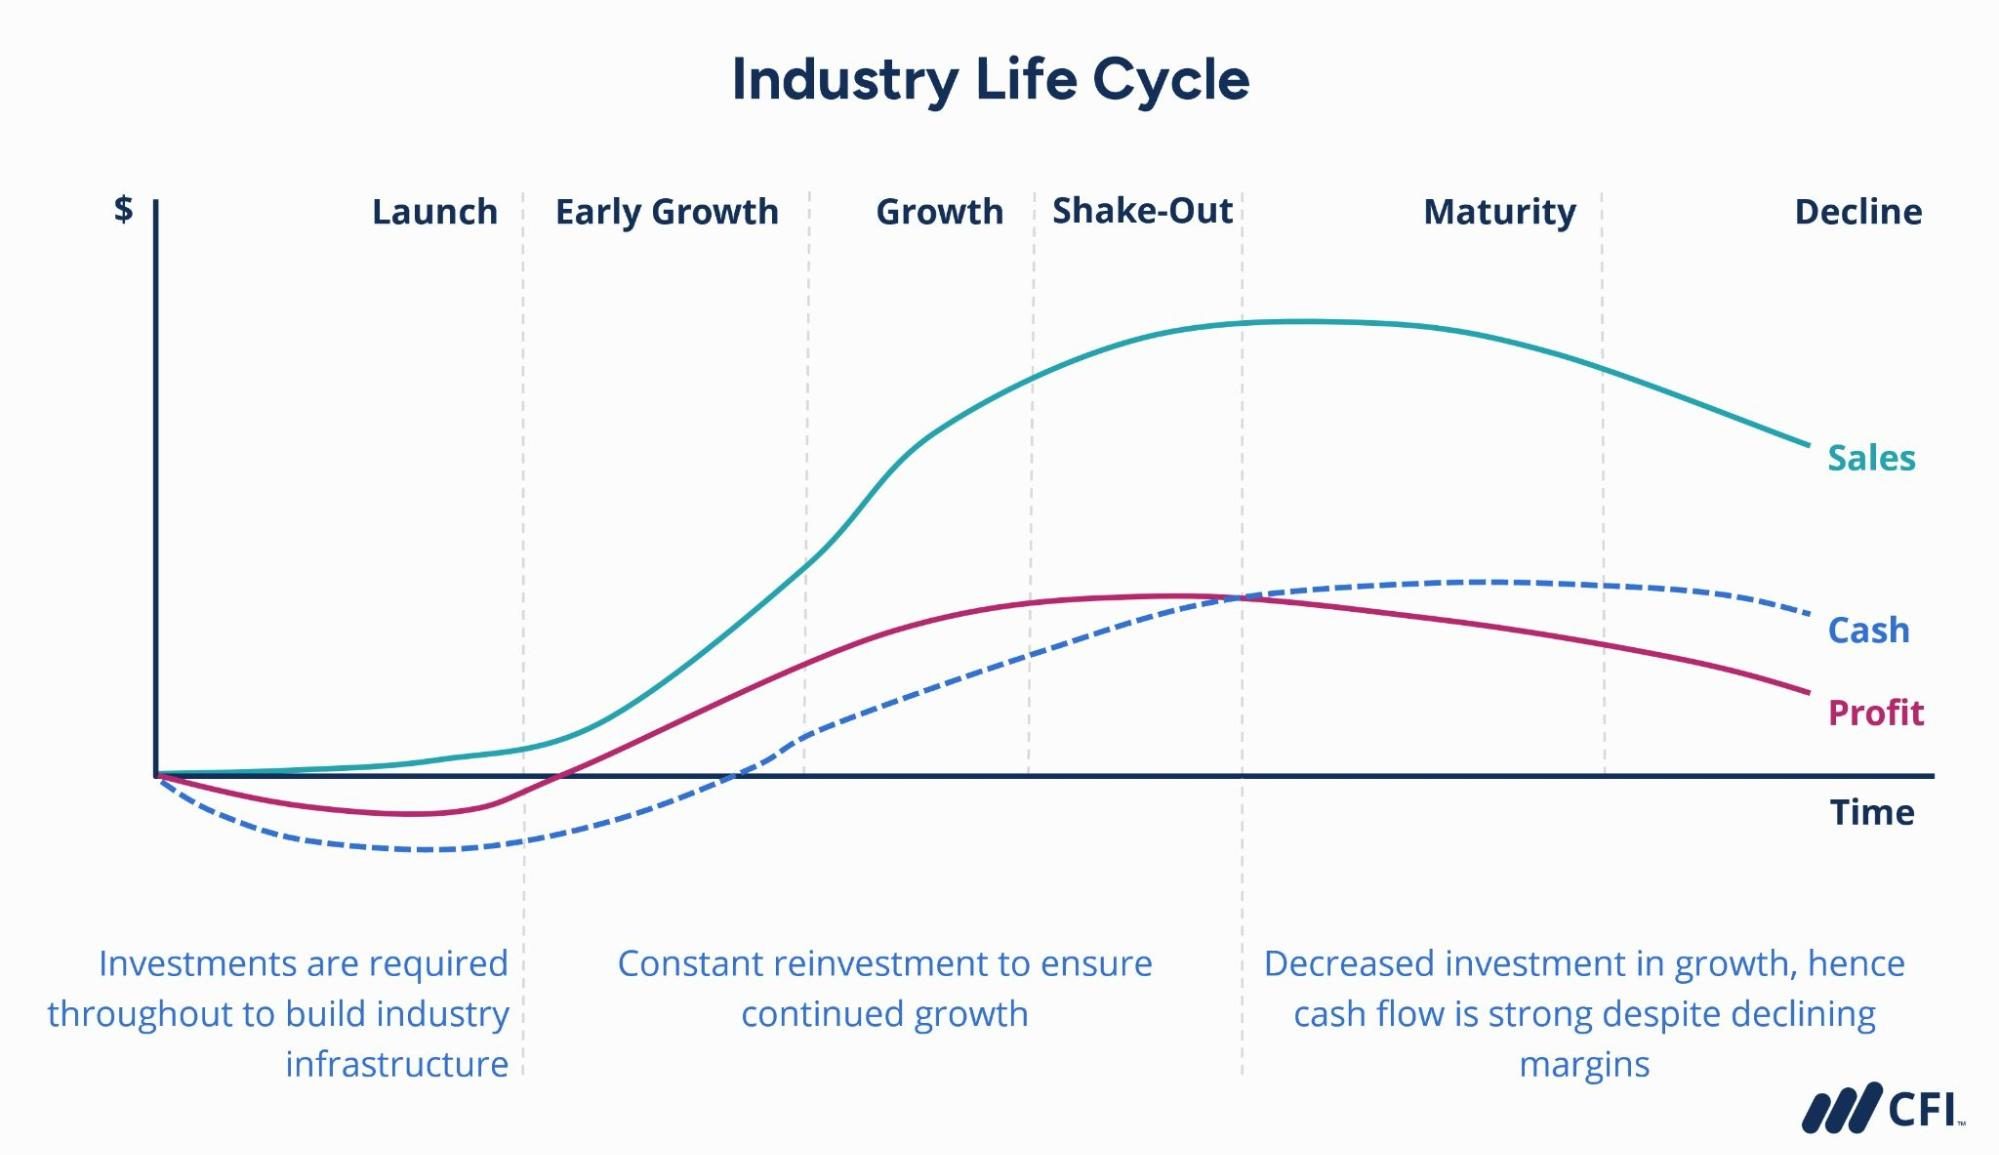
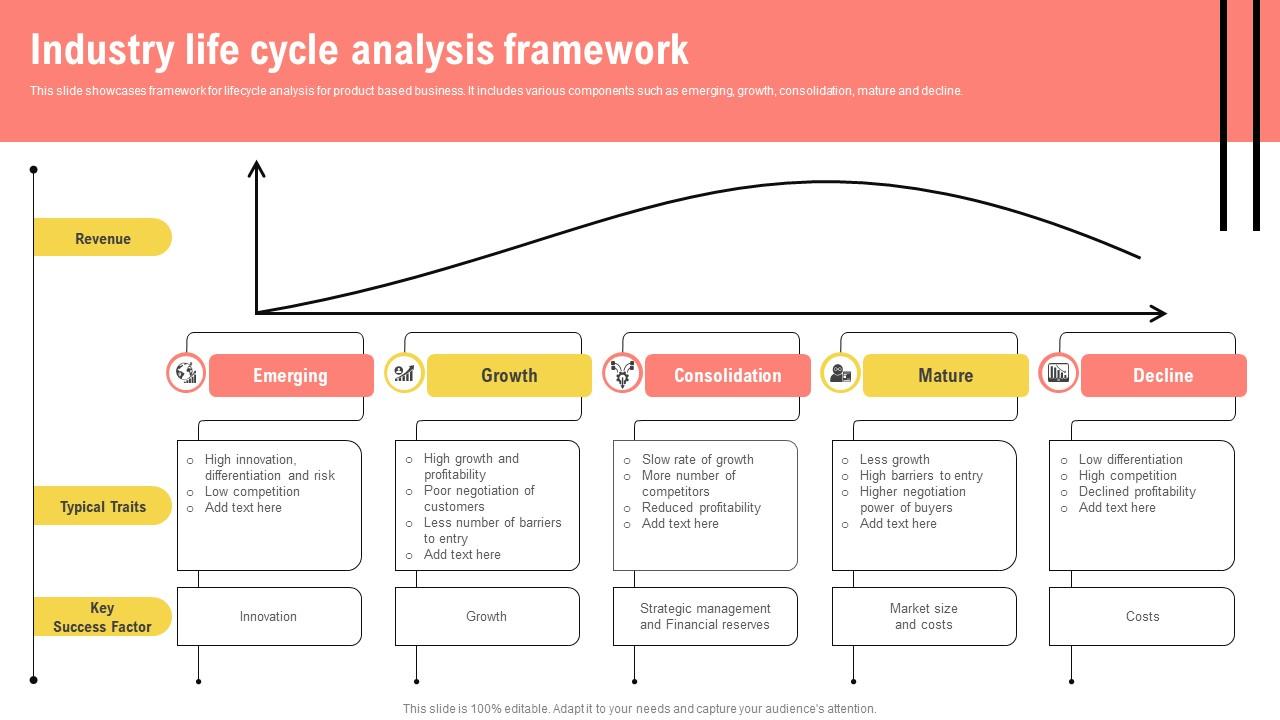
The actual lifecycle determination happens when you plot these against each other, not in isolation. A growing TAM with stabilizing competitor count and declining average deal size usually signals the growth-to-shakeout transition. That's the signal most beginners miss. They see rising revenue and assume expansion phase when the margins are already compressing. I've seen two separate investment teams disagree on the phase of the same wind energy sector because one looked at installed capacity numbers and the other looked at turbine OEM margin trends. Both were right. Both were incomplete.
Common Pitfalls That Wreck This Analysis
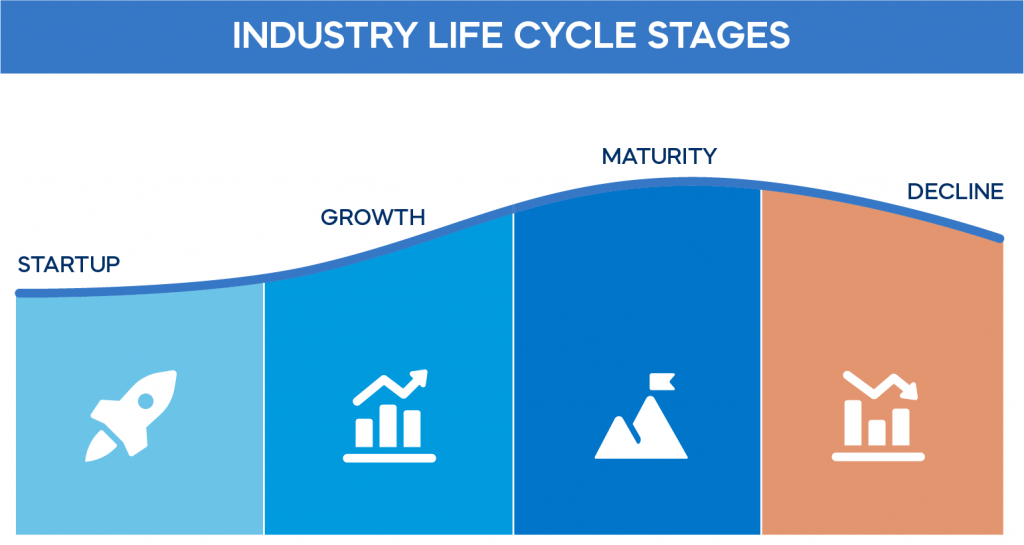
The biggest mistake is assuming the four phases exist in order for every industry. Some sectors jump straight from introduction to consolidation because a platform company acquires the category before it ever matures. Social media advertising was essentially born scaled. There was no slow build, no early adopter elongation period. Treating it like it had a natural growth phase distorted the entire competitive assessment. Another issue is recency bias in your time window. If you only look at the last five years of data, a mature industry might look like it's entering growth because of a regulatory tailwind or a new technology enablement event. I once worked a utilities modernization project where the dataset started in 2018. The analysis showed accelerated growth across the board. It wasn't until we extended back to 2008 that the decay phase became visible, and the entire investment thesis changed. Adding historical context took about twenty minutes of spreadsheet work and saved us from a materially wrong conclusion. There's also the problem of geographic fragmentation. A sector might be mature in North America, growing in Southeast Asia, and in decline in Europe. Aggregating those into a single lifecycle reading produces a result that doesn't match any real market. You need to segment by region at the data collection stage, not after the analysis is already done. That's a process change that most teams skip because it requires more upfront classification work, but it's the difference between a useful framework and a misleading chart.
Get the Full Details

When the Method Breaks Down Completely
Industry Life Cycle Analysis does not work well in markets driven by regulatory arbitrage or subsidy cycles. Government incentives create artificial demand spikes that look like organic growth on the curve. The battery storage sector in certain European markets showed repeated false growth signals between 2019 and 2023 because policy changes shifted adoption timing by eighteen to twenty-four months. The lifecycle model couldn't distinguish between policy-driven acceleration and genuine market maturation without supplementary regulatory timeline mapping. The method also struggles with platform-dependent industries where the lifecycle belongs to the underlying platform, not the application layer. A payment processing tool riding on a social media platform isn't on its own lifecycle curve. It's on the platform's curve. I had to layer a dependency analysis on top of the standard framework to separate platform risk from category risk, which added a week to the project but was necessary to avoid recommending investments that looked attractive on the surface. The base analysis alone would have missed it entirely. If you're dealing with a sector under active antitrust scrutiny, the lifecycle signals become unreliable because the regulatory environment is actively suppressing competitive dynamics that the model expects to see play out naturally. In those cases, supplement the lifecycle analysis with a regulatory impact assessment or switch to a scenario-based framework instead. The standard four-phase model assumes relatively free market evolution, and that assumption is void when government action is a primary market force.
Practical Execution Notes
Build the analysis in spreadsheets first. Don't jump to visualization tools until the underlying data is stable. I usually spend about forty percent of my time on data cleaning and verification before I ever plot a single trend line. The cleaning catches inconsistent reporting periods, duplicate competitor entries, and regions that shouldn't be aggregated. It's tedious work but it prevents you from building a narrative on broken input. Use relative metrics rather than absolute ones where possible. Year-over-year percentage change in market size is more reliable than raw dollar figures because it removes currency and inflation noise. Same thing with competitor count - use the rate of new entrants relative to exits rather than the net headcount, which can stay flat while the market composition completely shifts underneath it. These refinements add maybe ten percent more work at the data stage but significantly improve the interpretability of the lifecycle phase identification. Document every data source and the reasoning behind boundary decisions in a separate tracking sheet. When someone challenges your phase assignment six months later, you need to be able to point to exactly what you measured and why. That documentation habit has probably saved me more credibility than the analysis itself in client meetings. It's boring, unglamorous work, but it's the difference between an opinion and a defensible position.