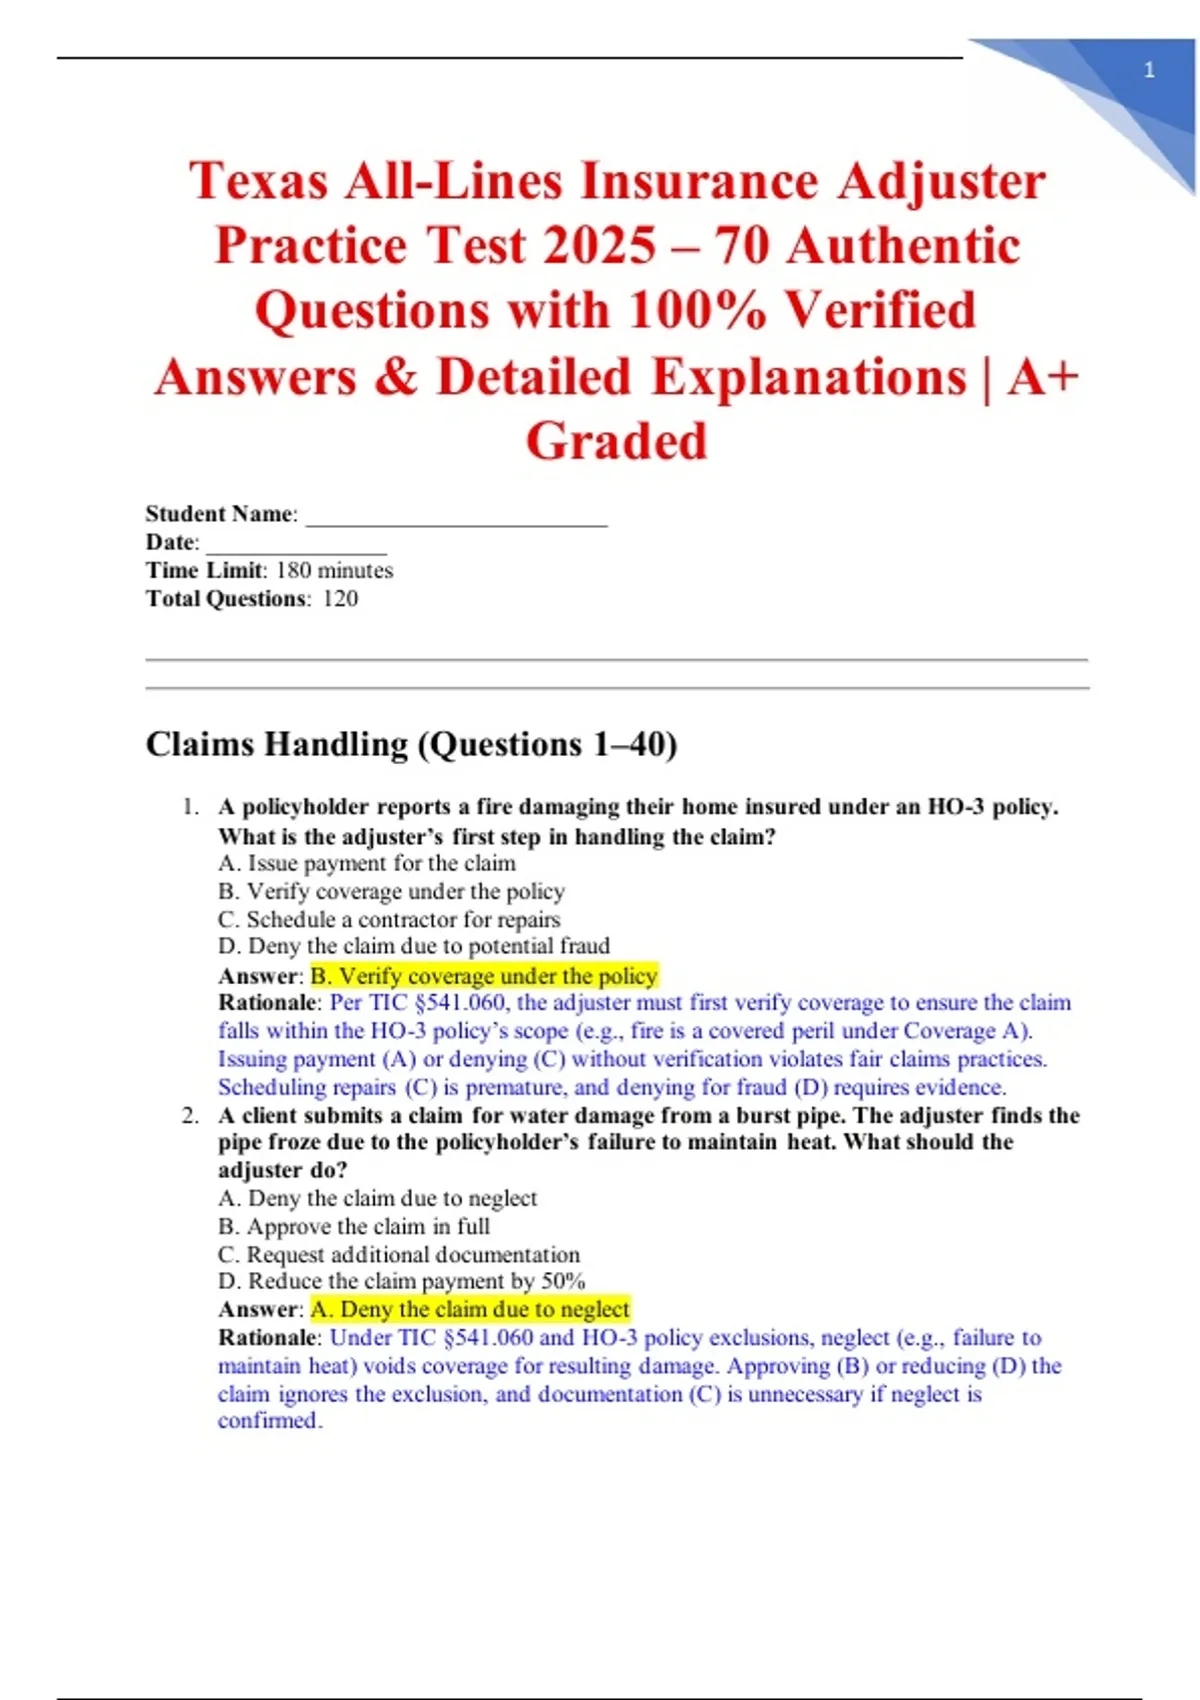
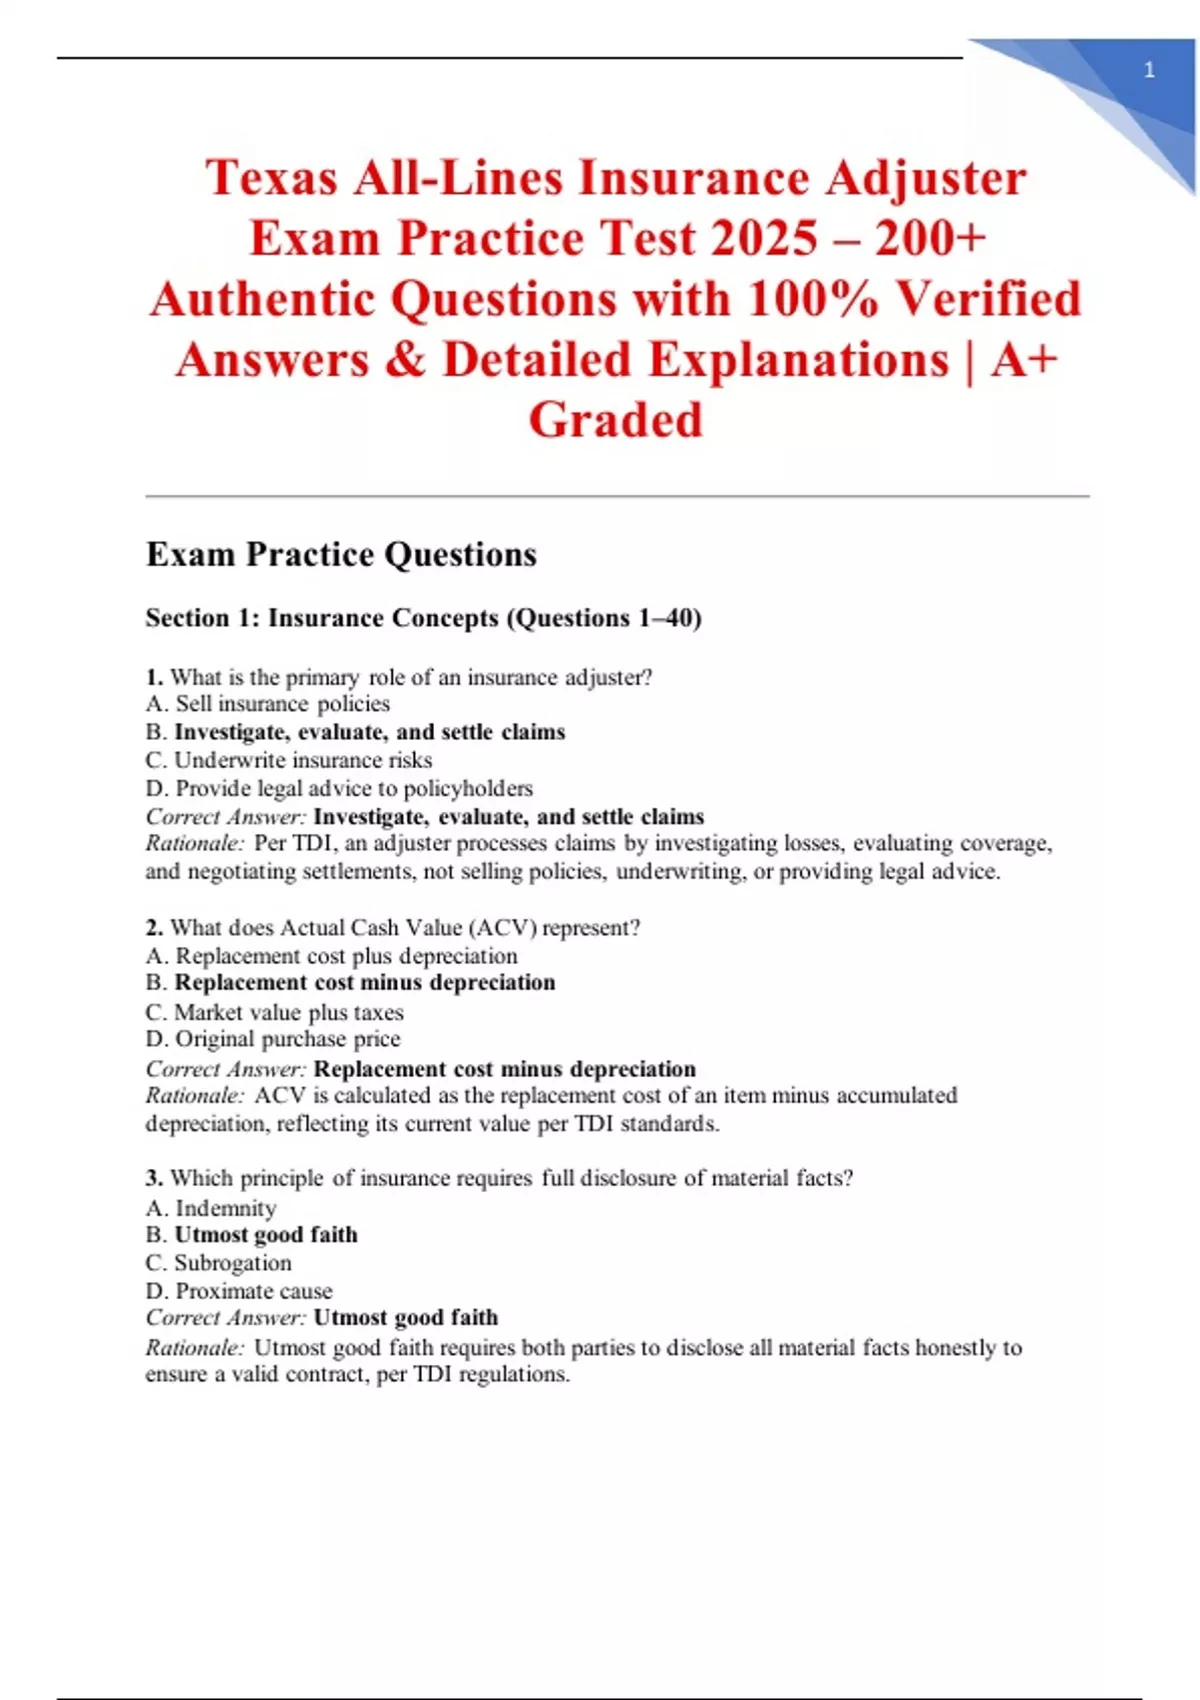
Why Most People Fail Their Adjuster Exam
I've sat through enough of these exams to know what separates people who pass from people who waste their money retaking it. The difference isn't intelligence. It's strategy. You treat it like a trivia contest and you'll fail. You treat it like a practical exercise with a time limit and you'll likely pass on the first try. Most study guides make you memorize definitions until your eyes bleed. That's backwards. The exam doesn't care if you can recite what a deductible is. It cares if you can identify which clause applies when a homeowner's basement floods because the sump pump failed during a storm. I learned this the hard way during my own licensing process back in 2009. I scored 72% on my first practice test despite knowing every definition cold. The questions were scenario-based and I kept looking for the textbook answer when the exam wanted the practical one. The real structure of these exams breaks down into three sections that get weighted differently depending on your state. Property claims handling dominates about 40% of the questions. Liability and general principles make up another 30%. The remaining 30% is a messy mix of ethics, state-specific regulations, and coverage interpretation. Your weak area will show up as wrong answers, not vague uncertainties. Wrong answers are specific. That's how you know what you didn't study.
How to Use Practice Tests Without Wasting Them
Here's what most people do wrong. They take a practice test, check their score, and move on. That's useless. A practice test without a detailed review cycle teaches you nothing about why you got something wrong. The only useful process is to take the test under real conditions, grade it honestly, then go back through every single wrong answer and look up the actual policy language or state regulation that makes it correct. I spent three weeks doing this before my exam. I took seven different practice tests. The first one I dropped to 58%. The seventh I pushed to 81%. The improvement wasn't from studying more. It was from understanding the pattern of how the exam writers trick you. They'll give you two answers that both sound right, but one is technically more complete. The more complete one wins. Always pick the answer that leaves fewer assumptions. There's a specific trap around subrogation and assignment of benefits that shows up in almost every exam I've seen. The test will describe a situation where an insured receives a payment from their own carrier and then signs over their rights to collect from the at-fault party. The answer choices will include terms like "subrogation," "conciliation," "reconvention," and "indemnification." The correct answer is subrogation. But they'll dress it up so carefully that people second-guess themselves. I've seen this exact scenario come up on three separate state exams now.
The Timing Problem Nobody Warns You About
The biggest bottleneck on these exams isn't knowledge. It's time. Most exams give you somewhere between 90 minutes to 2 hours for 100 to 150 questions. That's roughly 36 to 80 seconds per question depending on the state. Questions with long scenario descriptions eat time fast. I've learned to read the answer choices first on the heavy scenario questions. It sounds counterintuitive but skimming the options before the passage tells your brain what to look for and cuts your reading time in half on those ones. One practical workaround that actually works: flag every question you're unsure about and move on. Don't sit there debating a single question for two minutes. You'll run out of time on questions you actually knew. I use a simple note system where I circle questions that felt even slightly ambiguous. Then I review those in the last 20 minutes with whatever time remains. Most of the time you'll catch your original answer was right and leave it alone. Sometimes you'll spot something you missed. Either way, moving on saved you time.
Get the Full Details
Insurance Adjuster Practice Test Resources That Actually Help
Not all practice tests are equal. Some are updated for the current exam format. Some are stuck in 2015 and still ask questions about regulations that don't exist anymore. Before you spend any money or time on a particular resource, check the dates. Look for practice tests that reference ISO forms, HO-3 policies, and the current ISO declarations page structure. If a practice test hasn't been updated since 2020, assume half its questions are obsolete. The best free resource I found was the state DOI's own sample questions when they published them. They're usually outdated and sparse, but they're the real deal. Third-party prep courses like Adjuster Institute and ExamFX are better for volume but they charge money and some of their questions drift into territory that never actually appears on the exam. I'd recommend using one paid resource for the volume it provides and cross-referencing anything that feels off with your state's actual insurance code.
What the Exam Won't Tell You
Here's something nobody puts in their marketing materials. The exam is designed to catch people who only studied one book. If you rely exclusively on a single prep guide, you'll encounter questions written in language that guide doesn't use and you'll freeze up. The exam writers pull from multiple sources. ISO manuals. State statutes. NAIC model laws. Standard policy forms. No single book covers all of it equally well. Another thing: the exam tests your ability to interpret ambiguous situations, not your ability to find a clean right answer. In real adjusting, most claims fall in gray areas. The exam replicates this by making two answers defensible. The trick is figuring out which answer the exam writers consider more correct based on standard industry practice. When in doubt, choose the option that protects the insured's interests while staying within policy language. That's the default position exam writers expect you to take. I remember one specific question from my own exam that described a water damage claim where the policy had an exclusion for gradual seepage but the damage was sudden and accidental. The answer choices hinged on whether the exclusion applied retroactively to the entire claim or only to the portion caused by gradual damage. I spent about 90 seconds on that one. The correct answer was that the exclusion applies only to the gradual damage portion, and the sudden damage portion is still covered. That distinction matters in real claims too, not just on the exam.
One more practical tip that most people ignore. Bring a watch. Some exam centers don't have visible clocks and even if they do, looking away from your screen wastes time. A simple wristwatch lets you track your pace without breaking concentration. If you're doing math-heavy property calculations, having time management under control prevents panic when you realize you're behind. The bottom line is that passing this exam comes down to practiced exposure to the question format more than raw knowledge. You can know every clause in an HO-3 policy and still fail if you've never seen the way the exam writers phrase their questions. Take enough practice tests under timed conditions, review every mistake thoroughly, and you'll be fine. Skipping the review step is the most common reason people keep failing the same exam.