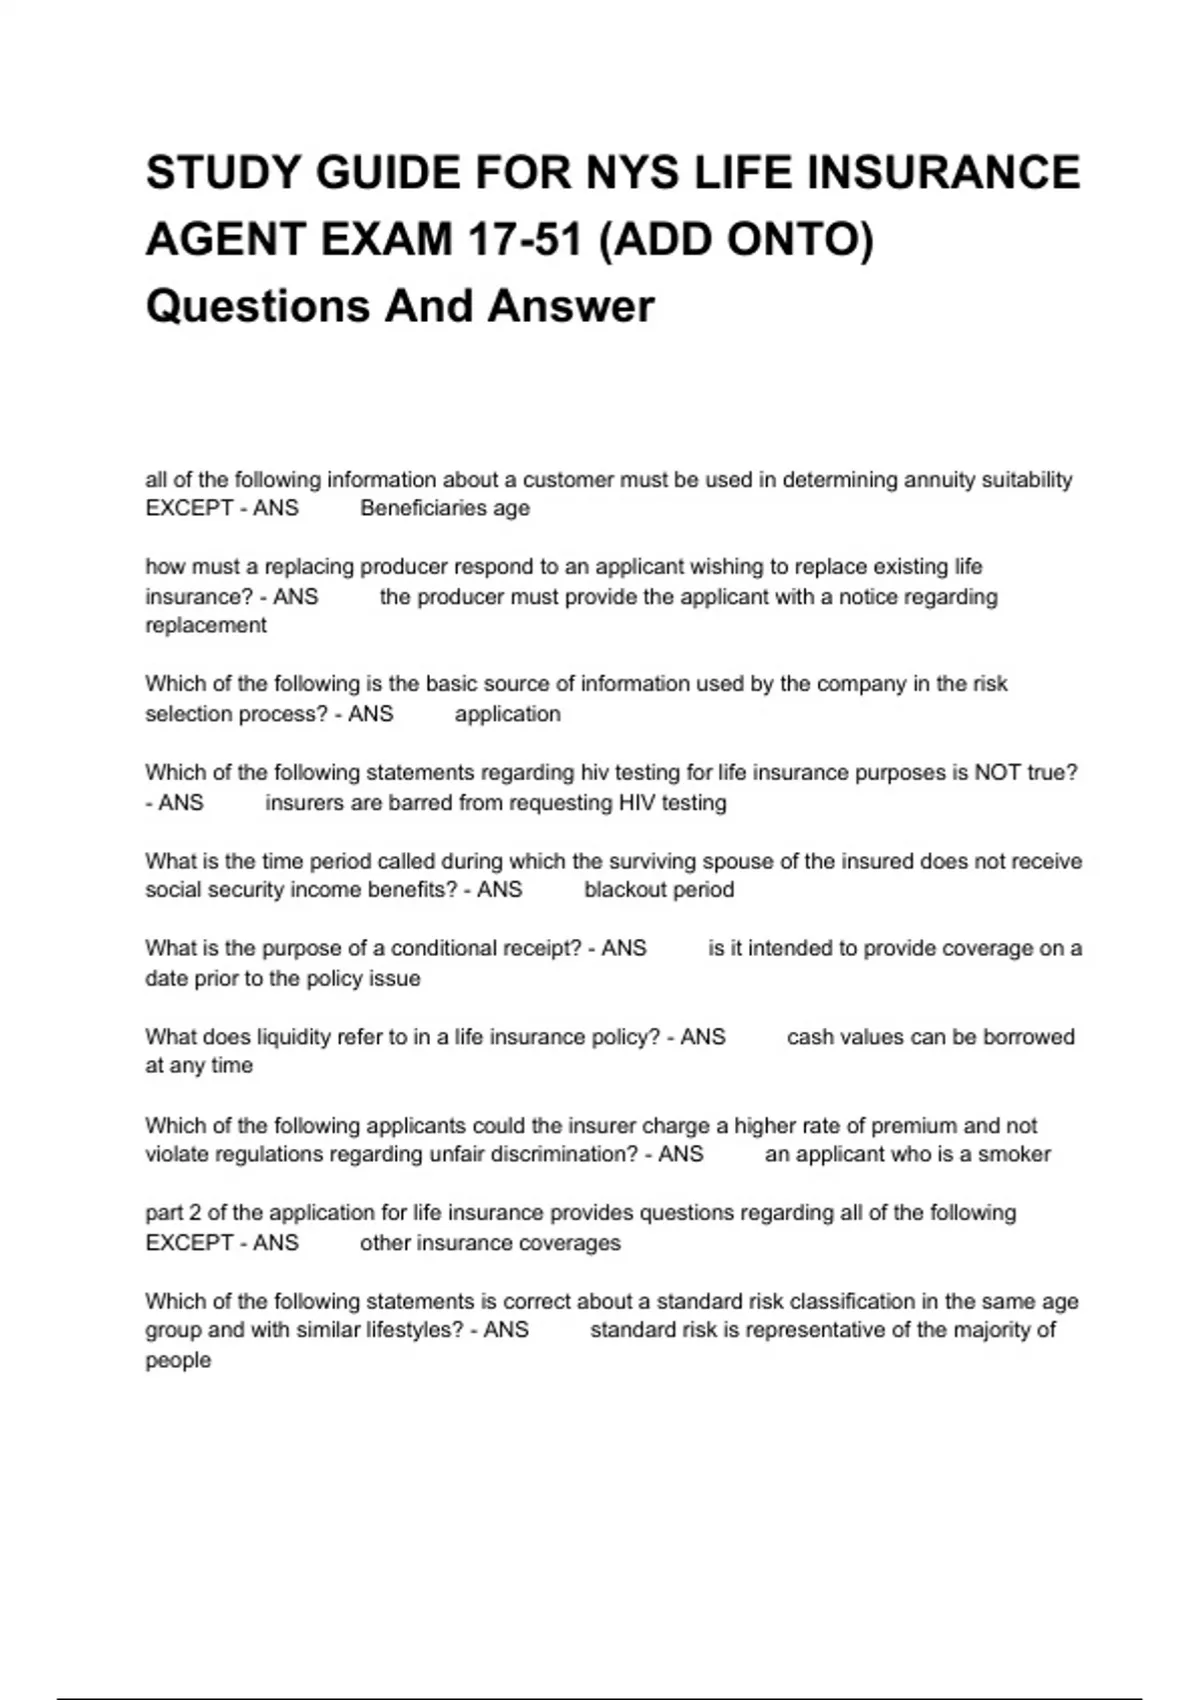
What You Actually Need When Studying for Your Insurance License
Most people treat the Insurance Agent Study Guide like it's a magic bullet. They buy a thick packet of flashcards, watch some video series, and expect to walk into the exam room knowing everything. It doesn't work that way. The licensing exam tests your ability to apply concepts under time pressure, not your ability to recite definitions. I've watched people memorize entire study guides word for word and still fail because they couldn't distinguish between a "best answer" and a "technically correct answer" on a scenario question. Here's how I actually approached it when I was getting licensed in three states over a two-year span. I started with the official pre-licensing course requirements for my first state, then layered in third-party practice exams. The key insight nobody mentions is that the state's own syllabus matters more than any commercial study material. Each state structures their exam differently. California spends heavily on ethics and consumer protection questions. Texas is heavy on policy provisions and contract law. Florida throws in a lot of variable annuity and long-term care material. Your study guide needs to reflect the actual weight distribution of your state's exam, not some generic template you found online. I keep a running spreadsheet tracking which topic areas I'm scoring below seventy percent on across practice tests. That spreadsheet became my de facto Insurance Agent Study Guide because it was tailored to my specific weak points. Generic guides waste time on material you already understand. The first time I did this, I cut my total study time roughly in half compared to my previous attempt where I just worked through a commercial prep course linearly. I went from studying maybe thirty hours to about fifteen, and my scores jumped from the low sixties to above eighty-five on practice exams.
One specific edge case that threw me off initially: the difference between a binder and a receipt in property and casualty insurance. Every study guide I used gave me a textbook definition. The exam question described a scenario where an agent handed someone a signed application and a temporary document at the time of a meeting, then asked what coverage was in effect. Three of the four answer choices were defensible depending on how you read it. The correct answer hinged on whether the premium was actually collected. If premium wasn't taken at the time of the binder delivery, coverage didn't attach yet in that state's regulatory framework. I had to look up the specific state regulation because the study guide had glossed over it. That became a permanent note in my personal guide. Now I flag every topic where the exam seems to test regulatory specifics rather than general principles. For life and health specifically, the trickiest area is definitely the replacement rules and suitability requirements. The NAIC model regulations changed significantly a few years ago, and many states adopted versions that don't match the older study materials still floating around. I spent about four hours re-studying the replacement section after my first attempt because my prep course was using pre-2020 wording. Make sure whatever Insurance Agent Study Guide you're using notes its revision date. If it doesn't, assume the compliance and ethics sections are probably outdated. Practice exams are where most people go wrong too. They take one test, get a score, and move on. The useful approach is to take a test, spend more time reviewing the missed questions than you spent taking the test, and then retake it after a couple days. I found that my retention improved dramatically when I was forced to retrieve the information again rather than just re-reading explanations. The gap between my first and second attempt on the same practice exam was usually fifteen to twenty percentage points. That gap represents the actual learning happening.
There's a limit to how much a study guide can help you with certain topics though. Concepts like actuarial basics, risk pooling mechanics, and the mathematics behind premium calculation won't click from memorization alone. If you're struggling with those sections, you need to find worked examples, not definitions. I ended up watching lecture recordings from community college insurance courses because the commercial prep materials treated those topics as throwaway chapters. Understanding why a premium is calculated a certain way matters more than memorizing the formula for the exam, even though the exam will ask you to apply it. Another thing people overlook: the unattended exam security measures. Some states now use video monitoring and randomized question ordering. If you're used to studying with the answers right next to the questions in your flashcard app, you're building the wrong skill. Practice under conditions that resemble the actual testing environment. Close your notes. Set a timer. Don't look anything up until you've committed to an answer. This takes more time upfront but saves you from the panic that happens when you realize you can't flip back and forth during the real exam. If you want downloadable materials, the state insurance department websites are the most reliable free source. They publish the exact content outlines and sometimes sample questions. Private companies sell polished prep courses, but you're paying for convenience, not necessarily better content. The raw material is usually available without spending money. I used the Texas Department of Insurance's published exam content outline as my chapter headers and filled in the details from a combination of free resources and one commercial practice exam package. Total cost was under sixty dollars for everything I needed.
Get the Full Details
The one scenario where a commercial Insurance Agent Study Guide actually earns its price is when you need structured accountability. If you know you'll procrastinate without deadlines, a course with scheduled modules and progress tracking is worth it. But if you're disciplined enough to follow your own schedule, the free materials from your state's regulatory body plus targeted practice exams will get you through. Just make sure your materials are current and your practice questions force you to think through scenarios rather than match terms to definitions.