Getting Your Money Back for Therapy
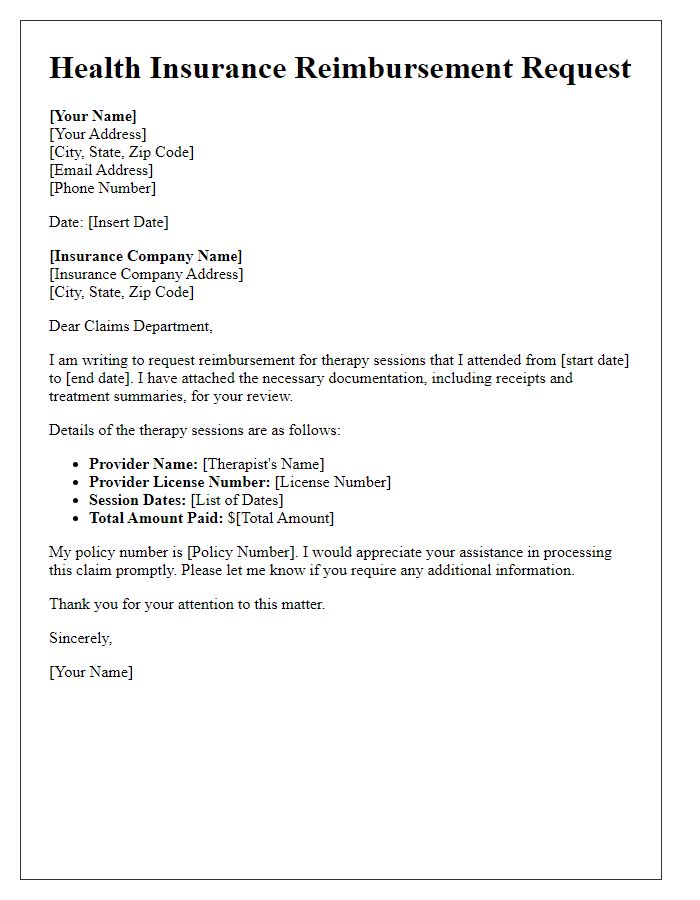
Most people don't realize that getting reimbursed for therapy is entirely possible, but it usually means paying upfront and chasing paperwork afterward. Your insurance doesn't automatically pay your therapist directly unless you're specifically enrolled in their network. That distinction matters more than most people understand going into it. The basic mechanic is straightforward enough: you pay your therapist at the end of each session, they give you a receipt or superbill, and you submit that to your insurance company. The insurance company then determines their allowable rate and cuts you a check or deposits it into your account. What happens next depends entirely on your plan's terms, which is where things get complicated. Your deductible comes into play first. If you haven't met it yet, you're out of pocket for the full session cost until you hit that threshold. After that, coinsurance kicks in — typically 20 percent in many plans — meaning you'd get back roughly 80 percent of what they consider a reasonable charge. But and this is the part nobody tells you — therapists often charge rates higher than what insurance deems reasonable, so your reimbursement won't cover the full session cost even after your deductible is met.
I spent about three weeks last year untangling a reimbursement issue where my therapist's superbill listed a service code that my insurance company had already denied twice before. It turned out she was using an outdated diagnostic code that their system flagged automatically. I had her resubmit with the current ICD-10 code, and the whole thing cleared within a week. That's a real-world example of how these processes actually fail and get fixed. The lesson is to keep copies of everything and always verify that codes are current.
What You Need From Your Therapist
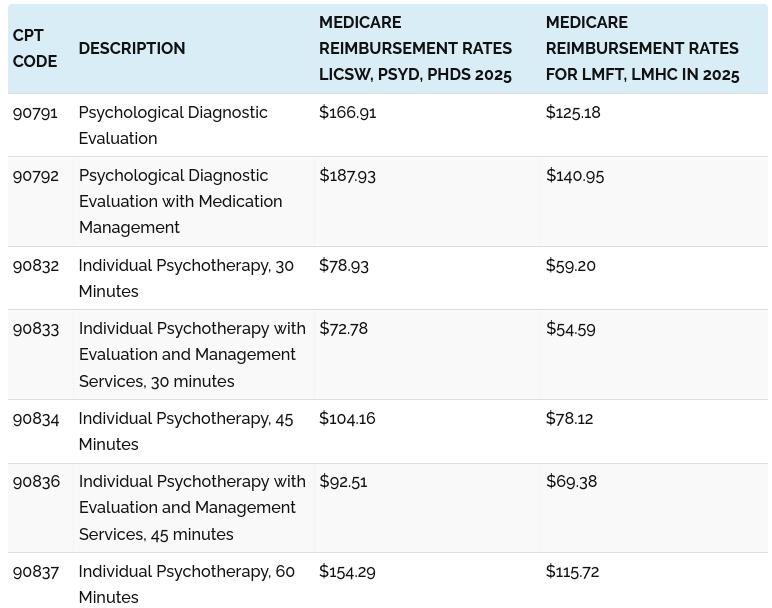
Not every therapist provides superbills, and not all of them will even if you ask. Licensed professionals like LCSWs, LMFTs, and PhD psychologists are generally set up to issue them, but some counselors operating under different credential types might run into limitations depending on their state licensing. Your therapist needs to be willing to provide a detailed receipt that includes their NPI number, your diagnosis code, the CPT code for the session, the date of service, and the amount paid. A standard superbill looks something like this: a one-page document that breaks down the service (90837 for a 53-minute individual therapy session is the most common), the diagnosis (F41.1 for generalized anxiety disorder if that's your billing code), and the fee. If your therapist can't produce something like this, reimbursement becomes significantly harder. Some smaller practices don't keep track of diagnosis codes the way medical providers do, which creates a gap that falls on you to bridge. Here's something most guides don't mention: you can often request this documentation yourself if your therapist isn't proactive about it. Under HIPAA, you have a right to your medical records, and billing documentation falls under that umbrella. I've submitted formal requests multiple times, and the response time is usually two to three business days. It's a bit bureaucratic, but it works.
Get the Full Details

Submitting the Claim Yourself
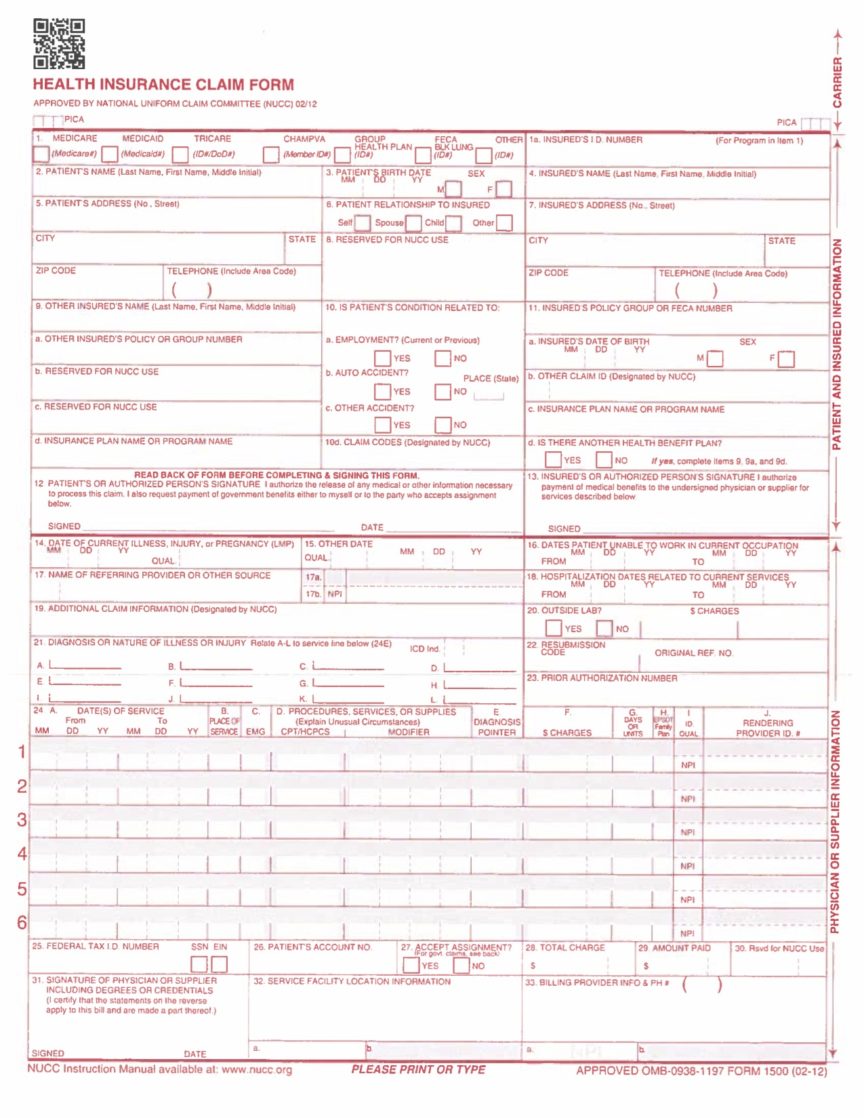
Most insurance companies have an online portal where you can upload receipts and track claim status. Some still require paper forms, which means printing out their claim form, attaching your superbill, and mailing it. This step alone adds about a week to whatever timeline you were expecting. I'd estimate the whole process from submission to reimbursement check takes between three and six weeks depending on your insurer. Several carriers offer mobile apps now where you can snap a photo of your receipt and submit directly. This cuts the administrative time considerably, though you still wait the same processing period on the backend. UnitedHealthcare, Aetna, and Cigna all have functional portals, but each has its own quirks. United requires you to select the correct place of service code, and getting that wrong will bounce your claim back. Aetna's portal sometimes fails to recognize certain therapist credentials unless you manually enter the provider information. These are the small frustrations that make the process feel longer than it should. There's also the option of having your therapist submit the claim directly to your insurance company on your behalf. Some practices offer this as a service, though many don't. If yours does, it removes one step from the equation, but you're still paying out of pocket until the reimbursement hits. The advantage is that professional submitters tend to catch coding errors before the claim goes out, which reduces the chance of denial on technical grounds.
Common Pitfalls and What to Watch For
The biggest mistake people make is assuming their plan covers therapy at the same rate as in-network medical care. Some plans — particularly HMOs — have strict network requirements that mean you'll get zero reimbursement if you see an out-of-network provider. Others, like many PPO plans, offer partial out-of-network benefits, but at a significantly reduced rate. Check your summary of benefits document. The section labeled "out-of-network mental health" is where the answer lives, though it's often buried in dense policy language. Another trap is the annual session limit. Some plans cap the number of therapy sessions they'll reimburse per year, even if your therapist recommends more. I once worked with a client who had a 20-session annual limit on her plan. Her therapist needed her to continue past that point due to trauma work, and there was no straightforward appeal path available. The limitation was contractual, not medical, which meant the insurance company had no obligation to budge. That's a structural problem, not a procedural one, and it affects more people than you'd expect. Pre-authorization is another area where things go sideways. A handful of plans require approval before treatment begins, especially for out-of-network providers. Skipping this step means your claims get denied retroactively, and you're stuck covering costs that should have been covered. Always confirm pre-auth requirements before your first session, not after you've paid out of pocket.
When Reimbursement Doesn't Make Sense
Let me be straightforward about when this whole process falls apart. If your insurance has a high deductible and low out-of-network benefits, the math might not work in your favor. A single therapy session at $150 might get you back $80 to $100 after all the calculations, and the administrative effort of tracking receipts, submitting claims, and following up on denied claims could easily consume more time than the actual reimbursement is worth. In those cases, switching to an in-network provider, even if it means a shorter list of options, usually saves you more than you'd gain from the reimbursement chase. There's also the tax angle. Reimbursements from insurance for medical expenses are generally not taxable income, but if you're using a flexible spending account or health savings account to pay for therapy, that changes the picture slightly. FSA and HSA funds are pre-tax dollars, so using those for therapy is often more efficient than pursuing reimbursement, particularly if your plan doesn't offer favorable out-of-network rates. Some people find that the Mental Health Parity and Addiction Equity Act works in their favor here, requiring insurers to treat mental health benefits comparably to medical and surgical benefits. This is enforceable law, but invoking it means filing a complaint with your state's insurance department, which is a longer path than most people want to take. Still, it's worth knowing about if you're being systematically denied coverage that comparable medical treatments would receive.
The whole process isn't impossible, and for people with solid out-of-network benefits, it can meaningfully reduce the cost of therapy. But it requires patience, documentation discipline, and a willingness to navigate insurance bureaucracy that most people never anticipated dealing with. Before you commit to the reimbursement route, pull your policy documents, read the out-of-network section carefully, and do the math on what you'd realistically get back versus what you'd save by simply going in-network.