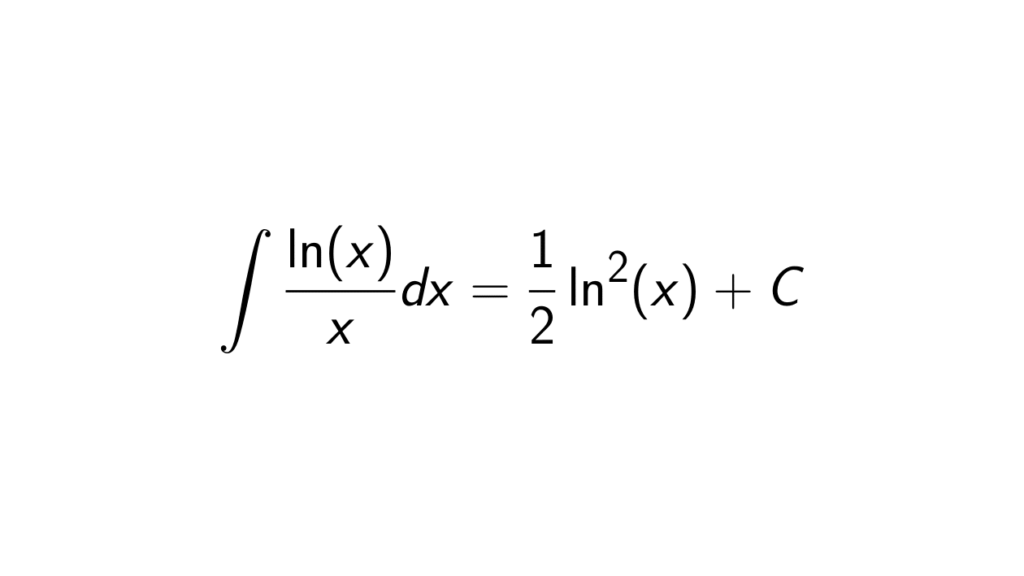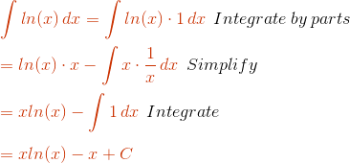
Integration By Parts For Logarithms
The most straightforward way to handle the Integral Of Ln X is to recognize that there is no quotient rule for integration the way there is for differentiation. You are multiplying ln(x) by 1, so integration by parts is the tool. Set u equal to ln(x) and dv equal to dx. That gives you du as 1/x dx and v as x. When you apply the formula uv minus integral of v du, the x terms cancel in the remaining integral and you are left with x times ln(x) minus x plus C. It takes about two minutes on paper if you have done this a few times. The reason this works cleanly is because the derivative of ln(x) is algebraic. That is the whole point of choosing it as u. If you flip them and make dv equal to ln(x) dx, you end up going in circles. I see this mistake constantly in early calculus submissions. The rule of thumb LIATE still applies here: logarithms come before algebraic terms when deciding what becomes u.
Integral Of Ln X derivation and result
Starting from u equals ln(x), dv equals dx, du equals dx over x, and v equals x, the application goes like this: x times ln(x) minus the integral of x divided by x dx. The x over x simplifies to 1. The integral of 1 is just x. Add the constant of integration and you have x times ln(x) minus x plus C. Factor out the x if you want the answer as x times the quantity ln(x) minus 1 plus C. Both forms are correct. Definite integrals follow the same antiderivative but you evaluate at the bounds. The natural domain restricts x to positive values, so any integral starting at 0 is technically improper. You have to take a limit as the lower bound approaches 0 from the right. That limit of x times ln(x) minus x as x approaches 0 from the positive side is negative 1. I ran into this exact scenario last year when I was setting up a normalization integral for a probability distribution that involved ln(x) weighted by a polynomial. The boundary term at 0 contributed a finite value, and forgetting to evaluate it as a limit instead of just plugging in 0 would have given the wrong answer by exactly 1. What trips people up is assuming that ln(0) appearing in the expression means the whole thing diverges. It does not. The product x times ln(x) goes to 0, not to infinity. You can show that with L'Hopital's rule applied to ln(x) over 1/x, which turns it into a ratio of 1 over x and negative 1 over x squared. That simplifies to negative x, which clearly goes to 0 as x approaches 0. So the boundary contribution is finite and well-defined even though the integrand itself blows up at 0.
There is a practical shortcut worth knowing. If you need the integral of ln(ax) where a is a nonzero constant, you do not need to redo the whole derivation. The result is x times ln(ax) minus x plus C. The constant a disappears into the integration constant because x times ln(a) is just another linear term that gets absorbed. I use this regularly when working with scaling factors in engineering calculations and it saves about thirty seconds per problem. A more useful extension is the integral of ln(x) squared. That requires applying integration by parts twice. Set u equal to ln(x) squared and dv equal to dx. After the first pass you get x times ln(x) squared minus 2 times the integral of ln(x) dx. The remaining integral is the one we already solved. The final answer is x times ln(x) squared minus 2x times ln(x) plus 2x plus C. This pattern generalizes to higher powers of ln(x), though the algebra gets tedious past the third power. For fourth or fifth powers, I usually switch to a tabular integration setup to keep track of the signs without writing everything out. Not every logarithmic integral has a closed form. The integral of ln(ln(x)) dx cannot be expressed with elementary functions. It requires the logarithmic integral function li(x), which is defined as a definite integral itself and is typically evaluated numerically or looked up in tables. If your problem involves ln(ln(x)), you are likely working in analytic number theory or asymptotic analysis, and symbolic integration will not help you. Numerical quadrature is the only realistic path.
Get the Full Details

Another case where the standard method breaks down is when ln(x) appears inside a rational function or multiplied by an exponential. The integral of ln(x) over x squared, for example, still uses integration by parts but the resulting integral is not simpler. You have to apply parts again and check whether the loop terminates. In some configurations it does not terminate within a reasonable number of steps, and you end up with an infinite series representation instead of a closed form. That usually means you should switch to numerical evaluation unless the series converges fast enough for your accuracy requirements. When doing this by hand under exam conditions, the most common error is dropping the constant of integration or forgetting to change the sign in front of the remaining integral. Another frequent mistake is writing the answer as x times ln(x) plus C and stopping there. The minus x term is essential. Without it, differentiating your answer back does not return the original integrand. You can always verify your work by taking the derivative of x times ln(x) minus x. The product rule gives ln(x) plus 1 minus 1, which simplifies back to ln(x). If your derivative does not simplify cleanly to ln(x), you made an algebra error somewhere. For definite integrals over intervals that include 1, the antiderivative evaluates cleanly because ln(1) is 0. Over intervals starting below 1, you have to be careful with the sign. ln(x) is negative between 0 and 1, so the area accumulated in that region is negative. The antiderivative handles this correctly on its own, but visual confirmation helps catch sign errors before you submit work.
If you are programming this into a calculator or a script, define the antiderivative as a separate function and evaluate it at the upper and lower bounds. Do not try to approximate the integral numerically with a Riemann sum near 0. The function is unbounded there, and standard numerical methods will give poor results unless you use adaptive quadrature or transform the variable. A simple substitution like t equals ln(x) can sometimes convert the problematic region into a more manageable form, but that introduces its own complexity. For most practical purposes, using the closed-form antiderivative is faster and more accurate than any numerical approximation.