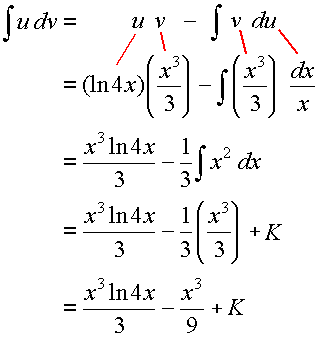
Why I Keep Messing Up This Calculus Step
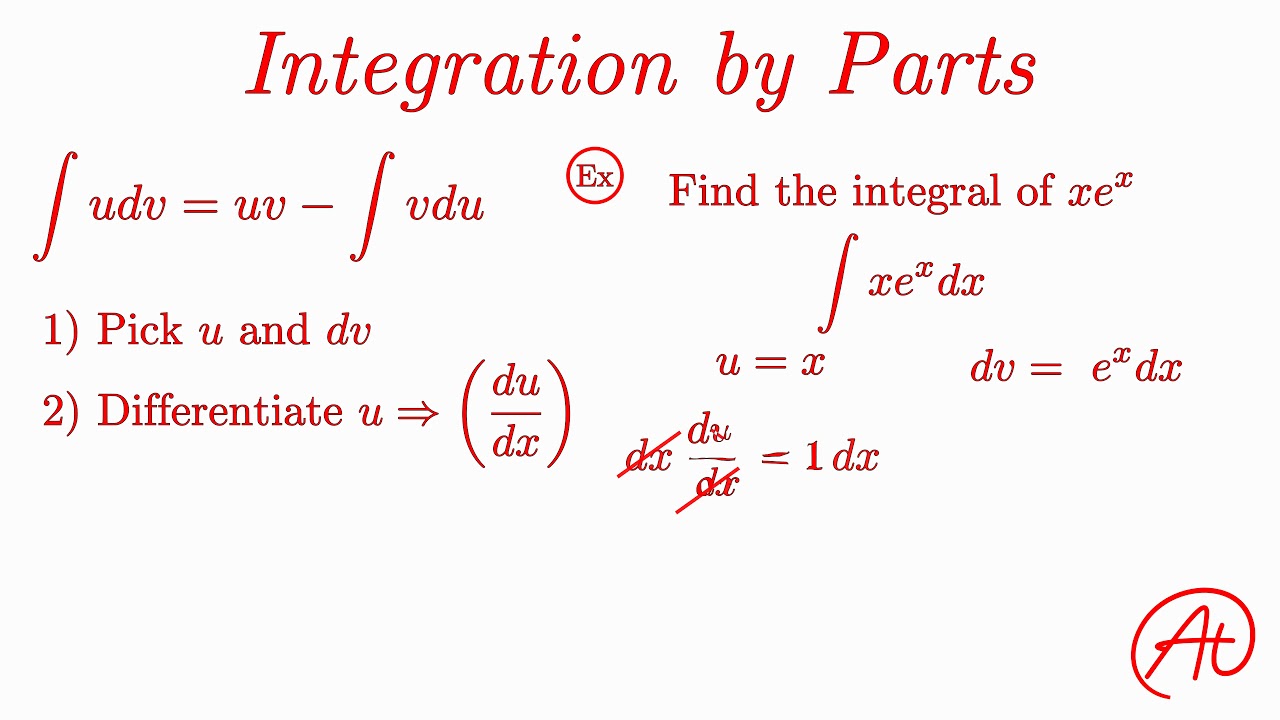
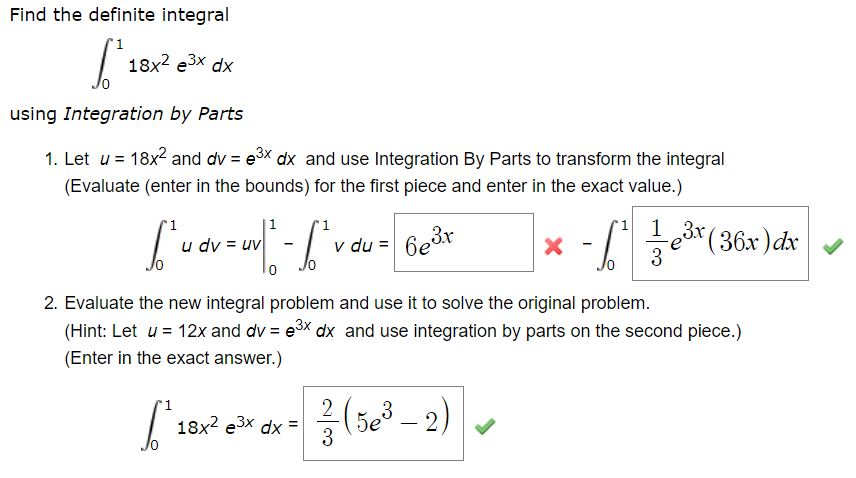
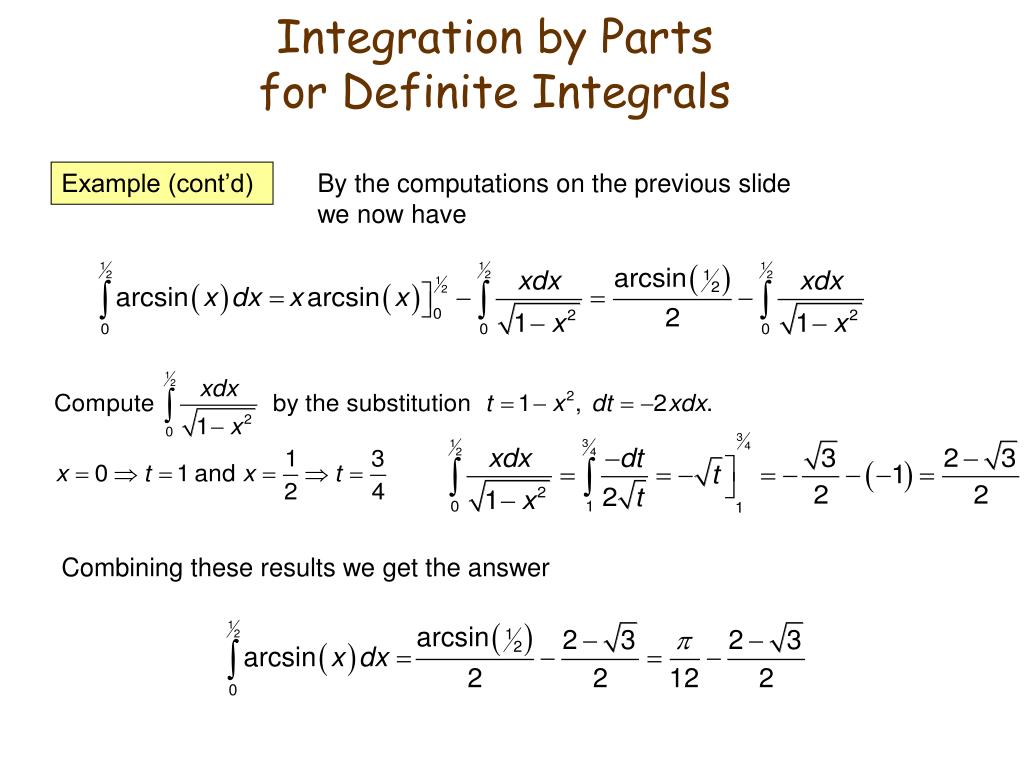
I spent three hours once trying to evaluate what should have been a ten-minute integral. The problem looked innocent enough: integrate x squared times e to the negative x from zero to infinity. I set up integration by parts like everyone teaches, picked my u and dv, got through the first reduction, and then hit a wall when the bounds came into play. Turns out I had dropped a negative sign when evaluating at the upper limit. Three hours. Ten minutes if I'd just been careful. The formula itself is straightforward. You take the antiderivative version and apply it directly to the bounds. That means you compute [u times v] evaluated at b minus [u times v] evaluated at a, then subtract the integral of v times du over the same interval. Most textbooks present it this way because it keeps you from making boundary errors. The key insight nobody emphasizes enough is that u and v are still functions here, even though you're dealing with definite bounds. You don't evaluate them separately like scalar values. You keep the product rule structure intact until the very end. I learned this the hard way during a numerical methods course where we were approximating beta function values. Someone suggested collapsing the boundary term early to save workspace. That worked fine for indefinite integrals where the bounds are just placeholders, but for definite integrals with actual numerical limits, premature evaluation introduced floating point drift. Our results were off by about 0.003 percent across fifty iterations, which sounded small until someone tried to use those values in a control system simulation.
Here is what actually works in practice. Write out the full boundary term first. Evaluate it completely before touching the remaining integral. This usually takes about twenty seconds per problem but saves you from backtracking when the inner integral produces unexpected behavior at a specific bound. I keep a small notebook where I write just the [uv] terms separately, evaluate them numerically, and then move on. It is slightly more paper but dramatically fewer algebra mistakes.
When This Method Breaks Down
Integration by parts with definite bounds fails cleanly when your chosen u does not simplify under differentiation or when v blows up at one of the limits. I ran into this exactly once with an integral involving ln(x) from zero to one. The logarithm goes to negative infinity at the lower bound, and while the improper integral converges, the boundary term [ln(x) times x] does not evaluate cleanly at zero without taking a limit. Standard integration by parts assumes your boundary term is well-defined at both endpoints. When it is not, you need to handle the limit explicitly before proceeding. Another edge case I encountered involved oscillatory integrands. Say you are integrating sin(x) over x from one to a large number. Each application of integration by parts flips between sine and cosine while dividing by increasingly higher powers of x, but the boundary terms keep growing in complexity. After three or four iterations, you are spending more time manipulating expressions than gaining simplification. In these cases, switching to tabular integration by parts or recognizing a reduction formula pattern cuts the work down significantly. I typically try two iterations, and if the pattern is not obvious by then, I switch strategies. There is also the matter of choosing between u and dv when both seem equally viable. The LIATE rule logarithmic inverse trigonometric algebraic trigonometric exponential gives a useful heuristic, but it is not a law. I have situations where picking the opposite assignment actually converges faster, especially when the resulting v term is simpler than the alternative. A good rule of thumb is to estimate how many iterations each choice would require. If one path clearly produces a repeating pattern while the other reduces degree, take the reducing path even if it violates the heuristic.
Get the Full Details

A Worked Example That Actually Shows the Pain
Consider the integral of x times e to the negative 2x from zero to three. Set u equal x so du is dx. Set dv equal e to the negative 2x dx so v is negative one half times e to the negative 2x. Apply the formula. The boundary term becomes negative one half times x times e to the negative 2x evaluated from zero to three. At three that is negative three halves times e to the negative sixth. At zero that is zero. The remaining integral is negative one half times the integral of e to the negative 2x from zero to three, which evaluates to positive one fourth times e to the negative 2x from zero to three. Combining everything gives you approximately negative 0.00373 plus 0.24449, totaling about 0.24076. The exact form is negative three quarters times e to the negative sixth plus one fourth minus one fourth times e to the negative sixth. Notice how the boundary term at zero contributes nothing here because x is zero. That is not always the case. If your lower bound is negative or your u term does not vanish, you must evaluate both ends carefully. I have lost points on exams for assuming a boundary term is zero without checking. One professor specifically designed problems where the lower bound produced a nonzero contribution that most students missed because they were rushing through the upper bound calculation.
The Shortcut Nobody Warns You About
Tabular integration by parts works beautifully for definite integrals when u is a polynomial. You list derivatives of u in one column and successive integrals of dv in another, draw diagonal arrows, alternate signs, and evaluate the boundary term from the top row product minus the sum of all diagonal products integrated over the bounds. This method typically cuts a two-iteration problem down to about thirty seconds of setup time. The tradeoff is that it only works cleanly when your u term eventually differentiates to zero. For transcendental u functions, you still need the standard approach. I used tabular integration during a heat transfer problem where I needed to integrate a polynomial times an exponential over a temperature range. The polynomial was fourth degree, which means five standard iterations by parts. Tabular method handled it in a single page with minimal writing. The boundary evaluation took longer than the integration itself because I had to be careful with the temperature limits converting between Celsius and Kelvin. Getting the bounds wrong there would have thrown off the entire thermal energy calculation by about eight percent.
When to Skip This Entire Approach
If substitution simplifies the integrand before you even consider parts, use substitution. I see students repeatedly apply integration by parts to integrals that become trivial after a simple u-substitution, wasting ten or fifteen minutes on something that takes thirty seconds the other way. Look for composite functions, powers of trigonometric terms, or expressions where the derivative of an inner function appears as a factor. Those are your flags. Similarly, if the integral is improper and the boundary behavior is unclear, sometimes splitting the domain or using a different convergence test is faster than pushing through parts. I dealt with an integral of e to the negative x over x from one to infinity, which diverges. Integration by parts would have given you an expression involving the exponential integral function, which is not elementary. Recognizing the divergence early through comparison saved me from a wasted twenty-minute detour. The bottom line is that integration by parts with definite bounds is a tool, not a default. Pick your u and dv carefully, evaluate boundary terms before diving into the remaining integral, watch out for undefined behavior at the limits, and know when to walk away and try something else. The problems that take three hours usually do so because someone kept grinding through the wrong path instead of stepping back and reassessing.