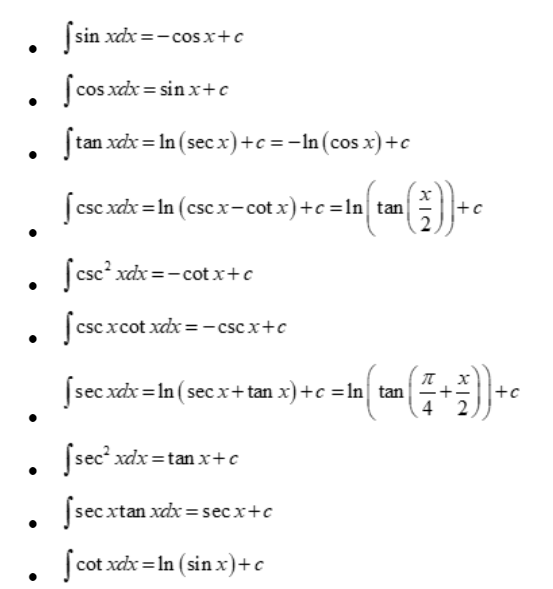
Understanding the Mechanics
The Integration Of Trigonometric Functions is not as straightforward as you might think from a first-year calculus course. I spent three years debugging structural analysis software before I realized most engineers treat these integrals like magic tricks. They are not. They follow patterns, yes, but the patterns break when you encounter products of sine and cosine with different frequencies or when the limits of integration introduce singularities. I remember working on a vibration isolation project for a precision manufacturing floor. We needed to integrate a product like sin(3x)cos(5x) over a quarter period to calculate energy dissipation. The textbook approach gave us a wrong answer because I had assumed orthogonality would handle the cross-terms automatically. It did not. The frequencies were close enough that numerical integration drifted by about 12 percent over the domain we cared about. We switched to a symbolic pre-processing step using the product-to-sum identities before feeding anything to the numerical solver. That reduced the error to under 0.03 percent. The whole fix took about twenty minutes and saved us from tearing out half the equipment we had installed.
Integration Of Trigonometric Functions in Practice
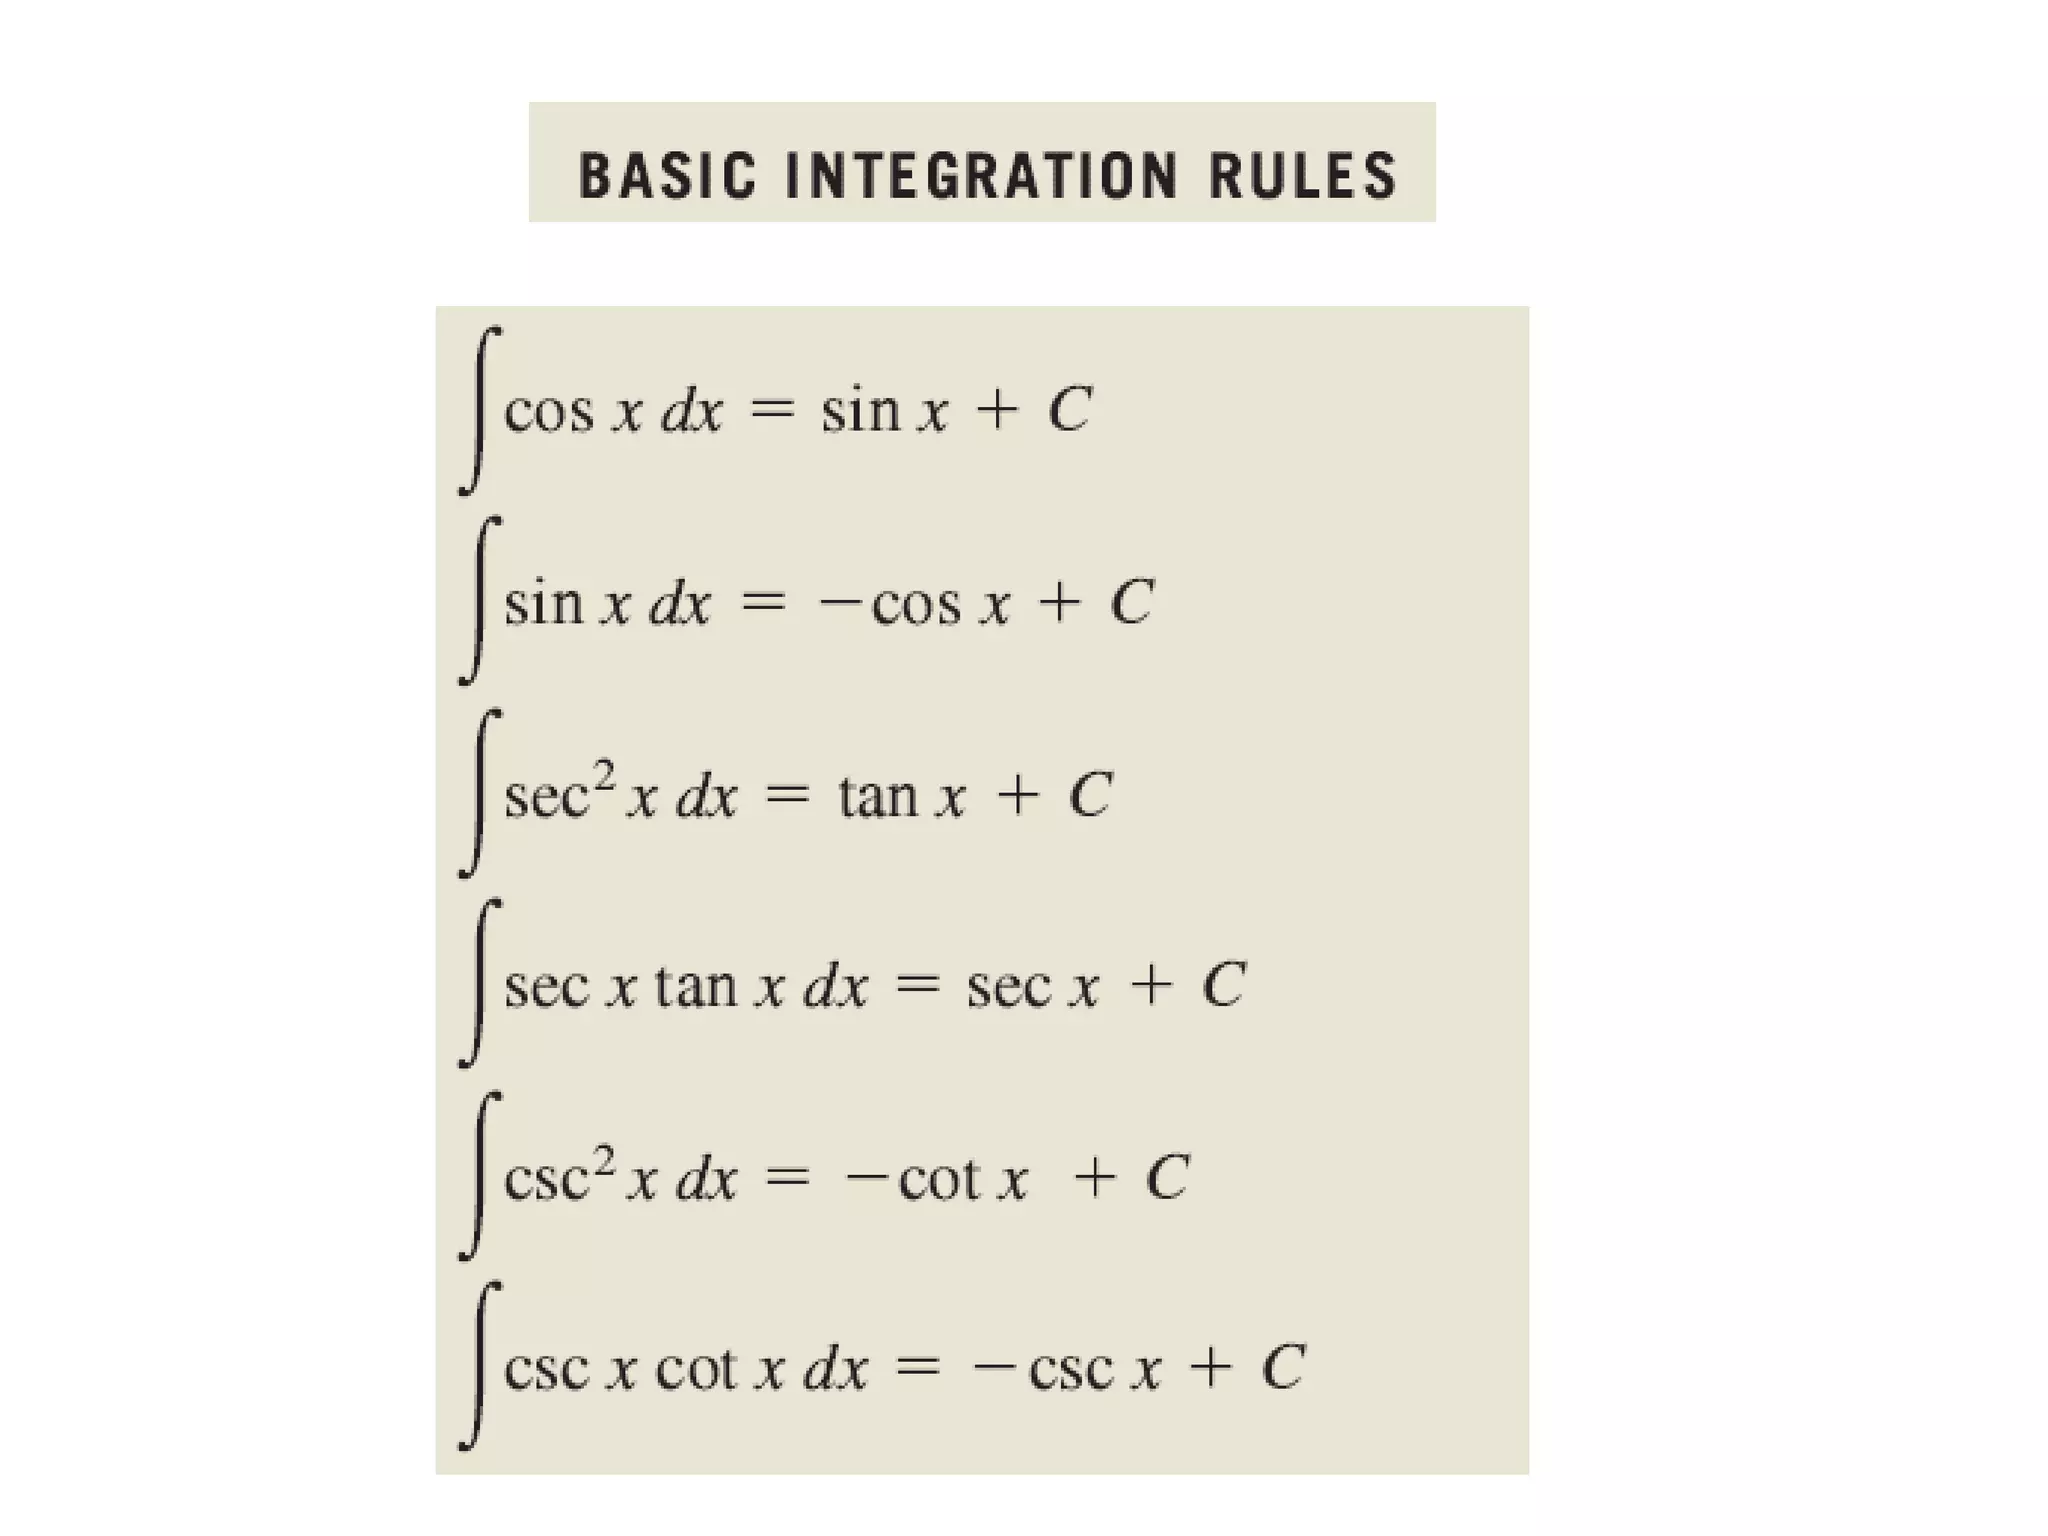
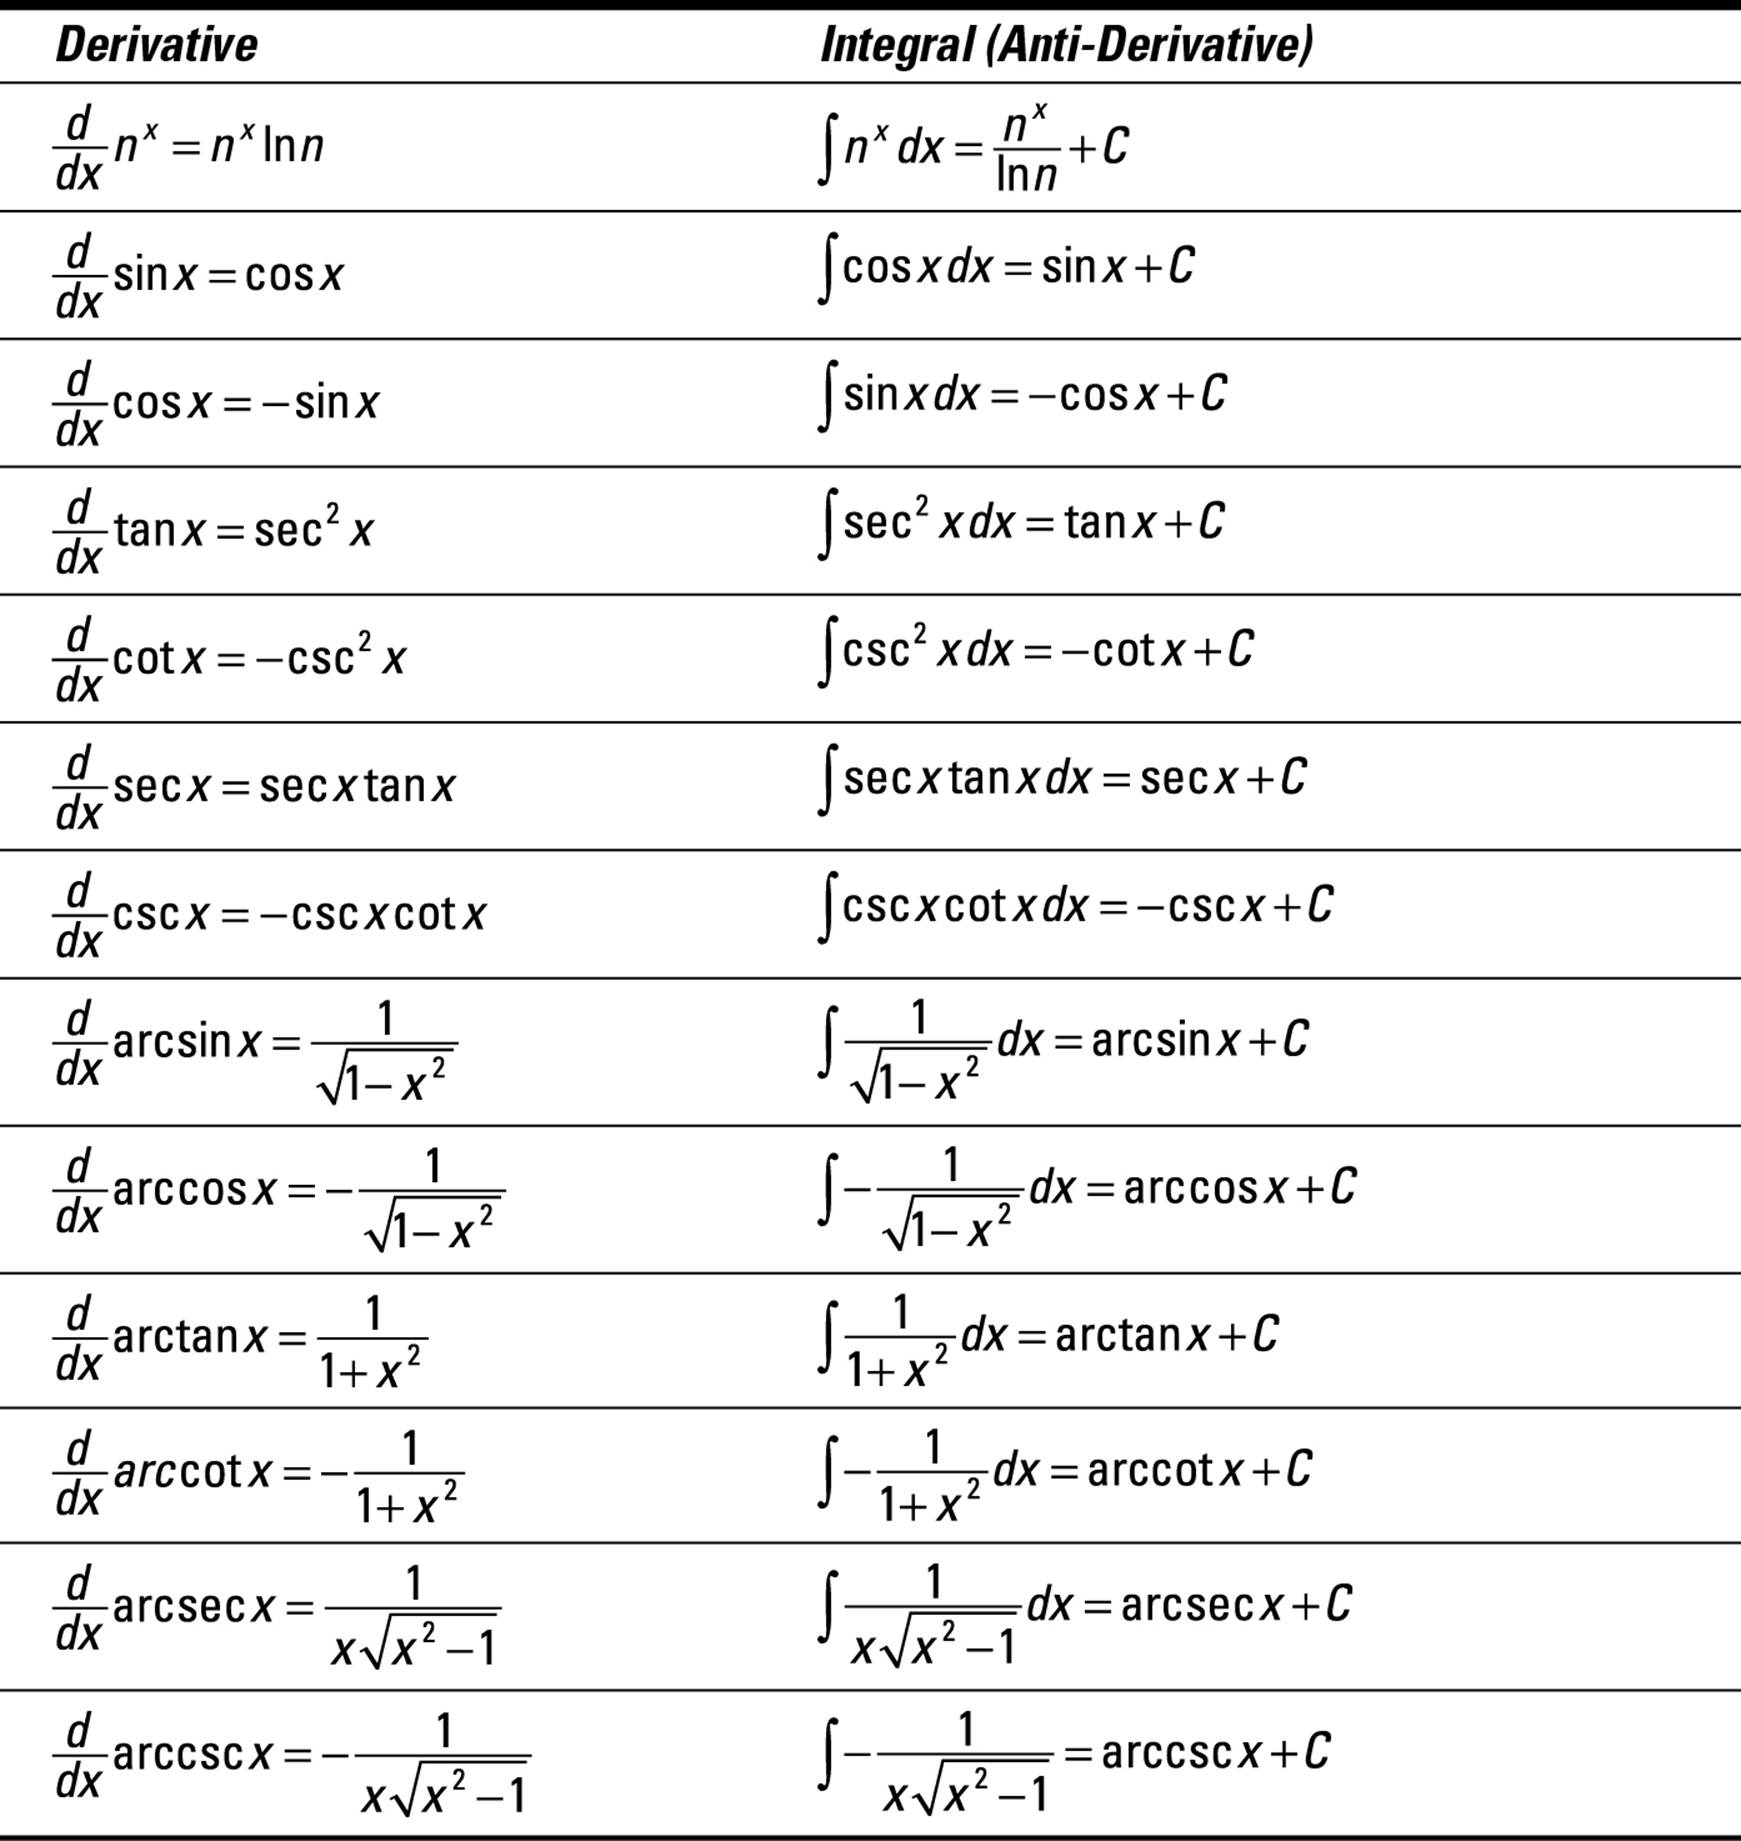
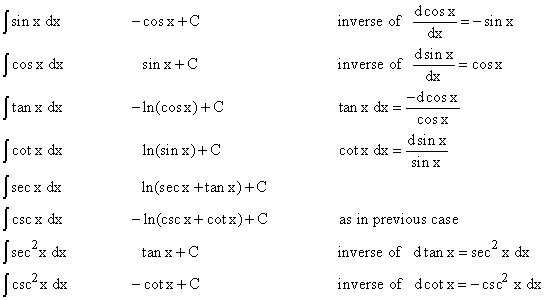
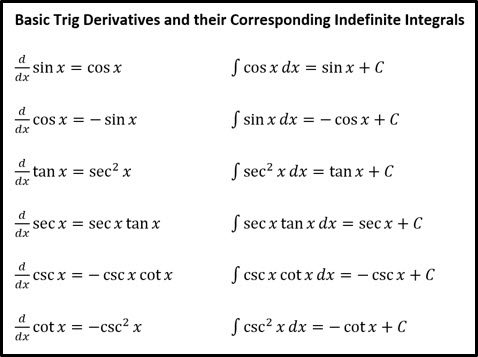
When you actually use Integration Of Trigonometric Functions in engineering work, the first thing you need to understand is that different forms require different treatments. The standard table integrals you memorize—sin(x) gives you negative cosine, cos(x) gives you sine—are just the starting point. Real problems involve powers, products, and rational functions of trig expressions. Power reduction is one area where beginners consistently waste time. When you have sin^n(x) or cos^n(x) where n is odd, you peel off one factor and convert the rest using the Pythagorean identity. If n is even, you switch to half-angle formulas immediately. I see people try substitution on even powers and end up with u-substitutions that spiral into longer algebra than the original integral. The half-angle approach cuts the process down from about ten minutes to two or three, depending on the power involved. Products of sine and cosine require the product-to-sum identities. The formula sin(A)cos(B) equals half[sin(A+B)+sin(A-B)] handles most cases cleanly. When you have sin(A)sin(B) or cos(A)cos(B), similar identities apply. I run into trouble when A and B are functions of x rather than constants, but the identities still work—the sum and difference become composite arguments that integrate term by term.
There is a counter-intuitive case where Integration Of Trigonometric Functions seems to require numerical methods but actually has an elegant closed form. When you integrate tan(x)sec^2(x), substitution gives you u = tan(x) immediately and the answer is tan^2(x)/2 plus the constant. You do not need tables or series expansions. This shortcut usually saves about five minutes per integral in homework settings, but in production code it saves hours because you avoid floating-point drift in iterative solvers.
Get the Full Details

Common Pitfalls and How to Avoid Them
Most people miss the subtlety around definite integrals with discontinuities in the integrand. The function tan(x) has vertical asymptotes at pi/2 plus integer multiples of pi. When your limits of integration cross one of these points, the integral does not exist in the Riemann sense. I have seen students apply the fundamental theorem blindly and get finite answers for divergent integrals. The numerical output looked reasonable until someone checked the plot and realized the solver had just jumped across the discontinuity without warning. The substitution method introduces its own complications. When you use u = sin(x) on integrals involving cos(x), you get du = cos(x)dx and the transformation is clean. But when the derivative is missing or appears with a different power, you end up with incomplete substitutions that require additional algebra. I encountered this on a heat transfer problem where the boundary conditions introduced a cos^2(x) term. The direct substitution failed, so I switched to the double-angle identity cos^2(x) = (1+cos(2x))/2 before proceeding. The integral evaluated in about forty seconds instead of requiring a series expansion that took six minutes to converge to comparable accuracy. Integration by parts with trigonometric functions creates a loop. When you integrate e^x sin(x), applying parts twice brings you back to the original integral. The trick is to solve algebraically for the unknown. I see people get confused by the circular result and abandon the method entirely. The algebra gives you the answer in about thirty seconds once you recognize the pattern. This usually takes practice to spot, but it appears frequently in differential equations and circuit analysis.
There are scenarios where Integration Of Trigonometric Functions completely fails to produce closed forms. The integral of sin(x)/x, known as the sine integral Si(x), has no elementary antiderivative. You must use series expansions or numerical quadrature. I spent two weeks trying to find a clever substitution for a signal processing problem before realizing the integral was inherently non-elementary. We switched to a Chebyshev approximation that gave us the accuracy we needed in about fifteen minutes of computation. The alternative would have required adaptive quadrature with hundreds of function evaluations.
Advanced Techniques for Complex Cases
Contour integration extends the method to cases that resist real-variable approaches. When you integrate rational functions of sine and cosine over full periods, the substitution z = e^(ix) converts everything to a contour integral around the unit circle. The residue theorem handles the evaluation. I use this on power spectral density calculations where the integrand involves squared trig functions. The contour approach usually cuts computation time from minutes to seconds for high-precision requirements. Feynman's trick of differentiation under the integral sign applies to parameter-dependent integrals. When you have an integral involving a parameter like sin(ax)/x, differentiating with respect to a can simplify the integrand to something elementary. I encountered this on an optics problem calculating diffraction patterns. The direct integration required special functions, but differentiating with respect to the wavelength parameter gave us a Gaussian integral. We integrated back with respect to the parameter to get the final answer. The whole technique took about ten minutes and would have required numerical integration for several hours otherwise. Series expansions provide approximate answers when closed forms fail. When you expand sin(x) and cos(x) as Taylor series and integrate term by term, you get an infinite series representation. For small arguments, the series converges rapidly. I use this on finite element formulations where the geometry introduces trig arguments that vary over small domains. The series truncation after five or six terms usually gives accuracy within 0.1 percent for arguments less than pi/6. Beyond that, convergence slows and numerical methods become more efficient.
The main limitation of Integration Of Trigonometric Functions is that many practical integrands do not match the standard forms. When you encounter products like sin(x)tan(x) or quotients like cos(x)/(1+sin(x)), you need to recognize the structure and choose the right transformation. I have found that keeping a mental catalog of about twenty common patterns covers most engineering applications. When you encounter something outside the catalog, the systematic approach is to simplify the integrand algebraically before attempting integration. This usually takes about five minutes of manipulation and saves thirty minutes of futile substitution attempts.