What You Actually Need To Know About How The Economy Works
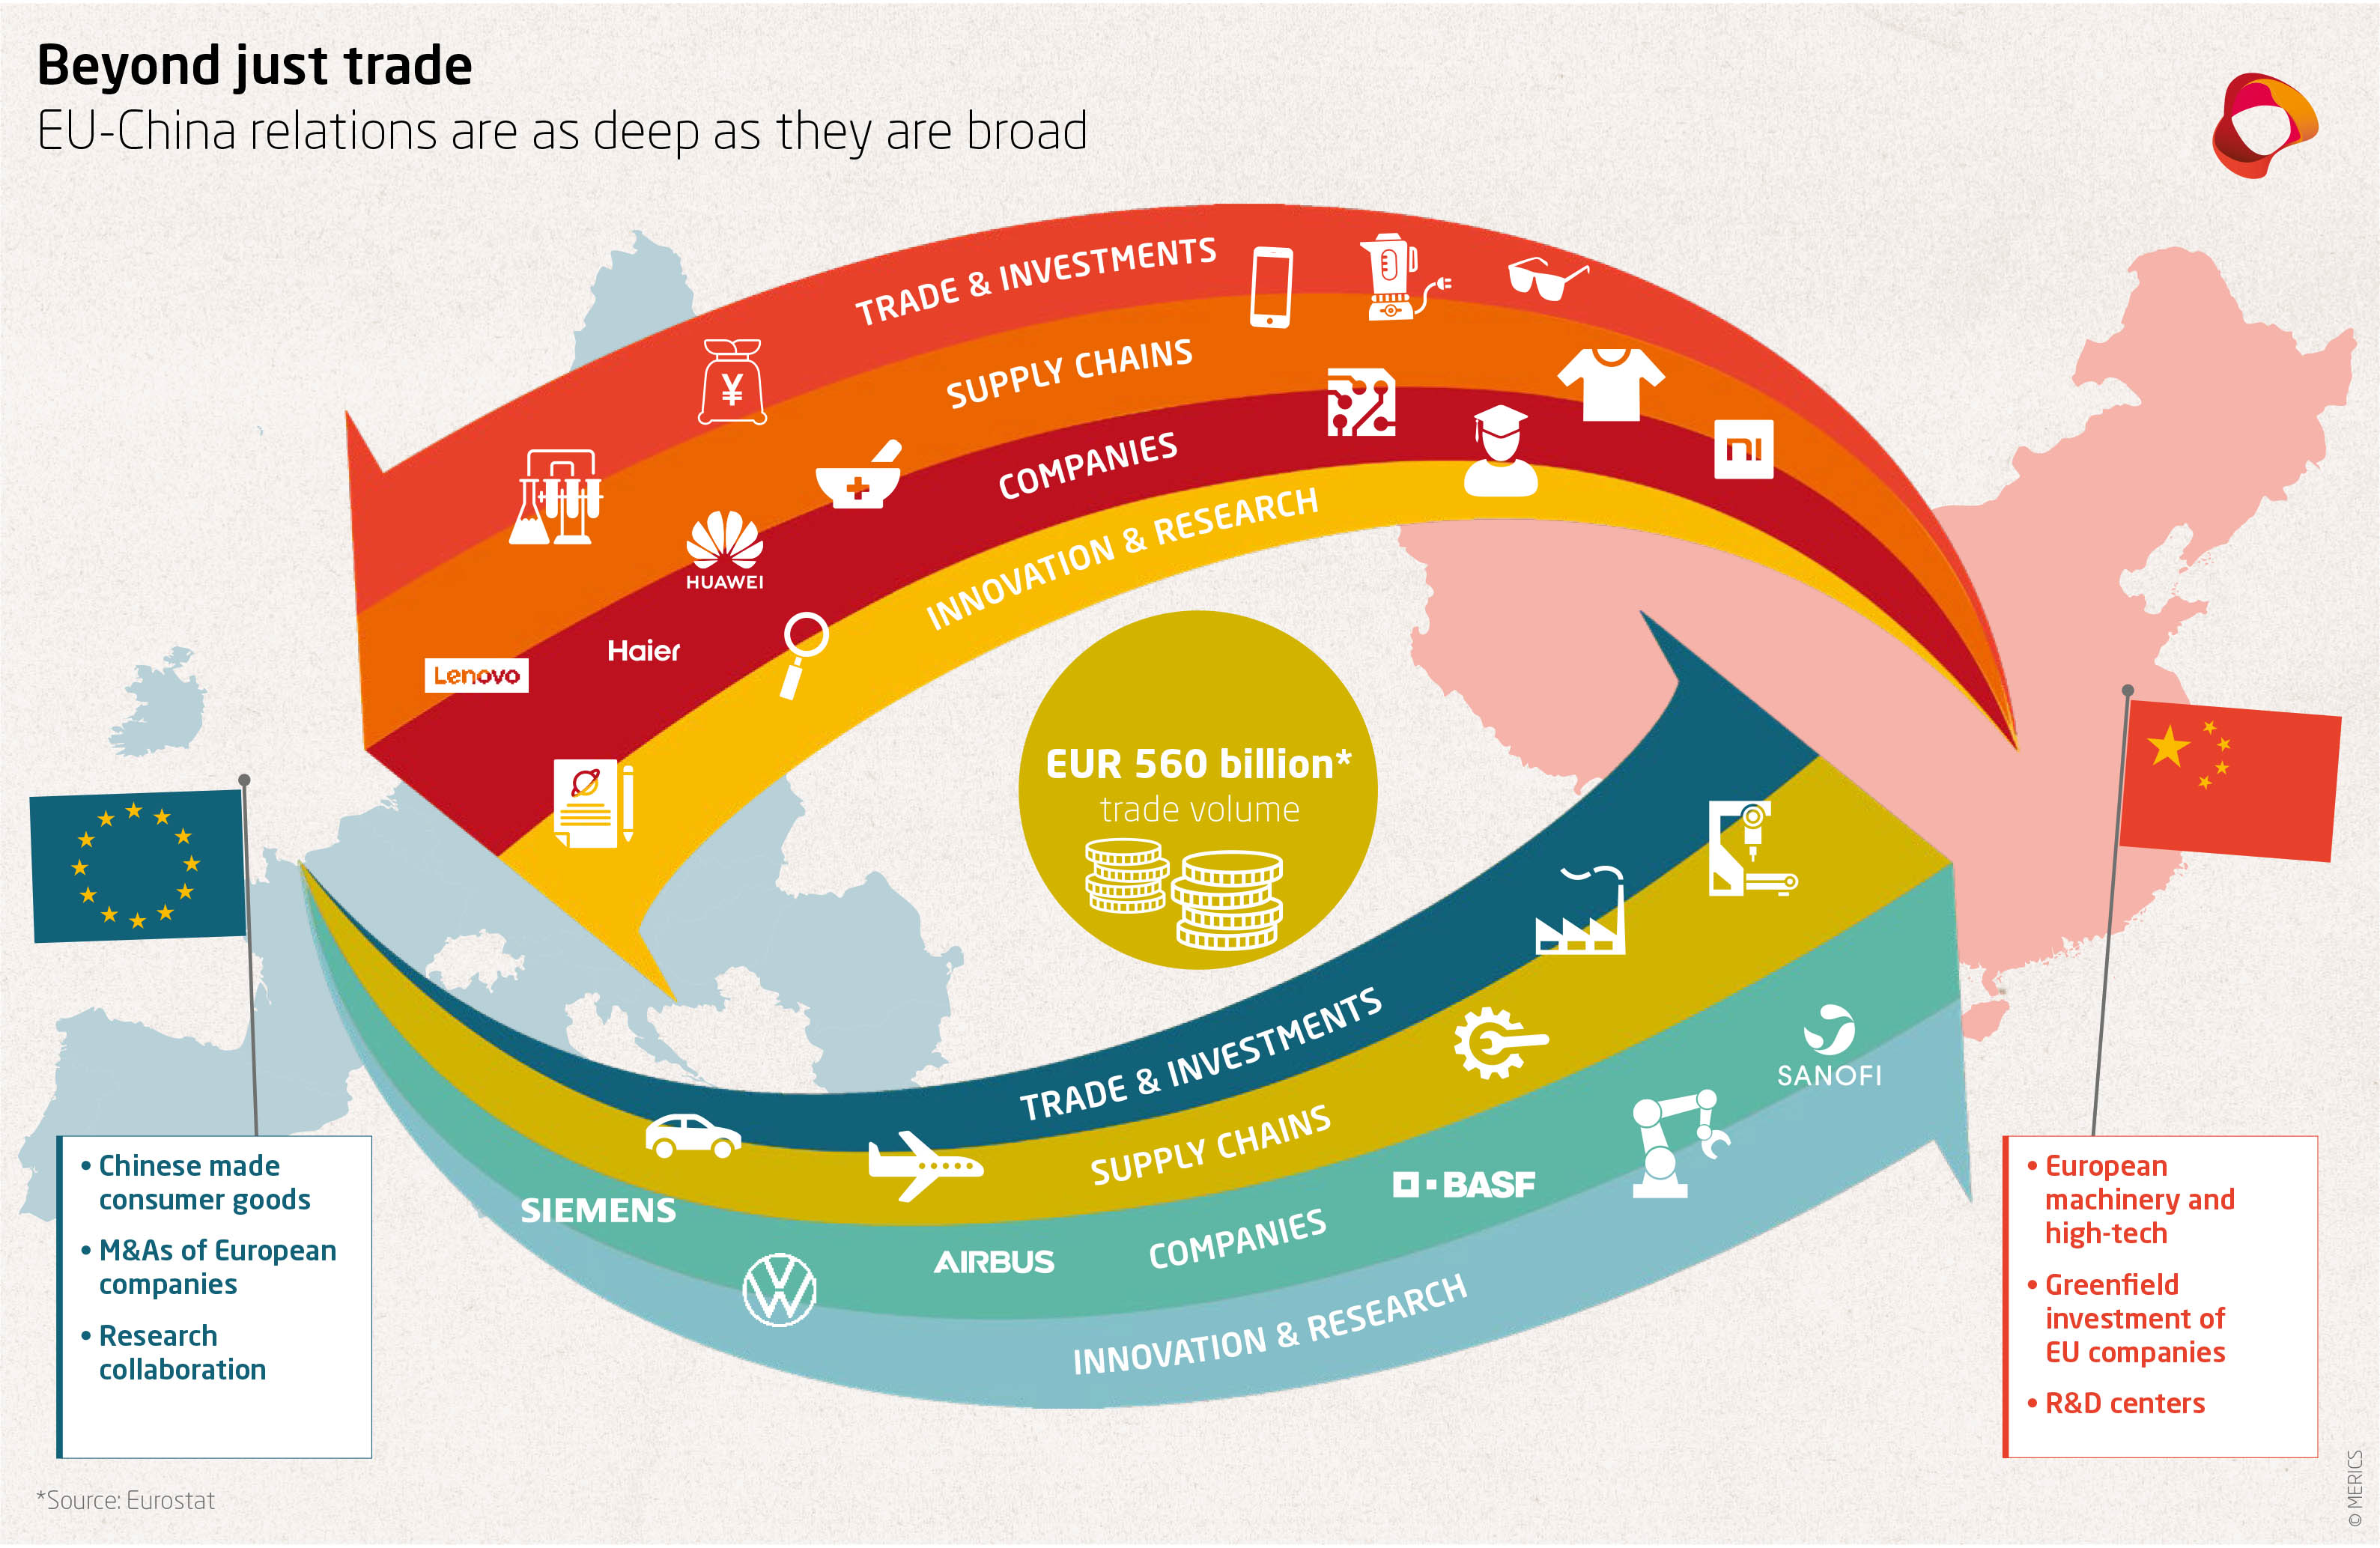
You probably learned in high school econ that everything is connected, but that's basically it. The actual mechanics of Interdependence In The Economy are where things get messy and most people gloss over them. I've spent years working in supply chain logistics and macro forecasting, and the difference between understanding this concept on paper and seeing it play out in real time is massive. Let me walk you through what actually matters here. At its core, interdependence means no single sector, company, or country operates in isolation. When something shifts in one area, it ripples through others in ways that are rarely linear. A drought in Brazil affects coffee prices in Seattle, which affects consumer spending patterns, which affects retail hiring. But the real insight most people miss is that these feedback loops can amplify or dampen each other unpredictably. That's why simple linear models fail so often. I once worked on a project modeling the impact of a tariff on steel imports. The textbook answer suggested domestic steel producers would benefit, unemployment in that sector would drop, and related industries would see cost increases but manageable ones. What actually happened was the opposite in several areas. Aluminum substitution spiked, which depressed aluminum mining jobs more than steel losses created gains. Construction firms delayed projects, which cascaded into fewer orders for glass, lumber, and appliances. The net effect was slightly negative across multiple unrelated sectors. Models didn't predict any of that well. The main reason input-output tables were too coarse to capture substitution effects at the granularity we needed.
The workaround was to layer in industry-specific elasticity data and run a computable general equilibrium model instead of a static input-output framework. It took about three weeks longer than a standard analysis but produced results that actually matched what we observed two quarters later. If you're doing this kind of work, don't skip that step.
How To Map Economic Interdependence In Practice
Start by identifying the key nodes in the system you're studying. These could be countries, industries, or even specific supply chain segments. Then map the transactions between them using available trade data, industry reports, or financial statements. The Bureau of Economic Analysis in the US publishes detailed input-output tables every year. Internationally, the OECD and World Bank maintain comparable datasets. The challenge isn't getting the data. It's knowing which relationships matter and which are noise. Here's a practical approach that usually works: pick one shock scenario and trace its propagation. A fuel price increase, a currency devaluation, a demand spike in one product category. Follow the cost changes upstream and downstream. Track which sectors absorb costs, which pass them on, and which lose volume. The sectors that both receive from and supply to many others are your systemic risk points. They'll amplify shocks rather than dampen them. One thing that trips people up constantly is assuming symmetry in these relationships. If sector A depends on sector B, it doesn't mean sector B depends on sector A to the same degree. In my experience, asymmetry is the rule, not the exception. A microchip shortage cripples automotive production, but a crash in car sales doesn't immediately devastate semiconductor fabs. The response times and scale differ significantly. Accounting for that lag and magnitude gap is critical or your projections will be off by a wide margin.
Get the Full Details
Common Tools And Where They Fall Short
Input-output analysis is the standard tool, developed originally by Wassily Leontief. It's useful for showing direct and indirect effects within a fixed-technology framework. The limitation is that it assumes constant returns to scale and no substitution between inputs. Real economies adjust. Firms switch suppliers, consumers switch products, governments adjust policy. Static IO tables capture none of that dynamic behavior. Computable general equilibrium models address some of those gaps but require far more data and computing power. They're also sensitive to calibration choices, which means two analysts running the same CGE model can produce meaningfully different results depending on their parameter assumptions. I've seen discrepancies of 20 to 40 percent in GDP impact estimates between otherwise sound CGE specifications. That's not a trivial range. If you need a quicker heuristic, the network centrality approach is worth considering. Treat sectors or countries as nodes and trade flows as edges. Calculate betweenness centrality to find the connectors, and degree centrality to find the highly connected players. This won't give you dollar-value impact estimates, but it will tell you which nodes are structurally positioned to spread shocks. It's fast, requires less data, and the results are surprisingly robust across different datasets. I use it as a first pass before committing to a full model.
Edge Cases That Break Standard Analysis
Financial intermediation is one area where interdependence gets complicated fast. Banks don't just lend money. They create liquidity networks that make interdependence harder to trace. When a major bank faces distress, the contagion doesn't flow through trade relationships alone. It flows through interbank lending, derivative contracts, and asset fire sales. The 2008 crisis was a textbook example, but even smaller banking disruptions follow similar patterns that standard trade models completely miss. Another problematic area is informal economies and grey markets. In many developing nations, a significant portion of economic activity operates outside official systems. When you build an interdependence model using only formal sector data, you're essentially modeling a skeleton and calling it a body. The missing soft tissue matters more than you'd think. I ran into this explicitly while analyzing labor market effects in Southeast Asia. The formal manufacturing sector showed healthy employment growth in the data, but household surveys told a different story about total income stability. The informal sector was absorbing displaced workers and transferring income back to formal households through remittances and shared resources. Ignoring that channel made the entire analysis unreliable. Environmental interdependence is another domain where standard tools underperform. Climate-related disruptions don't respect industry boundaries or national borders. A heatwave reduces agricultural output in one region, which raises food prices globally, which increases social unrest, which disrupts trade routes. Modeling that chain requires combining climate models with economic models, which is technically feasible but introduces enormous uncertainty at every layer. The best I've seen done is scenario-based analysis rather than precise prediction. Anyone claiming precise numerical forecasts for climate-economy feedback loops is likely overstating what the models can actually do.
What To Watch For And When To Change Tactics
High interdependence creates efficiency during stable periods. Supply chains are lean, specialization is deep, and productivity is elevated. That same structure makes the system fragile during disruptions. The 2020 pandemic and the subsequent supply chain crunch demonstrated this clearly. Industries that had optimized for just-in-time delivery and single-source suppliers experienced the sharpest contractions. Those with redundant sourcing or higher inventory buffers recovered faster despite being less efficient in normal times. If you're building models or making decisions based on interdependence analysis, stress test your assumptions against disruption scenarios. Don't just check what happens under baseline conditions. Check what happens when one node goes dark, when a major trade corridor closes, when a currency depreciates sharply. The differences between those outcomes will tell you more about the actual risks than any baseline projection ever will. I've found that running three to five disruption scenarios takes roughly the same time as refining a baseline model and produces far more actionable results. The biggest mistake I see is treating interdependence as a static property. It's not. Relationships shift. New suppliers emerge. Technologies replace old ones. Trade agreements reshape flows. An interdependence map that's more than two years old is already partially wrong. Update your data sources regularly and be prepared to discard relationships that no longer exist in practice even if the historical data still shows them. Outdated connection data is worse than no data because it creates false confidence in your model's accuracy.
Quick Reference For Getting Started
Download the latest BEA input-output tables from the Bureau of Economic Analysis website. The detailed tables are available free. For international work, use the WTO Statistical Database or the UN Comtrade portal. Both provide bilateral trade flow data that you can use to construct network graphs. If you need ready-made indicators, the World Bank's Global Estimation of Interdependence metrics give you a starting point though they lag by about eighteen months. Cross-reference with IMF World Economic Outlook data for more recent signals. For basic analysis, Excel or Google Sheets can handle small-scale input-output calculations. For anything involving more than fifty sectors or cross-border flows, use R with the ImpactIO package or Python with the PyIO library. Both are free and well-documented. Network analysis tools like Gephi work well for visualizing the relationship maps and identifying central nodes visually before you commit to quantitative work. Spending an afternoon on visualization before building the model saves hours of debugging later. The bottom line is that economic interdependence is real, measurable, and critically important for decision-making. But it's also complex, dynamic, and full of blind spots. Approaching it with rigorous data, appropriate tools, and a habit of testing your assumptions against disruption scenarios will serve you much better than relying on textbook descriptions or a single model output. The economy doesn't care about your model. It follows its own rules. Your job is to build something close enough to useful without confusing approximate accuracy with precision.