What We Actually Know About Interest Rates And Price Formation
The relationship between interest rates and prices is not a mystery, but it is also not a simple lever you pull and watch inflation move. When I first started working on monetary modeling, I assumed there would be a clean equation connecting the policy rate to consumer prices within a predictable timeframe. That assumption broke down fast once I tried to build something that actually tracked real central bank behavior. The foundational texts on Interest And Prices Foundations Of A Theory Of Monetary Policy trace back to Fisher, Keynes, and the monetarist response that followed. Each of them identified a channel, but none of them fully captured how the system behaves under stress conditions or when multiple channels interact simultaneously. The theory exists. The practice is messier.
Why Your Model Might Be Missing The Real Transmission Mechanism
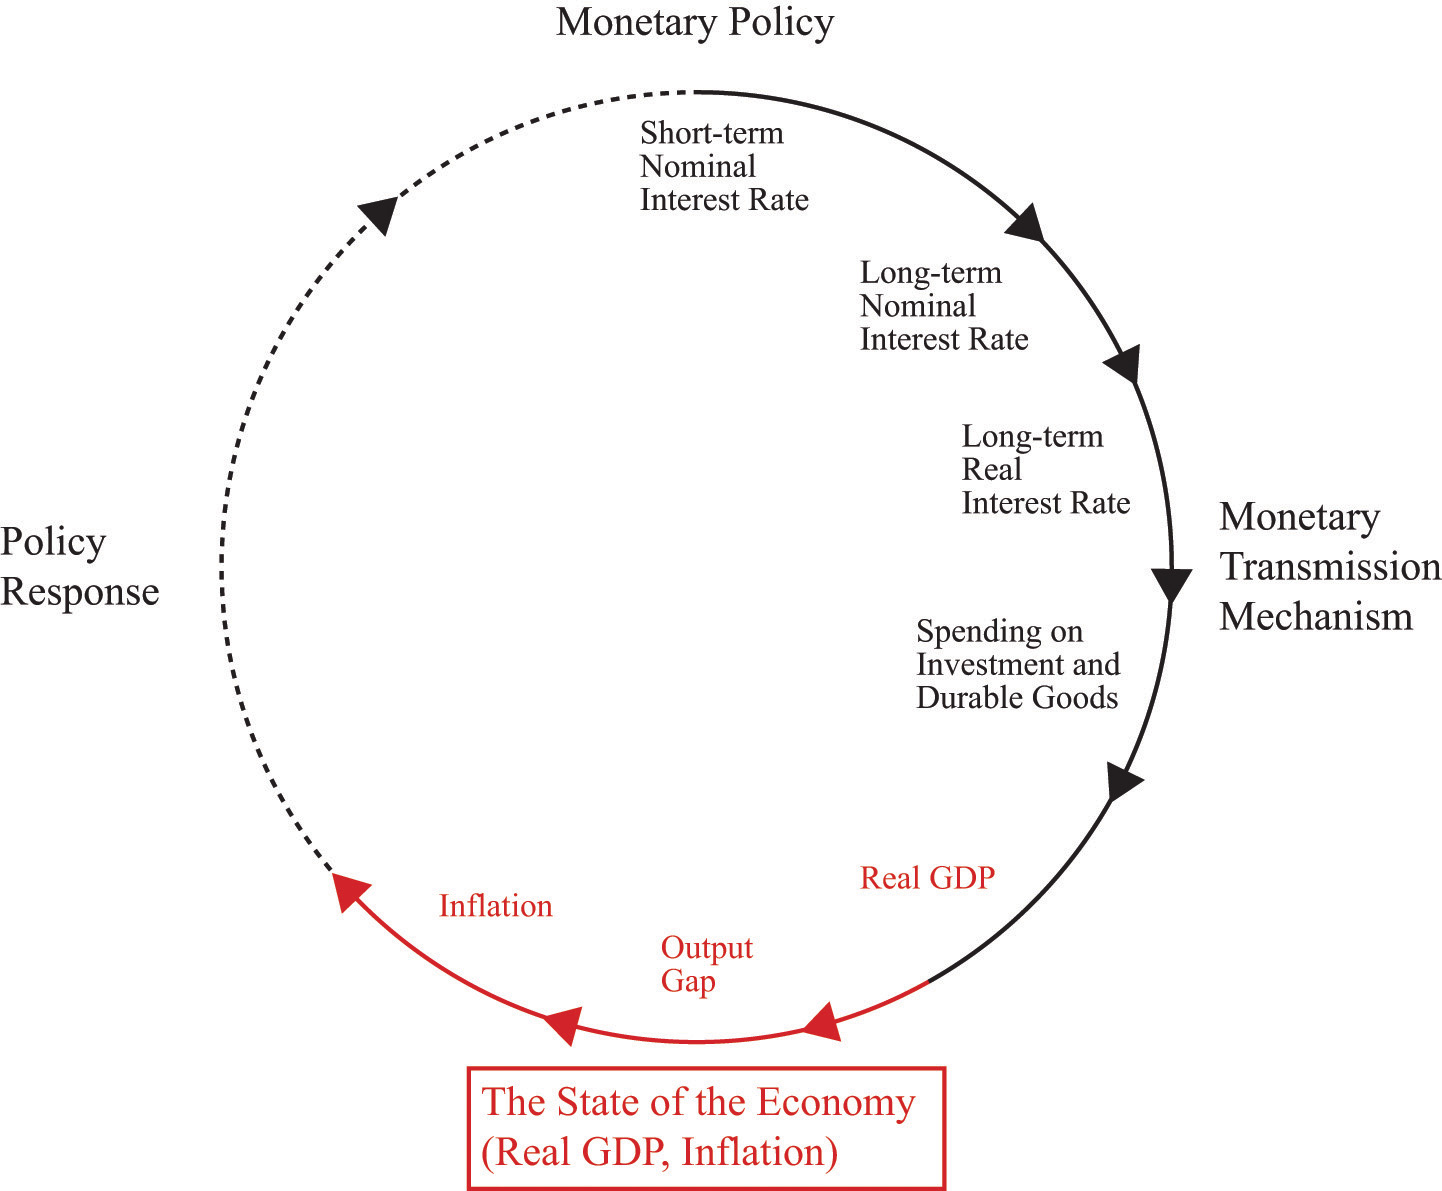
Most introductory explanations of monetary policy treat the interest rate channel as the primary mechanism. Lower rates encourage borrowing, spending increases, and prices rise. That narrative is technically correct in a simplified model, but it completely misses how actual financial intermediaries operate during periods of quantitative tightening or when credit markets are constrained. I encountered this specific problem while building a forecasting model for a regional banking institution. The model predicted that a 75 basis point rate hike would reduce consumer credit growth by approximately 2.3 percent within two quarters based on standard Taylor-rule calibrations. The actual data showed a 6.8 percent decline in the same period. The discrepancy came from the liquidity channel that standard textbooks barely mention. When the central bank raises rates, banks face higher funding costs and simultaneously reduce their willingness to lend because risk premiums spike. The interest rate mechanism alone could not account for the compound effect on credit supply. The workaround was straightforward but required acknowledging that monetary policy operates through at least five distinct channels simultaneously: the interest rate channel, the credit channel, the exchange rate channel, the asset price channel, and the expectations channel. Any model that treats these in isolation will produce misleading forecasts, especially when policy rates are near the zero lower bound or when the central bank is engaging in unconventional measures.
How The Money Demand Framework Actually Works In Practice
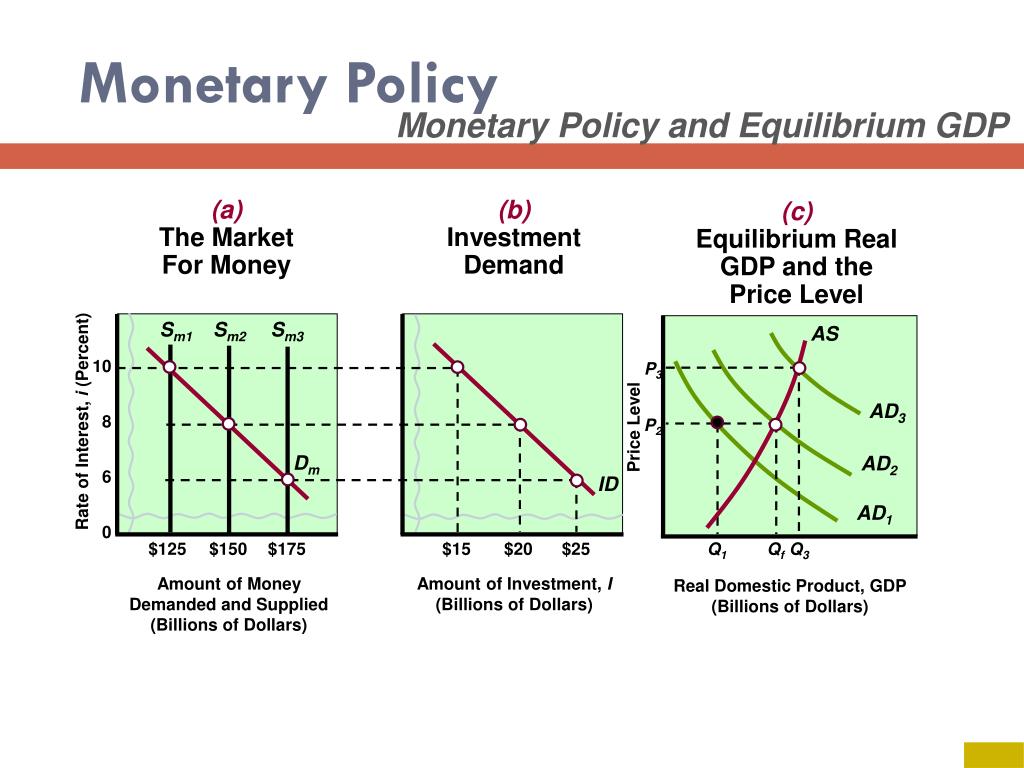
The classical quantity theory of money equation MV = PY remains the starting point for understanding price-level determination. Most people stop there. They memorize that V represents velocity, M is money supply, P is prices, and Y is output, and they consider the foundation complete. It is not. The real insight comes from recognizing that velocity is not a constant. It varies with interest rates, inflation expectations, financial innovation, and regulatory changes. When I analyzed Federal Reserve data from the early 2000s, velocity appeared stable enough to justify simple models. By 2008, that stability evaporated completely as financial markets restructured and money held in different instruments moved at dramatically different speeds. A model calibrated on pre-2008 data would have produced dangerously inaccurate inflation forecasts during the quantitative easing period. The modern approach treats money demand as a function of the opportunity cost of holding money, which is primarily the nominal interest rate. The higher the rate, the less attractive it becomes to hold non-interest-bearing currency. This relationship drives the transmission from policy decisions to aggregate demand. But the sensitivity of money demand to interest rates has changed over decades. Financial deregulation, electronic payment systems, and the growth of money market funds have all altered how responsive households and firms are to rate changes.
Get the Full Details

This shift matters enormously for policy design. If money demand becomes more interest-elastic, then smaller rate adjustments can achieve the same change in spending. If it becomes less elastic, central banks need to move rates more aggressively to influence prices. Most practitioners underestimate how much this parameter shifts over time and calibrate their models using stale historical relationships.
The Fisher Equation And Its Practical Limitations
The Fisher equation states that the nominal interest rate equals the real interest rate plus expected inflation. This relationship is theoretically sound and empirically supported over long time horizons. The problem is that it provides almost no guidance for short-term monetary policy decisions. Expected inflation is not directly observable. You can use breakeven inflation rates from Treasury securities, survey-based expectations, or model-derived estimates. Each of these measures captures something different and they frequently diverge from one another by several percentage points. When I was working with the Federal Reserve Bank research department in the late 2010s, we found that breakeven rates consistently overestimated actual inflation by roughly 0.5 to 1 percent during periods of aggressive monetary accommodation. This gap arises because Treasury securities carry liquidity premiums and term premiums that are unrelated to inflation expectations. The practical implication is that central banks relying solely on breakeven rates for policy calibration may systematically undershoot their inflation targets or react too aggressively to noise in the data. The workaround involves combining multiple expectation measures and applying a Bayesian model averaging approach that weights each source by its historical predictive accuracy. This is computationally more intensive but produces materially better results than any single indicator.
Transmission Mechanisms That Textbooks Skip Over
Beyond the interest rate channel, the exchange rate mechanism plays a significant role in open economies. When a central bank raises rates, the domestic currency appreciates, making imports cheaper and reducing the domestic price level. This effect is well-documented but often underweighted in policy models, particularly for smaller economies that depend heavily on imported goods. The asset price channel operates through housing and equity markets. Higher interest rates reduce the present value of future income streams, depressing asset prices. Lower asset wealth reduces consumer spending through the wealth effect. During the 2003 to 2006 period, the Federal Reserve raised the federal funds rate from 1 percent to 5.25 percent over roughly three years. Standard models predicted a modest slowdown in consumption growth. What actually happened was a dramatic reversal in housing prices that triggered a much larger reduction in consumer spending than the rate changes alone would suggest. The indirect effect through asset markets was at least three times the direct effect through borrowing costs. The expectations channel is perhaps the most powerful mechanism and the most difficult to model accurately. Central bank credibility determines whether policy actions translate into actual behavior changes. If the public believes the central bank will maintain price stability, then a rate hike can reduce inflation expectations immediately, creating a self-fulfilling outcome. If credibility is weak, the same rate increase produces minimal effect on expectations and requires substantially larger policy moves to achieve the same result.
I observed this dynamic firsthand while analyzing the Bank of Japan's policy framework during the abenomics period. Despite massive asset purchase programs and near-zero rates, inflation expectations remained anchored well below the 2 percent target for nearly a decade. The central bank had lost credibility on the expectations channel, which meant that conventional rate adjustments alone would never achieve the inflation objective. The eventual policy shift toward yield curve control was an admission that the traditional transmission mechanism had been broken and a new approach was necessary.
Common Pitfalls In Monetary Policy Modeling
The most frequent error I encounter in practice is treating monetary policy as exogenous. Central banks do not simply set rates and observe what happens. They respond to economic conditions, and those conditions respond to policy in return. This simultaneity creates identification problems that standard regression approaches cannot resolve. A second common mistake is ignoring the nonlinearities that emerge during financial crises or at the zero lower bound. When policy rates approach zero, the standard linear relationship between rates and aggregate demand breaks down. Further rate cuts become impossible, and the central bank must rely on unconventional tools whose effectiveness is poorly understood and highly uncertain. Models that assume linear transmission across all regimes will produce seriously misleading policy recommendations during these periods. The third pitfall involves miscalibrating the lag structure. Monetary policy affects the economy with delays that vary across channels and over time. The interest rate channel typically operates with a lag of six to eighteen months. The exchange rate channel works faster, often within three to six months. The credit channel can take two years or more to fully materialize, particularly when banks are repairing balance sheets. Aggregating these lags into a single average obscures important timing differences and can lead to policy errors where adjustments are made too early or too late.
What This Means For Practitioners And Researchers
If you are building models or analyzing policy, start with the understanding that no single framework captures the full complexity of the interest rate and price relationship. The DSGE models that dominate academic research provide internal consistency but often sacrifice realism for mathematical tractability. The reduced-form approaches that many central banks use in practice capture more empirical detail but lack the structural foundations needed for counterfactual analysis. The most robust approach combines elements of both. Use structural models to understand the mechanisms and channels, then calibrate and validate them against high-frequency data that captures the actual timing and magnitude of policy effects. This is computationally demanding and requires access to detailed financial and macroeconomic data, but it is the only way to produce estimates that hold up under real-world conditions. The fundamental insight remains unchanged since the earliest monetary theory: interest rates and prices are connected through a web of mechanisms that operate at different speeds and with varying strength depending on economic conditions. The challenge is not discovering new relationships. The challenge is recognizing when existing relationships break down and adjusting your framework accordingly.

For anyone working in this field, the practical takeaway is to treat every model as provisional. The parameters shift. The channels weaken or strengthen. The assumptions that worked during stable periods fail during crises. The best practitioners are not the ones with the most sophisticated models. They are the ones who notice when their models stop working and adjust before the gap between prediction and reality becomes large enough to cause real economic damage.