How to actually calculate and work with interest without second-guessing yourself
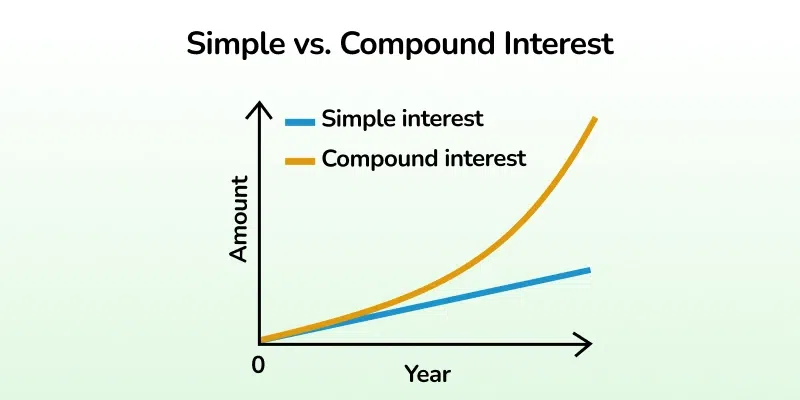
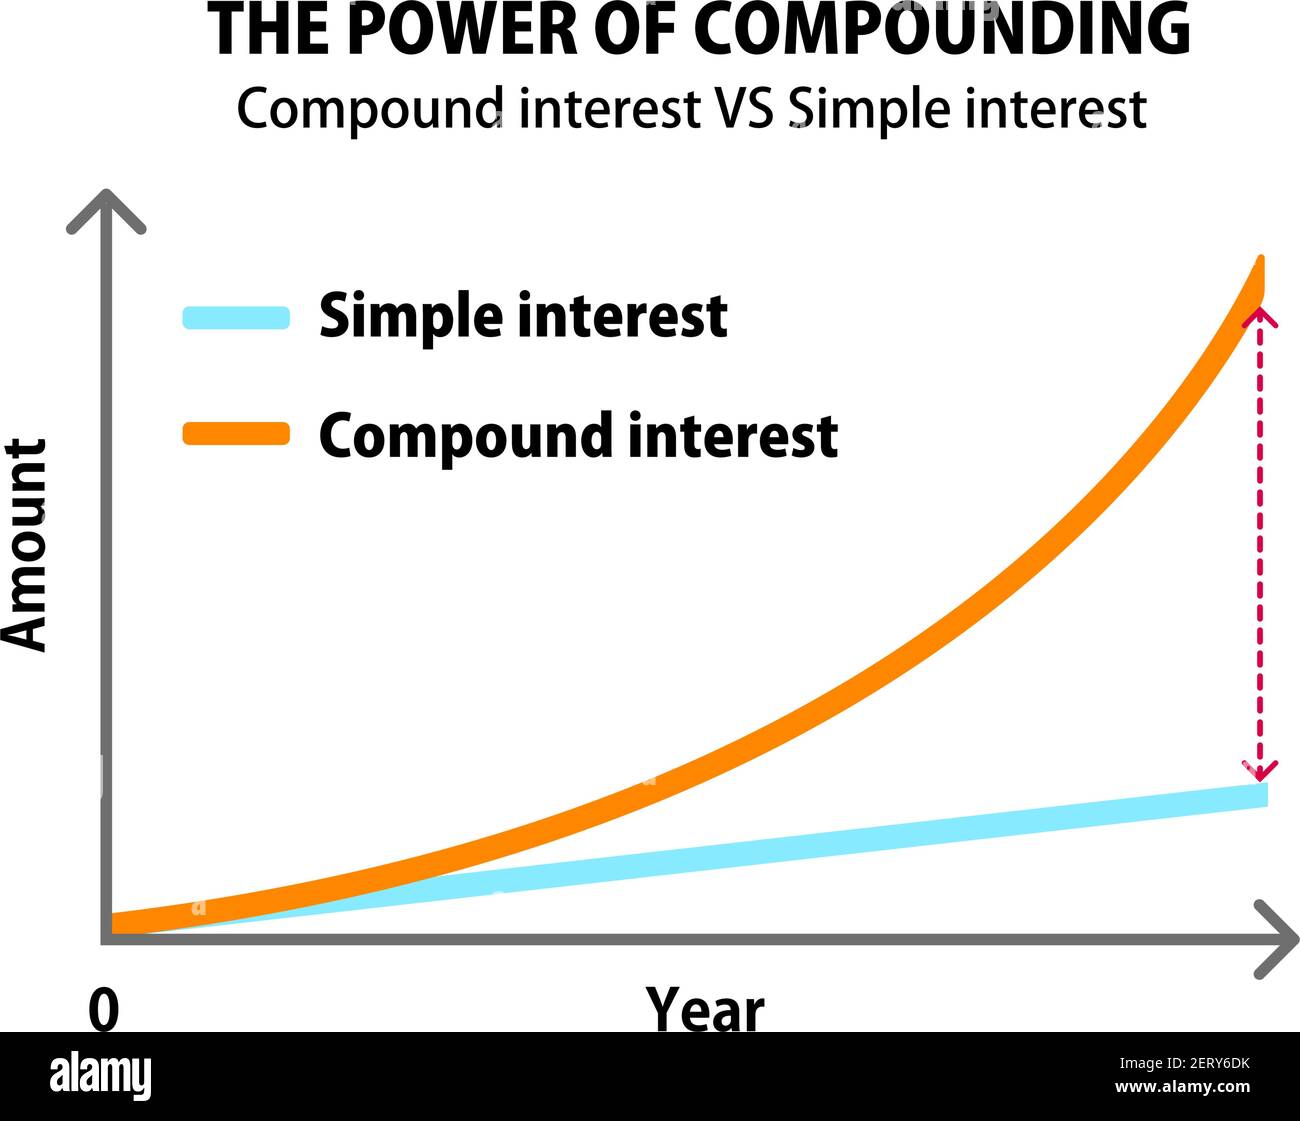
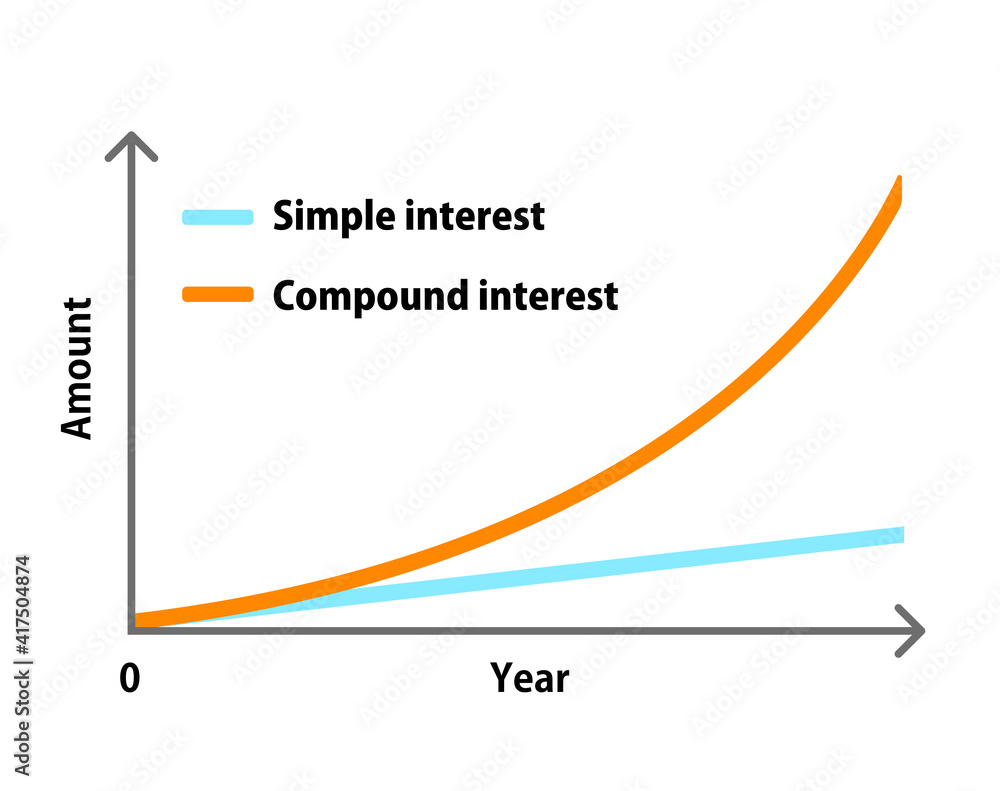
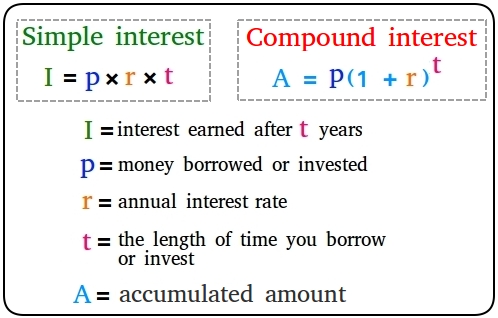
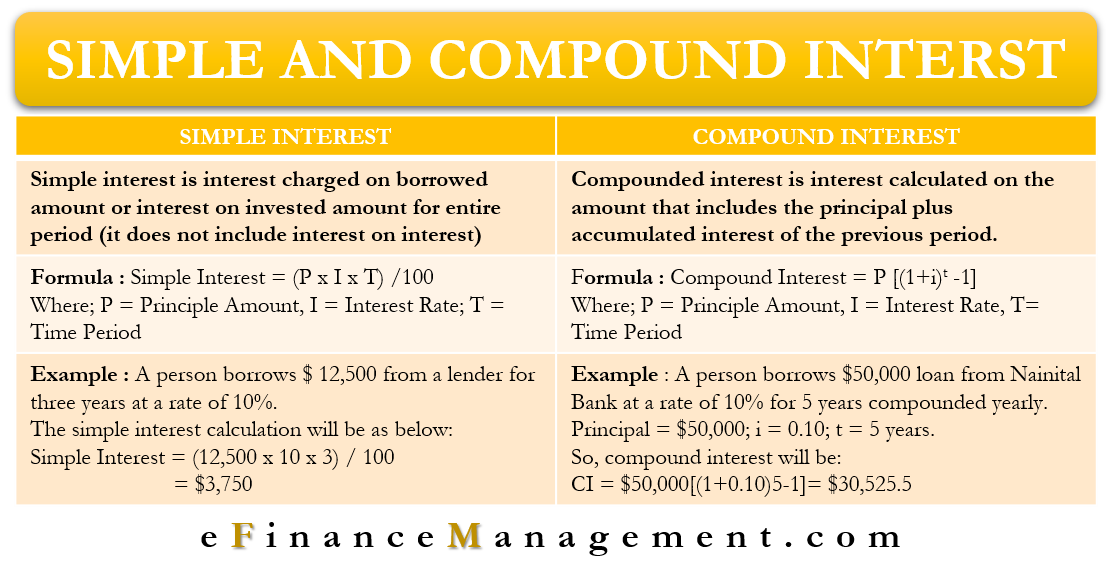
People mix up simple and compound interest constantly, and most online calculators don't make it any clearer because they just spit out a number without showing you which day count convention is being applied. I ran into this problem head-on when reconciling a municipal bond portfolio a few years back. The broker's statement showed interest accrued at a flat 4.5% for a 90-day period, but the actual settlement amount was $187 short of what the standard formula produced. After about two hours of tracing the paperwork, I discovered the broker was using Actual/360 day count convention instead of the more common Actual/365 that I had been applying. Switching to the 360-denominator fixed the discrepancy immediately. This kind of mismatch shows up far more often than it should in retail finance. Simple interest is the most basic form of interest calculation and it works by applying the rate only to the original principal amount. The formula is straightforward: multiply the principal by the annual interest rate by the time period expressed in years. I = P × r × t. That is it. No compounding. No reinvestment of earned interest. Each period generates the exact same dollar amount of interest. Compound interest reinvests the interest earnings so that each subsequent period earns interest on both the original principal and the accumulated interest from prior periods. The standard formula is A = P(1 + r/n)^(nt), where n is the number of compounding periods per year and t is the number of years. The difference between the two can be substantial over longer time horizons, which is why the distinction matters beyond textbook exercises.
Here is a practical example using numbers you can verify on a calculator. Say you lend someone $10,000 at 6% annual simple interest for three years. The interest comes out to $10,000 × 0.06 × 3 = $1,800. Total repayment is $11,800. Now take that same $10,000 at 6% compounded annually for three years. You get $10,000 × (1.06)^3 = $11,910.16. The difference is $110.16. Over ten years with the same parameters, that gap widens to roughly $588 because compounding accelerates.
When to use which calculation
Short-term loans under one year often default to simple interest because the compounding effect is negligible and the math is simpler to communicate to borrowers. Many auto loans, personal installment loans, and Treasury bills operate this way. Some credit unions and community lenders prefer simple interest structures for transparency, since each payment reduces the principal and the remaining interest drops accordingly. That is different from how many revolvers work, where minimum payments barely touch the principal. For investments like certificates of deposit, retirement accounts, and most savings products, compound interest is the norm. The reason is structural, not philosophical. Money deposited early has more time to compound, and the math rewards patience in a way that simple interest never does. A common rule of thumb people use is the rule of 72, which estimates doubling time by dividing 72 by the annual rate. At 6%, your money roughly doubles in 12 years under compounding. Simple interest would take 16.7 years to double at the same rate. That gap is not academic.
Get the Full Details
Day count conventions and why they matter
This is where most people get tripped up in practice. A year is not always 365 days in financial calculations. The actual number of days used as the denominator changes depending on the instrument and the market convention. The main ones you will encounter are Actual/365, Actual/360, 30/360, and Actual/Actual. US Treasury bonds use Actual/365 (or sometimes Actual/Actual depending on whether it is a leap year). Corporate bonds in the US typically use 30/360, which assumes every month has 30 days and every year has 360 days. Money market instruments like commercial paper and certificates of deposit in the US usually use Actual/360, which is why my broker discrepancy happened. The same nominal rate produces slightly different accrued interest amounts depending on which convention applies. Over a full year, Actual/360 yields about 1.4% more interest than Actual/365 at the same stated rate. That is material when you are dealing with six-figure principals.
Common pitfalls
The first mistake people make is assuming that a quoted annual rate means the same thing across all products. A 5% CD and a 5% money market fund may use different day count conventions, so the effective yield differs. Always check the prospectus or the loan disclosure documents. The second mistake is treating simple interest as if it is always cheaper without running the actual numbers over your expected holding period. If you pay off a simple interest loan early, you save on interest because you reduce the principal faster. But if you are the one earning the interest, early payoff costs you. The direction matters. A third pitfall involves partial periods. If you invest for 45 days at a simple interest rate quoted on an annual basis, you cannot just multiply by 45. You need to convert the time fraction properly using the right day count convention for that instrument. Using 45/365 when the convention is Actual/360 overstates the interest slightly. Using 45/360 when the convention is Actual/365 understates it. The error is small on tiny amounts but scales directly with principal.
A quick reference for manual calculation
If you need to compute simple interest without a calculator, break the multiplication into steps. Take $5,000 at 7.2% for 120 days using Actual/360. First convert the rate to a daily decimal: 0.072 divided by 360 equals 0.0002. Then multiply by the principal: 0.0002 × 5,000 = 1.00 per day. Multiply by 120 days to get $120 in interest. Total return is $5,120. You can verify this with the standard formula in about ten seconds on any phone calculator. The point is that doing it by hand reveals the mechanics, and knowing the mechanics helps you spot when a quoted figure looks wrong. For compound interest, the manual path is slower but still doable for short periods. $5,000 at 7.2% compounded monthly for one year means dividing the annual rate by 12 to get the periodic rate: 0.072 / 12 = 0.006 per month. Then raise (1 + 0.006) to the 12th power and multiply by 5,000. That gives approximately $5,372.83. The simple interest version for the same nominal rate and period would be $5,360. The compound version earns $12.83 more. Small now, larger later.
What simple interest gets wrong
Simple interest does not account for the time value of money beyond the linear relationship. It treats every dollar of interest the same regardless of when it is paid. In reality, receiving interest sooner allows you to reinvest it, which simple interest ignores by definition. This makes simple interest useful for short-term transparent pricing but inadequate for comparing products with different compounding frequencies or for valuing cash flows that extend beyond a couple of years. If someone offers you a simple interest note with a five-year term, ask them to also show you the equivalent compound annual yield. The numbers will diverge enough to change your decision. There is also the issue of payment timing within a compounding period. Some lenders apply payments to interest first, then principal. Others use a more neutral approach. The method changes how quickly your balance drops and therefore how much total interest you pay. Before signing anything, confirm the payment application order. It is usually disclosed in the fine print but rarely highlighted.
When to walk away from a simple interest product
Not every simple interest offering is bad. The structure is honest and easy to understand, which is a genuine advantage for certain borrowers who want predictable costs. But if the quoted rate is higher than comparable compound interest products after adjusting for day count and compounding frequency, the simple interest label is just marketing. Run the equivalent yield comparison before committing. A few minutes of arithmetic can save you thousands over the life of a loan or investment.