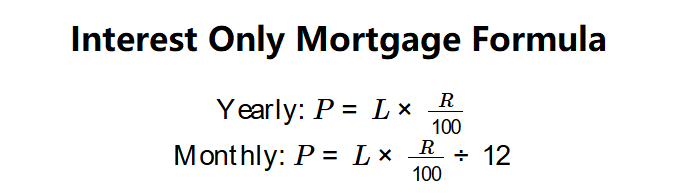
How the Calculation Actually Works
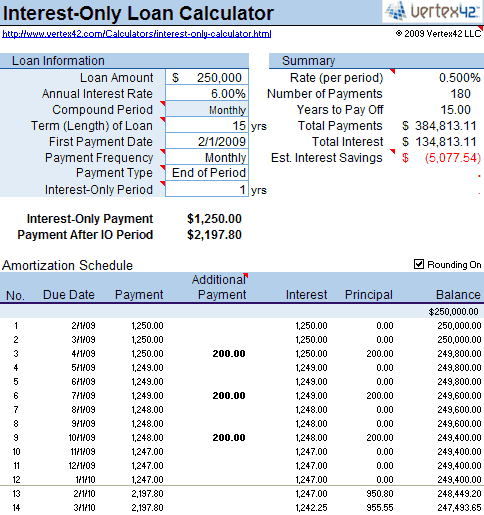
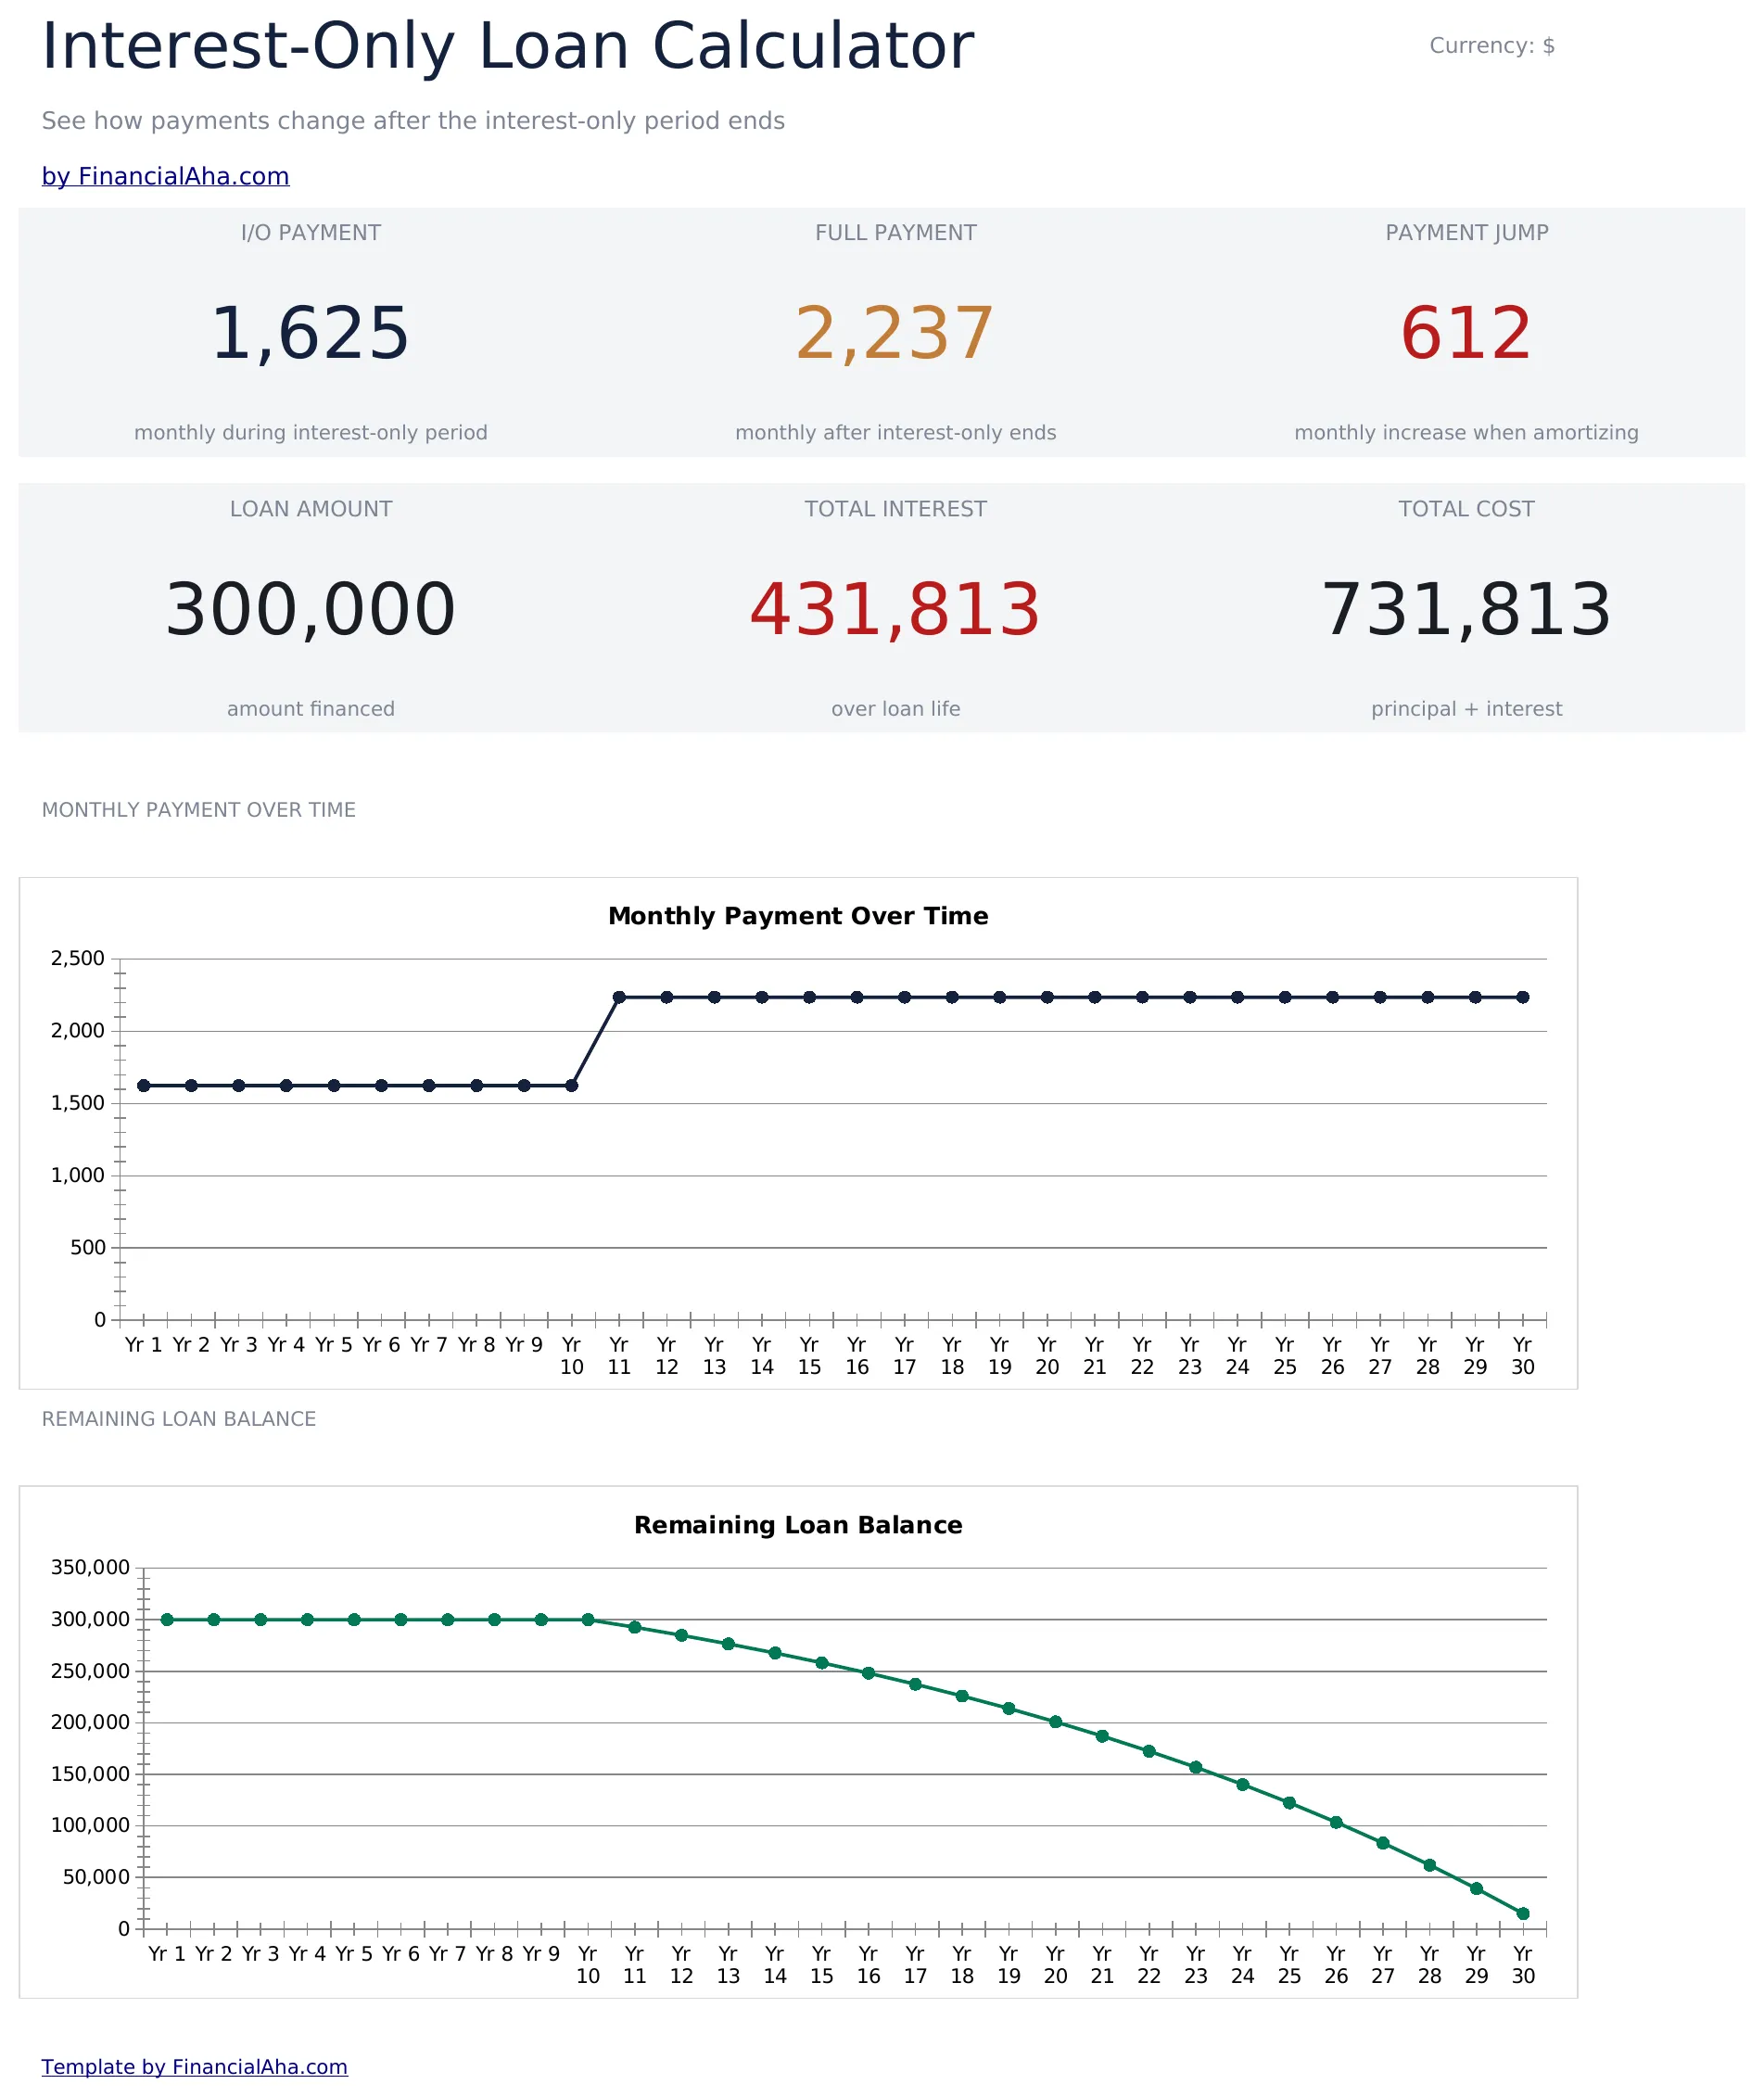
Take your loan balance, divide it by 12 to get the monthly period, then multiply by the annual interest rate. That's it. The principal never changes because you're only paying the interest portion every month. When I first set up an Interest Only Calc sheet for a commercial refinance back in 2014, I wasted about two days building a fully amortizing calculator that defaulted to showing principal reduction. My client needed pure interest payments for a 36-month bridge period, and the output was completely wrong for his cash flow model. I rewrote it from scratch in a single afternoon once I stopped overcomplicating it. The output is straightforward: a monthly payment figure that stays identical for the entire interest-only period, followed by whatever happens when that period ends. If you have a $500,000 loan at 6.5% annual rate, your monthly payment is $2,708.33. The balance remains $500,000 regardless of how many months pass. This is different from a standard amortizing loan where each payment chips away at principal and the payment amount stays fixed but the principal-versus-interest split shifts over time. One thing most people miss is what happens after the interest-only period expires. The balloon payment or the recast can completely wreck a borrower's cash flow if they haven't planned for it. With the same $500,000 balance at 6.5% over a remaining 25-year amortization, your new payment jumps to roughly $3,493 per month. That's a $785 increase out of nowhere. I've seen borrowers sign these loans expecting to sell or refinance before the recast hit, but the market didn't cooperate and they were stuck.
Setting Up the Calculation Manually
You don't need fancy software for this. A spreadsheet with three cells gets you there in under five minutes. Cell A1 is your principal balance. Cell A2 is your annual rate as a decimal (0.065 for 6.5%). Cell A3 is just A1 times A2 divided by 12. That's your monthly interest-only payment. If you want the total interest paid over N months, multiply that monthly figure by N. It is that direct because nothing amortizes. Where it gets messy is when your loan has a hybrid structure. Maybe the first five years are interest only, then the remaining 25 years amortize. Or maybe there's a rate reset at year three. I worked on a deal last year where the borrower thought they had a pure interest-only loan but the fine print said the rate would step up after 36 months from 5.75% to 7.25%. The monthly payment went from $2,375 to $3,000 without any warning in the marketing materials. Always read the rate adjustment clause before you build the model around the initial rate.
Common Mistakes That Cost Money
The biggest error I see is people confusing the annual percentage rate with the note rate. If your loan says 6.5% but the APR is 6.87% due to points and fees, your actual interest calculation should use the note rate, not the APR. The APR is a disclosure figure, not a payment figure. Using the wrong number throws off every subsequent projection in your model. Another issue is prepayment behavior during the interest-only window. Some loans allow extra principal payments that reduce the balance going into the amortization phase. Others don't permit it or penalize it heavily. If you're modeling a scenario where you might pay down principal during the IO period, check the lockout provisions. A typical lockout might be two to three years where any prepayment triggers a yield maintenance or defeasance penalty that costs more than the interest you saved.
Get the Full Details
When This Approach Breaks Down
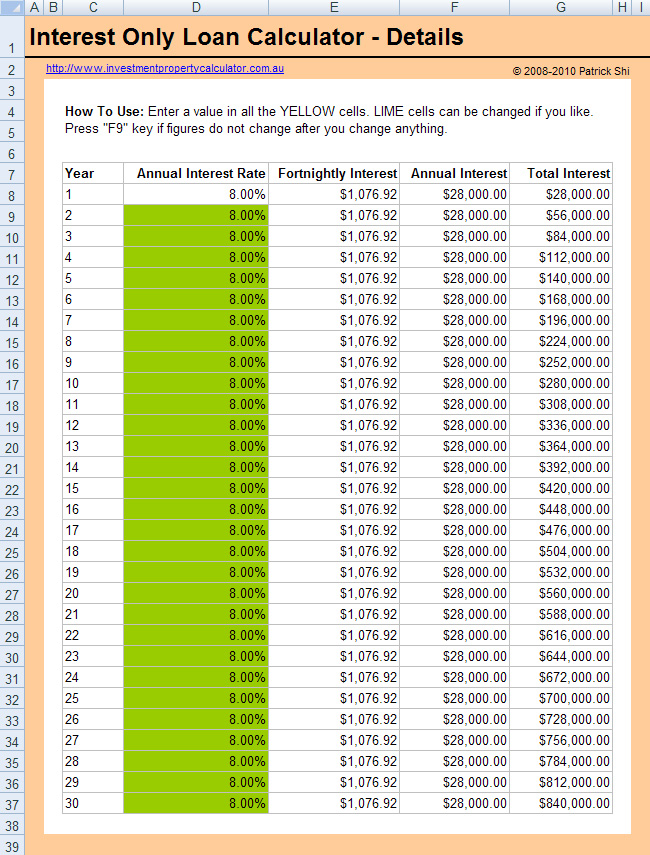
An Interest Only Calc becomes unreliable when the loan includes an adjustable rate with caps and floors, because the payment isn't actually fixed even during the interest-only period. The rate can reset annually or semi-annually depending on the index, and the payment will adjust within the cap structure. If you're budgeting for a single static number and the index moves 200 basis points, your payment could shift significantly without any change to the underlying balance. It also breaks down conceptually if you're trying to model tax implications. The interest deduction rules changed for certain types of investment property after 2018, and the interaction between IO loans and the passive activity loss rules gets complicated fast. You're better off running those numbers through a CPA tool rather than a spreadsheet.
Practical Example With Real Numbers
Let me walk through a scenario I dealt with last quarter. A client had a $1,200,000 commercial property loan at 5.5% for a 7-year interest-only period with a 23-year amortization afterward. Monthly payment during IO: $5,500. Total interest paid over 7 years: $462,000. After the IO period, the payment recalculates on the full $1,200,000 balance over 23 years at the same rate, which comes to approximately $7,689 per month. The difference between what they were paying and what they will pay is $2,189 per month. That gap needs to exist in their pro forma or the deal doesn't work. I had them run a sensitivity analysis at 6.5%, 7.5%, and 8.5% for the post-IO period because rate risk was the real threat here, not the IO structure itself. At 8.5%, the post-IO payment hit $9,744. That alone changed the net operating income requirement enough to kill the acquisition. We walked away from that deal before closing.