Most people don't realize that an interest-only mortgage payment is just principal balance times annual rate divided by twelve. That is it. There is no amortization happening during the initial period, usually five to ten years, so the monthly number stays flat while you owe nothing toward the actual loan balance. It sounds straightforward until you actually sit down and build out a calculator for it, or try to figure out what happens when the interest-only period ends and your payment jumps by forty, fifty, sometimes sixty percent.
I have seen borrowers take out a $400,000 interest-only loan at 6.5% and happily pay about $2,167 a month, then get blindsided when the term resets and the payment recalculates over the remaining twenty-five years at the same rate. The new payment goes to roughly $2,750. That is a $580 difference that nobody warned them about up front.
Building Your Own Interest Only Calculator Monthly Payment Tool
If you want to make a simple Interest Only Calculator Monthly Payment tool, the math takes about three lines of JavaScript. You need a text field for the principal balance, another for the annual interest rate, and a third for the loan term in years. Then you just compute the monthly payment as (balance × rate) ÷ 12. The reset calculation is where it gets messier, because you need to apply the standard amortization formula to the full balance with the remaining term.
Here is what a basic version looks like:
That handles the interest-only portion cleanly. For the full picture including the post-reset payment, you add an amortization function that takes the same principal, the same rate, and the remaining months until payoff.
Where These Calculators Break Down
I built a fairly detailed one for a client a few years back who was comparing two lenders on an investment property. The first lender quoted a 6.75% rate with a six-year interest-only period, the second lender at 6.625% but with an eight-year term. The monthly payment difference was only about thirty-two dollars during the interest-only window. Easy math, right? Not exactly.
The problem was that the first loan had a prepayment penalty clause kicking in if the borrower refinanced before year seven, and the second loan had an assumability feature that let the buyer take over the existing rate. When I factored in the prepayment penalty equivalent — roughly four points if refinanced at year five — the total cost of the first loan actually came out higher despite the slightly longer interest-only window. A basic calculator won't show you any of that. You have to model the exit strategy separately.
Another thing nobody mentions is that some lenders calculate the interest-only payment using a 360-day year while others use 365. On a half-million-dollar loan at 7%, that difference is about $28 per month. Over three years that adds up to roughly $1,000, and the borrower never knows which convention their lender is using until the statement arrives.
What Most Calculators Miss
A proper tool should also account for property taxes and homeowners insurance, because those are baked into escrow and show up on your actual payment even though they aren't part of the interest-only computation. On a $500,000 home in a area with 1.8% effective property tax and $1,200 annual insurance, you're looking at an extra $990 per year in escrow, or about $82.50 per month, layered on top of the interest-only principal and interest figure. If your calculator only shows the P&I number, it is lying to you by omission.
There is also the balloon payment edge case. Some interest-only structures require the entire principal to come due at the end of the term rather than transitioning into amortization. A standard calculator won't flag this unless you explicitly input balloon terms. I once had a borrower who thought she was getting a five-year interest-only followed by a fully amortizing term, when in fact the contract specified a balloon payment. She had six months to come up with $310,000 or sell the property. A good calculator catches that by making you select the loan type explicitly.
When to Use One Instead of the Other
The Interest Only Calculator Monthly Payment calculation is genuinely useful for planning cash flow during the initial period, especially if you are a flipper or a buy-and-hold investor who expects to sell or refinance before the reset. The lower payments free up capital for renovations or other deals. But it is almost never the right tool for evaluating whether the loan itself is a good decision. For that, you need a full cost analysis that includes the reset payment, the total interest paid across both periods, and the impact of any prepayment penalties or fees.
One final note on accuracy. Many online calculators round the monthly rate by dividing the annual percentage by 12 and then rounding to four decimal places before multiplying. That introduces a small error each month. On a $300,000 loan at 5.5%, the discrepancy is about three dollars per month. Over ten years that is roughly $360. It doesn't change the bottom line dramatically, but if you are building a calculator yourself, keep the decimals unrounded until the final output step. It is a habit worth learning early.
Gallery Interest Only Calculator Monthly Payment
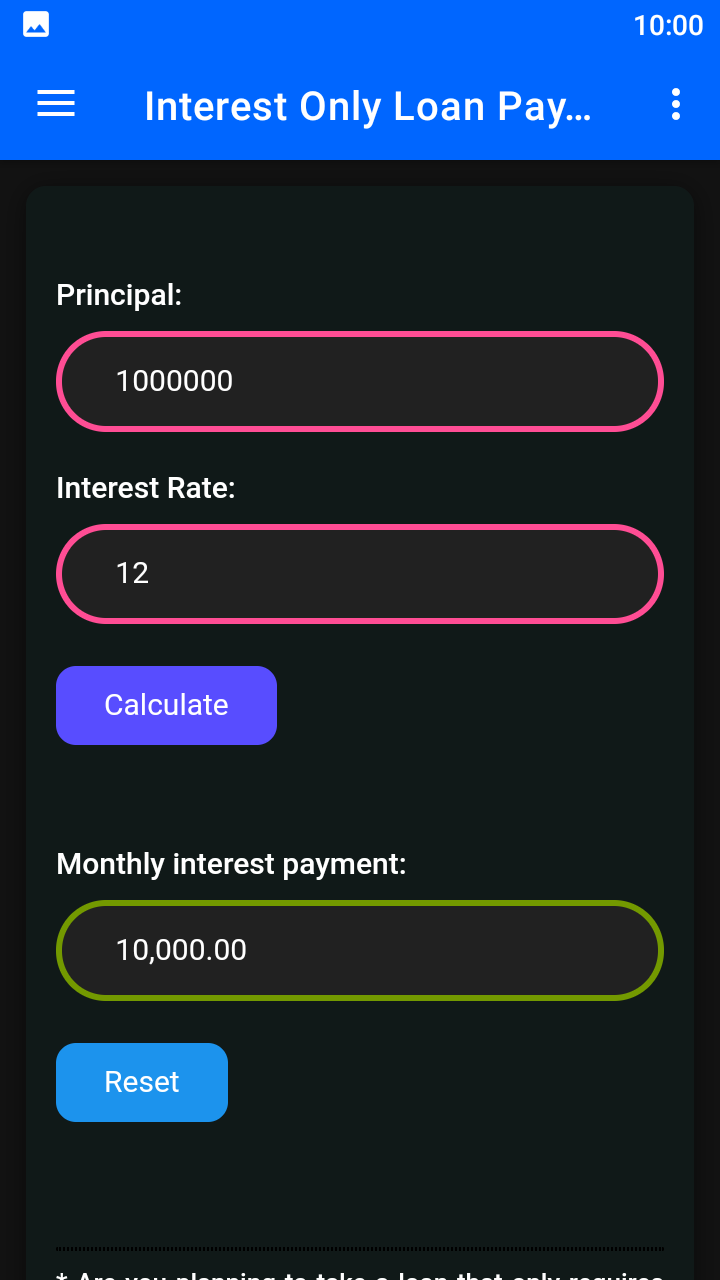
Interest Only Loan Payment Calculator - App on Amazon Appstore
What Is An Interest Only Payment Calculator? - Easiest Mortgages
Free Monthly Payment Calculator Templates For Google Sheets And Microsoft Excel - Slidesdocs
Auto Payment Interest Calculator at Phoebe Reddall blog
Monthly Interest Calculator - Calculator Academy