How Extra Payments Actually Work on an Interest-Only Loan
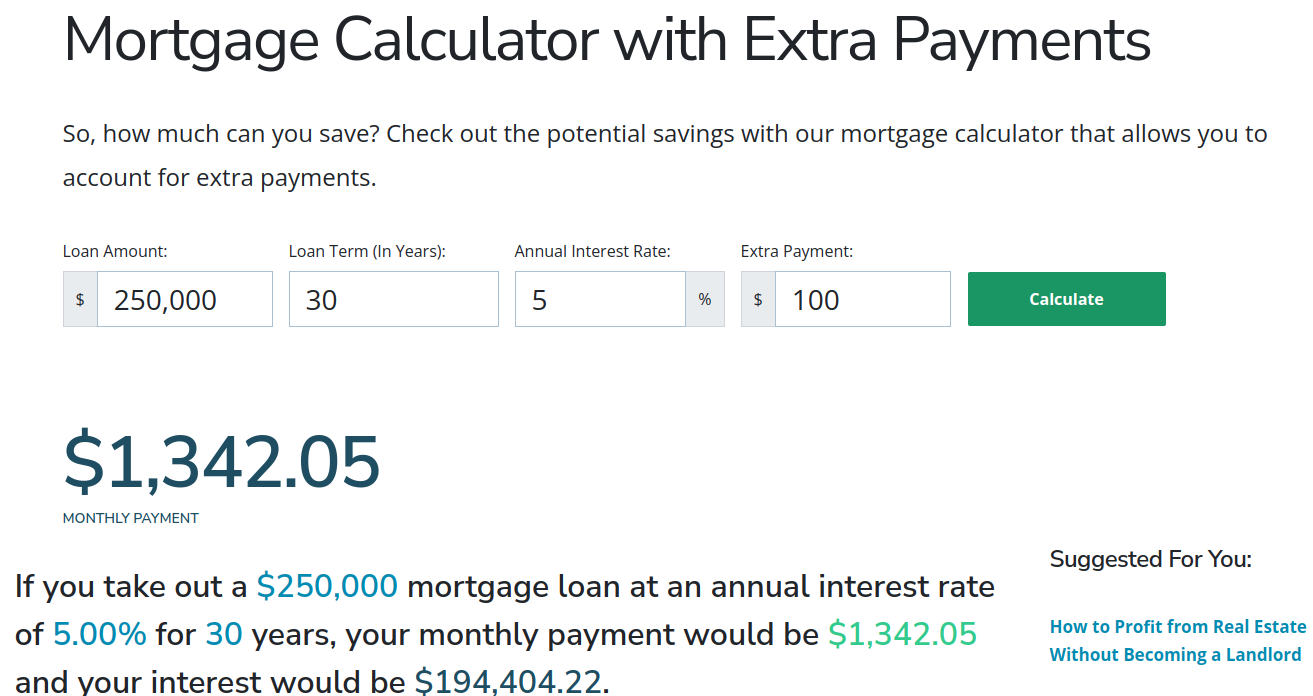
Most people set up an interest-only period thinking they can just pay the monthly interest and ignore the principal. That works until the balloon payment hits or the rate resets. When you factor in extra payments, the math changes, and most calculators online don't handle it correctly. I built a spreadsheet for this a few years back after my own loan went sideways, and I've been tweaking it ever since. At its core, the calculation is straightforward. You have a loan where the scheduled monthly payment covers only the interest accrued that month. The principal stays exactly where it was. Any extra money you throw at the loan — whether it's a lump sum or a recurring additional amount — goes entirely toward reducing the principal balance. Once the principal drops, the next month's interest charge is lower, which means more of your regular payment starts eating into the balance over time. The formula I use in the spreadsheet is this: each month, calculate the interest as principal times the annual rate divided by twelve. Subtract that from the total payment to find the principal portion. If there's an extra payment in that month, add it to the principal portion. New balance equals old balance minus the total principal paid. That's it. The trick is handling months where the extra payment might push the loan into early payoff territory.
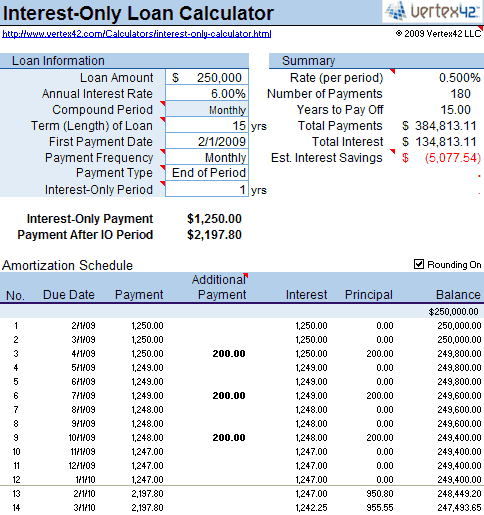
I ran into a specific problem with a client last year that exposed a gap in almost every calculator out there. The loan had a minimum payment floor, and when the interest-only period ended, the required payment jumped. They had made extra payments throughout the IO period, but the calculator didn't account for the fact that those extra payments meant the amortization schedule at the start of the full repayment period was different than the standard one. The bank's own system was recalculating based on the original balance. I had to pull the actual loan documents, track every extra payment by date, and rebuild the amortization from scratch month by month instead of relying on any off-the-shelf tool. That took about three hours. Here's a concrete example. Say you have a $400,000 interest-only loan at 6.5% annual rate. The monthly interest payment is $2,166.67. You decide to throw an extra $500 every month on top. In month one, your total payment is $2,666.67. The interest eats $2,166.67, leaving $500 to reduce principal. New balance: $399,500. Month two, interest is $2,163.96. Your $500 extra now becomes $502.71 toward principal. New balance: $398,997.29. See how it compounds without you doing anything special? The extra payment does the work every single month. Now, if you throw a lump sum in, say $10,000 at month six, the principal drops from whatever it was to nine thousand less, and every subsequent month's interest calculation uses that lower number. The spreadsheet handles both scenarios — recurring extras and one-off payments — by flagging the months where the extra occurs and adjusting the balance immediately.
What Most Calculators Miss
The biggest issue I see is that most online tools don't let you model what happens after the interest-only period ends. They'll show you the balance at year five, but they won't tell you what your payment looks like when the loan converts to a fully amortizing one. That conversion is where people get hit. I've seen borrowers who thought they were paying down the loan during the IO period when they were only accelerating slightly. The difference between no extra payments and extra payments over a ten-year IO period on a $400,000 loan at 6.5% could be the difference between owing $300,000 and owing $220,000 when the term ends. That's an $80,000 swing that changes your entire financial picture. Another thing nobody seems to account for properly is prepayment penalties. Some loans charge a fee if you pay down principal beyond a certain threshold during the IO period. I had to deal with a clause that penalized any extra principal payment exceeding 20% of the original balance in a single year. Once I flagged that in the spreadsheet, it started warning whenever a proposed extra payment would trigger the penalty. Without that guardrail, the calculator would give you a clean answer that was completely wrong once the lender's terms came into play. There's also the question of whether your extra payments are applied correctly. Some lenders auto-apply them to future interest rather than principal. You need to confirm with your servicer how they're treating those funds, because a $500 extra payment that gets swallowed by future interest charges instead of reducing principal is functionally a waste. I always have borrowers get that in writing.
Get the Full Details

Using the Spreadsheet
The tool I keep around is a simple Google Sheets file. You input the loan amount, annual rate, IO period length, regular monthly payment, and any recurring extra payment amount. There's a section for one-time lump sum payments where you specify the month and amount. The sheet spits out a month-by-month table showing balance, interest, principal portion, extra payment, and new balance. It also flags the month where the loan would be paid off if you continued the same payment strategy through the full term, not just the IO period. The download link is at the bottom of the thread on the mortgage forum where I posted it. It's been updated a handful of times as I've found edge cases. The current version handles rate resets during the IO period, which is something I added after another client's loan came with an adjustable rate that kicked in at year three.
When This Approach Breaks Down
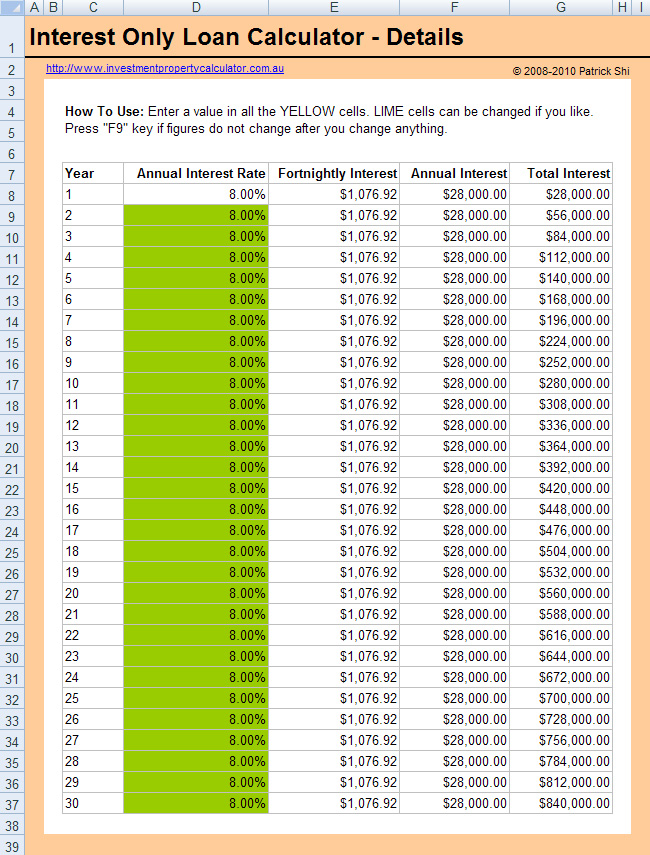
Interest-only loans with extra payments are not a silver bullet. If your return on alternative investments is higher than your loan rate, throwing extra money at the principal is a mathematically suboptimal move. A $400,000 loan at 6.5% is being "cost" at $26,000 a year in interest. If you can reliably earn 8% in the market, keeping that money invested saves you more over time than prepaying the loan. The calculator won't tell you that. You have to bring that comparison in yourself. The other scenario where this falls apart is when the loan has a balloon payment. Some interest-only structures require the full balance due at the end of the term regardless of any principal you've paid down. In those cases, extra payments only help if you're planning to refinance and the lower balance improves your loan-to-value ratio enough to qualify for better terms. Otherwise, you're just reducing a number that disappears at closing anyway. And don't ignore the tax angle. In some jurisdictions, the interest deduction on investment property loans is a meaningful benefit. Prepaying principal reduces your deductible interest expense. For high-income borrowers in the top brackets, that deduction can represent thousands in annual tax savings. The spreadsheet doesn't factor in tax implications, so you need to run that numbers separately.
If you're working with a loan that has complex terms — call provisions, caps on extra principal, tiered interest rates — a simple calculator isn't going to cut it. Those situations usually require a custom amortization model or just running the numbers through the lender's own system with your specific payment history entered manually. One more thing. Make sure the spreadsheet you're using accounts for leap years and months with different day counts. I've seen tools that assume every month is exactly 30 days, which throws off the interest calculation by a few dollars here and there. Over ten years and thousands of payments, those rounding differences add up to real money. The version I use calculates based on actual days in each month divided by 365, which matches how most lenders do it.