Understanding the Mechanics of an Interest Only Loan Payment
An interest only loan payment is what you pay when your lender allows you to service just the accrued interest for a set period, rather than paying down any principal balance. The principal stays untouched. Your monthly figure is calculated by taking your outstanding loan balance, dividing it by 12 to get the monthly rate, then multiplying by the annual interest rate. That gives you the pure interest charge for that month. If you have a $300,000 loan at 6.5 percent, your monthly interest only payment comes to $1,625. The principal balance remains exactly $300,000 throughout the interest-only window. I learned this the hard way on a commercial refinance back in 2019. The borrower had a five-year interest-only period, then jumped to a fully amortizing schedule over the remaining 25 years. He assumed the payment would stay manageable. It didn't. The payment increased by roughly 40 percent once principal amortization kicked in because the entire $300,000 was still owed and now being paid off over a shorter remaining term. We caught it during the pre-close analysis, but not before he'd already been quoting that lower number to his partners for months. The lesson: always project the payment after the interest-only period ends, not just the payment during it.
How to Calculate Your Interest Only Loan Payment
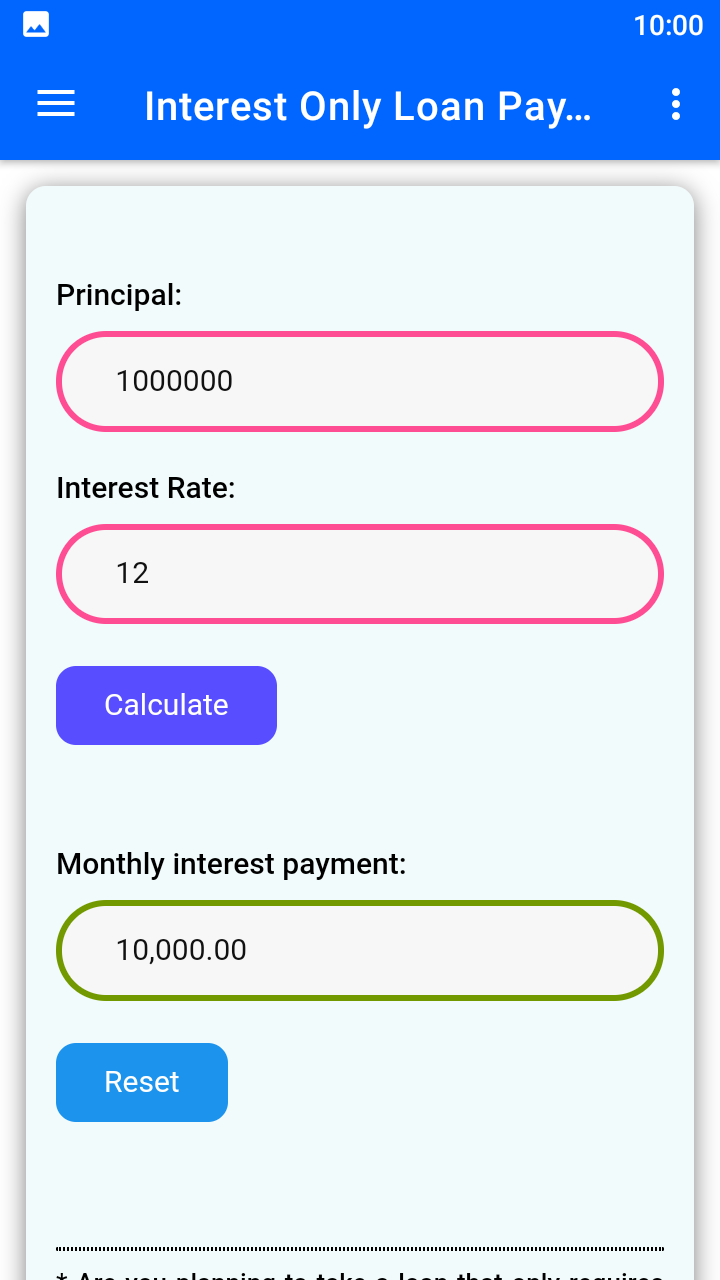
The formula itself is straightforward. Take your current principal balance, multiply it by your annual interest rate, then divide by 12. That is your monthly interest only payment. Lenders present it this way because it keeps the math transparent, though some will bake in a small administrative fee on top that they call a servicing charge. That extra $10 to $25 per month is where people get confused and think they are paying less than they actually are. Always check the Breakdown of Charges document before signing. A $300,000 loan at 7.25 percent works out to $1,812.50 per month in pure interest. With a $15 servicing fee, you are paying $1,827.50. The difference looks small until you multiply it across a dozen months and then realize you budgeted for the lower number the whole time. Here is something most people miss: your payment does not lock in forever even within the interest-only window. If you have an adjustable-rate mortgage or a commercial loan with a reset clause, the rate can change every one, three, five, or seven years depending on the index and margin. A rate moving from 6 percent to 7 percent on that same $300,000 balance adds $83.33 to your monthly payment overnight. That is not a rounding error. That is a line-item increase that shows up on your statement and forces a recalibration of your cash flow if you are running tight margins. I advise running a stress test at 1.5 to 2 percentage points above your current rate before you commit to anything interest-only. It takes about ten minutes in a spreadsheet and prevents a lot of late-night panic calls in year three. The other thing that trips people up involves the balloon payment structure. Some interest only loans are structured so that no principal is paid during the term and then the full balance comes due at maturity. A common setup is a five-year interest-only period with a seven-year maturity date, meaning you pay interest for five years and then have two more years to either refinance or sell the asset before the balloon hits. This is standard in commercial real estate lending. In residential, it shows up more often as a recast or re-amortization scenario. Either way, the clock starts ticking the day you close, and the payoff date is hard-coded in your promissory note. You cannot negotiate it away after the fact without refinancing, which means you need to be qualifying for a new loan two years before the balloon is due. That is usually when lenders start asking harder questions about your debt-service coverage ratio or loan-to-value ratio, depending on the asset type.
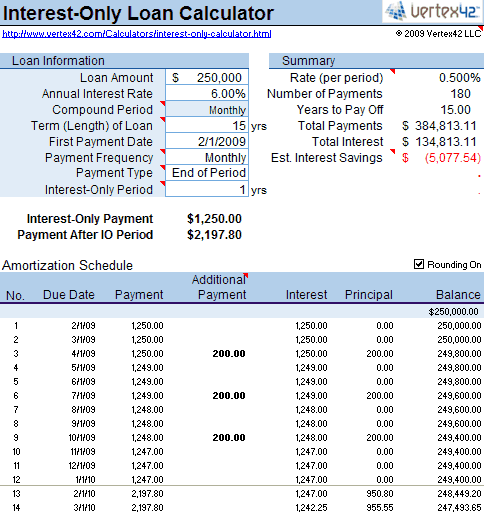
If you are looking at an actual calculator or spreadsheet to project your payments, most online tools let you input the principal, rate, and term. Set the amortization period equal to the full loan term but choose the interest-only option for the first segment. Some platforms call it a hybrid loan structure. What matters is that you see two distinct payment tiers laid out clearly. If your tool only shows one payment number, it is probably calculating a standard amortization, not an interest-only schedule. Run both scenarios side by side. The gap between them is the actual cost of deferring principal, and it is usually larger than people expect because compound interest keeps accruing on the full balance the entire time. The biggest downside to an interest only loan payment is exactly what the name implies: you are not building equity. Every month you make the payment, your loan balance stays the same. If your property value drops, you can quickly find yourself underwater. I worked with a buyer in 2022 who took an interest-only period on a multi-family property assuming values would keep climbing. They didn't. When the interest-only window closed, he needed to refinance but the appraisal came in 12 percent below his purchase price. The lender wouldn't touch it. He ended up selling at a loss because he had no equity cushion and no principal reduction to fall back on. Interest-only loans are fine when you have a clear exit strategy or when the cash flow surplus lets you invest elsewhere at a higher return than your loan rate. They are dangerous when you assume the property will pay for itself through appreciation alone. A practical workaround I use with clients is to set up a separate sinking fund account during the interest-only period. Even if you only contribute 20 to 30 percent of what a fully amortizing payment would be, that money accumulates and can be applied to principal once the interest-only period ends. It does not reduce your monthly obligation during the low-payment phase, but it narrows the gap when the payment resets. On a $500,000 loan, putting aside an extra $400 a month for five years gives you $24,000 toward principal before the recast. That knocks roughly $150 to $200 off your new monthly payment depending on the rate. It is a small hedge, but it is better than walking into a payment shock with nothing to absorb it.
Get the Full Details
Most lenders will not voluntarily flag these risks because the interest-only structure sells easier. The lower payment looks good on the brochure. Your job is to read past the brochure and look at the amortization schedule, the reset provisions, and the maturity date. If your loan document mentions a conversion feature or a mandatory recast clause, treat it as a scheduled event, not a contingency. Plan for it two years in advance. Otherwise you are just hoping the market behaves kindly while you wait to find out how much your payment is really going to cost.