How an Interest Only Loan Payoff Calculator Actually Works
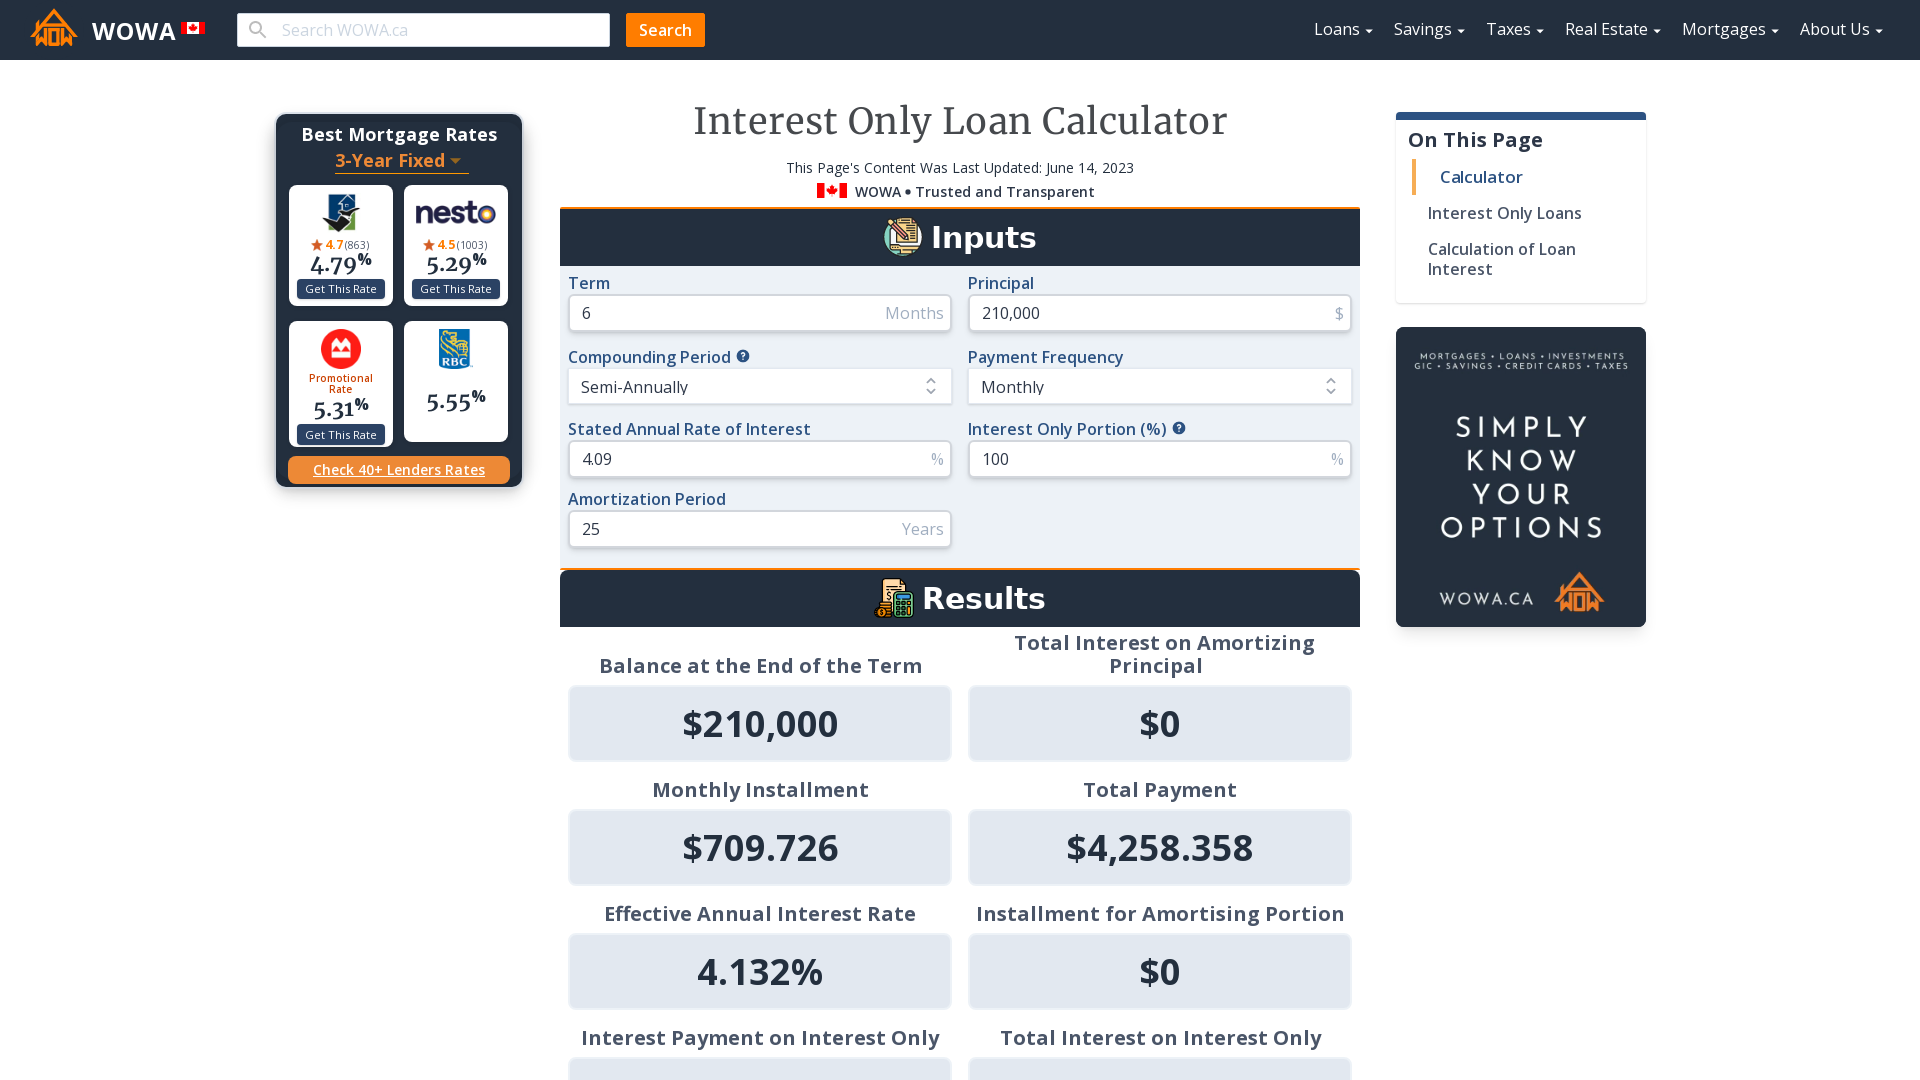
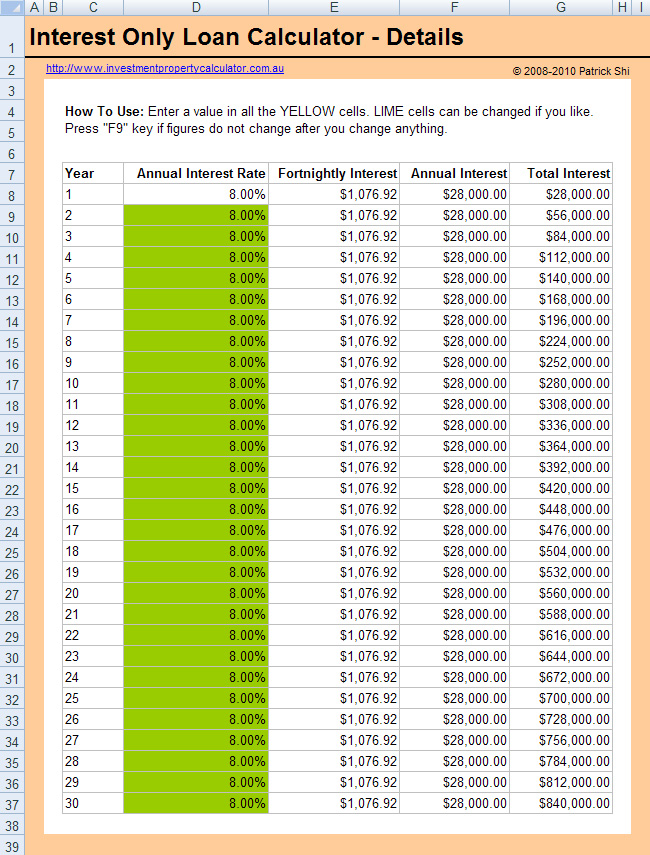
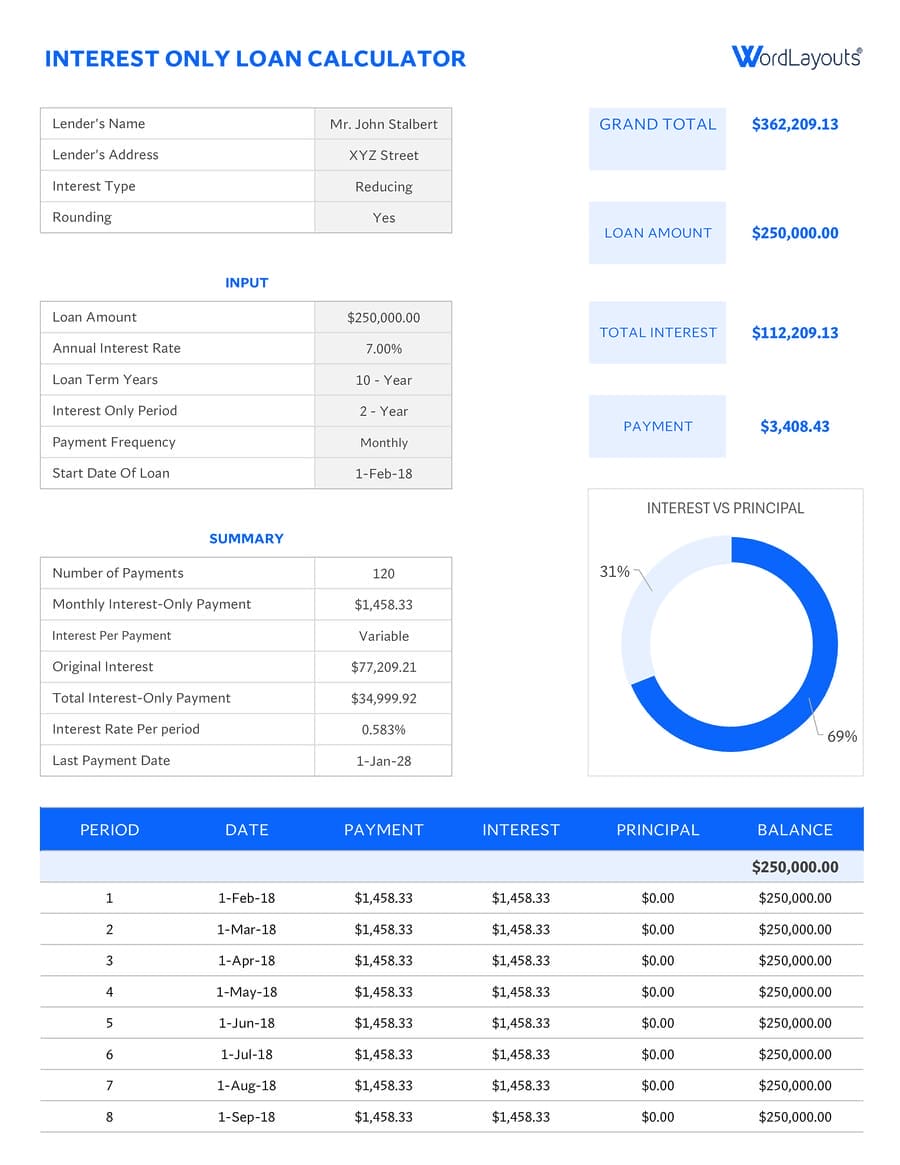
Most people don't realize an interest-only loan creates a weird payoff problem that standard calculators weren't built to handle. The loan balance stays flat for years while you make payments that cover nothing but interest. Then suddenly the balloon payment hits and the balance is exactly what it was at closing, plus whatever accrued during that period. A regular mortgage calculator will give you garbage numbers if you feed it an interest-only loan structure because it assumes principal is being paid down from day one. Here's what you need to know before you try to figure out your payoff number on your own.An Interest Only Loan Payoff Calculator needs to account for three distinct phases: the interest-only period where principal doesn't move, the amortization reset when the IO period ends, and any prepayment penalties or yield-maintenance clauses that lenders layer on top. Missing even one of those will throw your numbers off by thousands. First, get your exact loan terms in writing. Not the marketing brochure. The promissory note or disclosure statement. You need the start date, the IO period end date, the interest rate, the original principal balance, and any prepayment penalty structure. I once spent two hours trying to reconcile a payoff quote because the borrower had refinanced mid-IO period and the calculator was pulling data from the original loan, not the modified one. The difference was about $18,000 in missed principal adjustments. Make sure the calculator you're using is pulling current balances, not stale ones. The basic formula is straightforward: accumulated interest during the IO period plus any accrued daily interest since your last payment, minus any partial payments already applied, minus any prepayment discounts if your lender offers them. Then add the prepayment penalty if you're still inside the penalty window. Most lenders charge a penalty for paying off an interest-only loan early during the first few years — typically six months to a year of interest, though some use yield maintenance, which can be significantly more expensive.
When the IO period converts to a fully amortizing payment, the calculation changes entirely. Your new monthly payment is calculated on the remaining balance over the remaining term. If you're paying off early during this phase, you're dealing with an actual amortization schedule, which most standard calculators handle fine. The hard part is getting from your current date to the payoff date across that transition boundary.
Common Problems That Trip People Up
The biggest issue I see is people assuming their payoff quote is final. It isn't. Payoff quotes are good for about 30 days, sometimes less. Interest accrues daily. If your payoff quote came in March and you're trying to close in May, that number has probably moved. You'll need a fresh quote or you need to adjust for daily accrual yourself. Another thing that sneaks up: escrow shortages. If your loan has an escrow account for taxes and insurance, the payoff amount includes whatever surplus or shortage exists in that account. Lenders release the escrow after payoff, but sometimes there's a processing delay that creates a discrepancy between what you were told and what actually hits your account. I've seen this cause closings to fall through because the title company's final numbers didn't match the lender's earlier quote by a few hundred dollars. Prepayment penalties on interest-only loans are where people get hurt the most. Some lenders structure these as a percentage of the remaining balance. Others use a declining scale. A few use yield maintenance, which calculates the present value of all remaining payments at the current market rate. Yield maintenance can easily double what you'd expect to pay. Check your loan documents before you do any math. I had a client who thought she was saving $40,000 by refinancing early, and the yield-maintenance clause ate nearly all of it. She ended up paying more than she would have by just staying put for two more years.
Get the Full Details

What These Calculators Can't Do For You
No online calculator will tell you your exact payoff number. They can get you in the ballpark, usually within a few hundred dollars if your inputs are clean, but the final number has to come from your lender. The reasons are mechanical: daily accrual methods vary between lenders (some use 360-day years, some use actual/365), payment application ordering differs, and escrow accounting is lender-specific. If you're trying to decide whether to pay off early or refinance, a calculator can help you compare scenarios, but it won't factor in your tax situation. Interest-only loan payoff can have tax implications if you're deducting mortgage interest and paying off early reduces your deductible interest in the current year. That matters for high-balance loans where the deduction is significant. Run the numbers through a tax professional, not a spreadsheet. There's also the matter of loan modification or short sale scenarios. If you're behind and looking at a payoff as an exit strategy, the calculator becomes almost useless because the numbers depend entirely on what the lender is willing to negotiate. In those cases, you're dealing with loss mitigation, not simple payoff math. Get a loss mitigation specialist involved before you trust any online tool.
A Practical Way to Use This
Get your current payoff quote from your lender. Enter your loan details into an Interest Only Loan Payoff Calculator to see what the model gives you. Compare the two. If they're within a couple of hundred dollars, you're in good shape. If they're farther apart, dig into why — most of the time it's a date mismatch, an escrow difference, or a prepayment penalty the calculator didn't account for. Adjust your inputs accordingly and run it again. This process usually takes about 20 minutes and saves you from showing up at closing with a nasty surprise. Keep a copy of every payoff quote you receive. Date them. Lenders sometimes issue quotes with different assumptions depending on which department generates them. I've seen the same borrower get two quotes for the same loan on the same day that differed by over a thousand dollars because one included escrow adjustments and the other didn't. Having both lets you spot the discrepancy immediately instead of discovering it at the title company. When the IO period is ending and your payments are about to jump, run the numbers six months before the transition. The payment increase on a typical $400,000 interest-only loan at 6.5% converting to a 25-year amortization is roughly $2,600 per month. Knowing that ahead of time gives you a chance to refinance, extend the IO period if your lender allows it, or start saving for the higher payment without it catching you flat-footed. Waiting until the first new payment hits is too late for most of those options.