How to Actually Use an Interest Only Mortgage Calculator Without Getting Burned
An interest only mortgage calculator is a tool that tells you what your monthly payments look like during the interest-only period and how much will be left to pay afterward. It sounds straightforward until you realize most online versions leave out critical details like the balloon payment, the amortization shift, and the escrow components that actually show up on your annual statement. I spent years working with mortgage portfolios and ran into a specific problem last year that nobody warned me about. A client wanted to refinance their interest-only loan after the 10-year period was up. The calculator they had been using showed a clean monthly figure during the IO phase but completely ignored the fact that once the loan converted to a fully amortizing schedule, the principal portion would jump by roughly 340%. I had to manually recalculate the residual balance using the actual paid amortization table, not the simplified version the calculator produced. The workaround was pulling the original loan documents, noting the exact payoff date on the IO phase, and then running the remaining balance through a standard amortization formula instead of relying on the online tool's default assumption that the full term resets at 30 years.
Using an Interest Only Mortgage Calculator Correctly
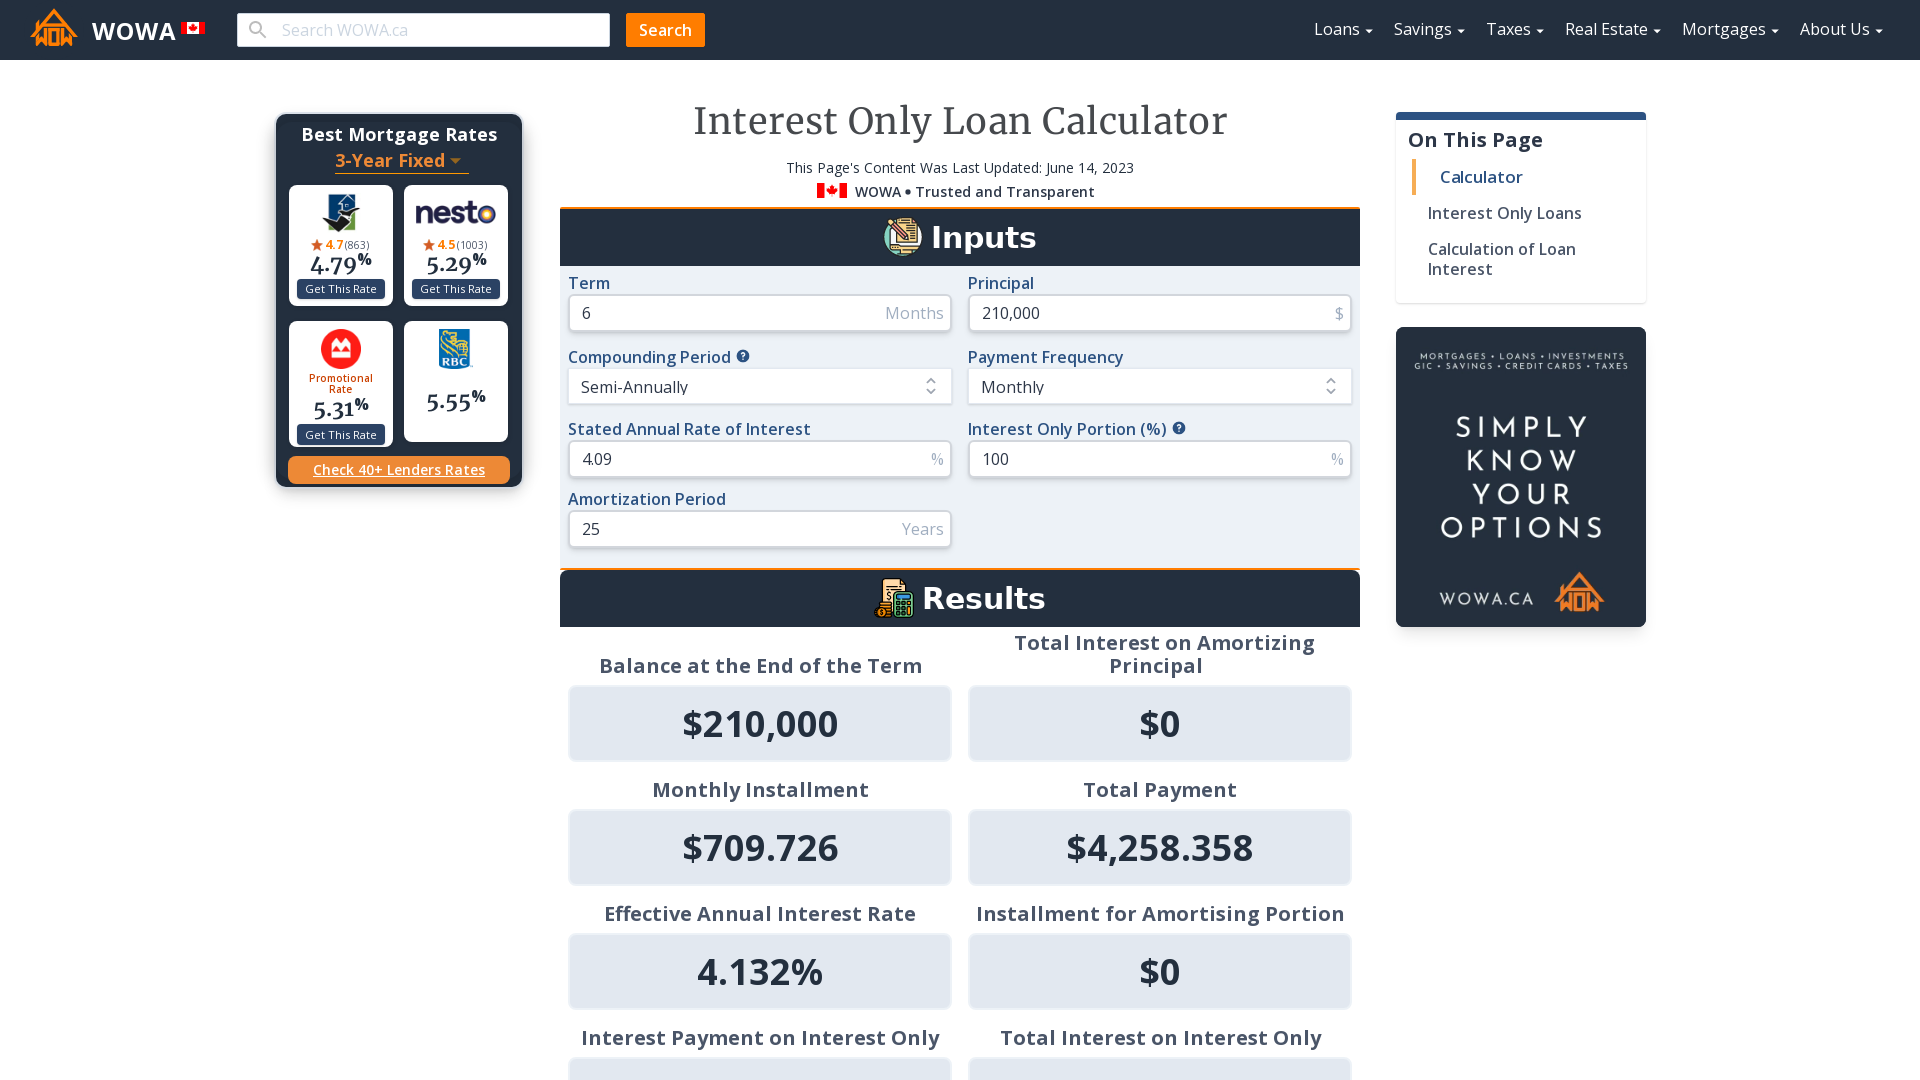
The basic inputs you need are the loan amount, the annual interest rate, the length of the interest-only period in years, and the total amortization period. Most calculators assume the total term is 30 years with the IO phase being a subset of that, but some loans have the IO period equal to the full term, which means you owe the entire principal at the end. You need to know which structure your loan follows before you enter anything. Here is the actual calculation path. During the interest-only period, your monthly payment equals the principal balance multiplied by the annual rate divided by 12. So on a $400,000 loan at 6.5% over a 10-year IO period, your monthly payment is $2,166.67. That number does not change. It stays flat because no principal is being touched. The calculator shows this easily enough. The part that trips people up is the post-IO phase. Once the interest-only period ends, the remaining balance stays the same but now it must be paid down over the remaining amortization period. If your original loan was a 30-year structure and 10 years have passed, you now have a $400,000 balance amortized over 20 years at the same rate. That payment jumps to roughly $3,038 per month. The difference between the two phases is where people get caught off guard financially.
I also want to flag something that most free calculators skip entirely. Escrow. Property taxes and homeowners insurance are typically rolled into the monthly payment even on interest-only loans. A proper calculator will ask for your annual tax bill and insurance premium separately and add one-twelfth of each to the total monthly figure. Without that, your real payment could be $400 to $800 higher than what the tool displays. I always tell people to run the numbers twice, once with escrow and once without, and keep both results visible when comparing lenders. Another nuance most calculators do not address is the tax deduction landscape. Interest paid during the IO period is fully deductible within current limits, which can make the effective cost of that phase lower than the stated rate for itemizers. Once the loan converts and you start paying principal, only the interest portion remains deductible. A spreadsheet with a tax-adjusted cost column will show you the real picture faster than any online tool can. If you are looking for a reliable Interest Only Mortgage Calculator, the most useful ones let you adjust the IO period length, the conversion date, and whether the remaining balance becomes due as a balloon or gets amortized. The cheap free versions usually assume one standard scenario and leave you guessing about the alternatives. A tool that lets you toggle between those options and shows side-by-side comparisons of each path is worth more than a dozen generic calculators.
Get the Full Details
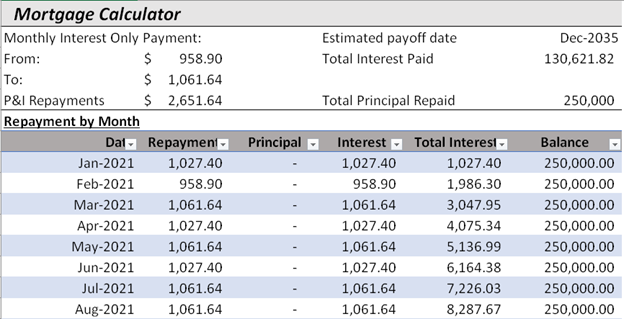
The real limitation of every interest-only mortgage calculator is that it cannot account for rate changes if you have an adjustable product. Some IO loans are tied to ARMs. The calculator will show you a static snapshot at the current rate, but if the rate adjusts after year three, every future payment shifts. The only way to model that is to build a projection with multiple rate scenarios and see how the payments accumulate under each one. I keep a simple spreadsheet template for this and plug in conservative, base, and aggressive rate assumptions. It takes about ten minutes to set up and saves you from signing a loan without understanding the worst-case monthly payment.
Common Pitfalls to Watch For
Lenders sometimes present the interest-only payment as the true monthly cost without clarifying that it will increase significantly later. A calculator can help you see through that, but only if you enter the full loan terms. Make sure you know the exact end date of the IO period and what happens automatically after that date. If the loan requires a new application or rate lock to convert, the process can delay the payment recalculation by several weeks, and you might get billed at the wrong amount temporarily. Another issue is the negative amortization trap on certain hybrid products. A few interest-only loans have a feature where if you do not pay the full interest due each month, the unpaid amount gets added to the principal. The calculator will not show this behavior unless you specifically model missed or partial payments. If you are in a situation where cash flow might be tight during the IO phase, run a scenario with a one-month payment delay and watch what happens to the balance and the subsequent payment amount. It often reveals a compounding effect that makes the next phase even more painful than expected. For most people evaluating whether an interest-only structure makes sense, the core question is not the monthly payment during the first few years but the payment after conversion and whether they can sustain it. I recommend calculating the post-conversion payment first and then determining if that amount fits comfortably within your budget before you even look at the interest-only phase. The early years are the easy part. The later years are where the math usually causes problems.