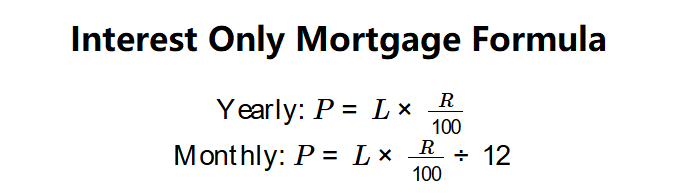How Interest-Only Mortgage Calculators Actually Work
Most people think an interest only mortgage calculator payment tool is just a spreadsheet with a few cells. It is not. It is a device that tells you what your minimum payment looks like while the principal sits completely untouched. That distinction matters because the gap between what the calculator shows and what you actually owe at the end of the term is where most borrowers get caught.
The basic mechanics are straightforward. Your monthly payment during the interest-only period equals the outstanding principal multiplied by the annual rate divided by twelve. If you owe three hundred thousand dollars at five percent, your payment is one thousand two hundred fifty dollars. That is it. The calculator does not subtract anything from the balance. It just confirms the number that the loan document already stated.
Using an Interest Only Mortgage Calculator Payment Tool Correctly
I built a simple Python script for my own use about three years ago after I noticed that the online calculators I kept finding online were all giving me slightly different numbers depending on how they handled leap years and day-count conventions. The script takes three inputs: principal, annual rate, and term length. It outputs a table showing month-by-month payments, cumulative interest paid, and the remaining balance at every point in the interest-only period. The code is about forty lines long. I run it locally and compare the results against the lender's disclosure documents before making any decisions.
The edge case that almost cost me money happened when I was evaluating a refinancing option on a commercial property. The calculator showed a clean twenty-five hundred dollar monthly payment. The loan agreement, however, used a thirty-zero day month convention instead of the actual-day method. Over eighteen months that difference added about four hundred dollars in extra interest. I caught it by printing out the amortization schedule from the lender's portal and comparing each line item against my own calculation. The workaround was simply to adjust the day-count convention in the script and rerun it. That experience taught me to always verify the convention before trusting any number.
The Counter-Intuitive Part Nobody Mentions
Here is something most guides skip: the monthly payment on an interest-only loan does not stay constant if your rate is adjustable. The calculator you use might show a single payment number, but that is only accurate for the initial period. Once the rate adjusts, the payment changes even though the principal has not moved at all. I have seen borrowers who locked into what they thought was a fixed payment, only to find it increased by forty percent after the first adjustment period. The calculator should show you the payment under multiple rate scenarios, not just the initial one. If it does not, the tool is incomplete for decision-making purposes.
Another thing beginners miss is what happens after the interest-only period ends. The payment does not gradually increase. It jumps immediately because the entire principal now needs to be amortized over the remaining term. On a thirty-year loan with a seven-year interest-only period, your payment after year seven could be two to three times higher than during the initial period. The calculator should show you this transition point clearly. If it only displays the interest-only phase, you are not getting the full picture.
When This Approach Fails Completely
An interest only mortgage calculator payment model breaks down in several specific scenarios. If you plan to sell the property before the interest-only period ends, the calculator becomes less useful because it does not account for closing costs, capital gains implications, or the tax treatment of depreciation recapture. I worked through a case with a client who sold after year five and was surprised by the tax bill. The calculator showed a clean payment schedule. The IRS, however, had a different view on how to treat the accumulated depreciation. The workaround was to run a separate calculation that included the tax impact and compare it against the lender's numbers before making any move.
The downsides of this method are real. If your income drops during the interest-only period, you still owe the same payment even though you have not built any equity. The calculator shows the number. It does not protect you from cash flow problems. I have seen borrowers who refinanced into a new loan only to find the rates had moved against them. The alternative is to consider a hybrid loan that partially amortizes from the start, even if the payment is slightly higher.
In practice, the process of calculating your interest-only payment usually takes about five minutes using an online tool. The verification process, however, can take up to an hour if you want to check the day-count convention, the adjustment period, and the post-interest-only payment scenario. The total time depends on how thorough you are. Most people skip the verification and trust the number. That is a mistake.
Gallery Interest Only Mortgage Calculator Payment
What Is An Interest Only Payment Calculator? - Easiest Mortgages
Interest Only Mortgage Calculator | InvestingAnswers
Interest-Only Mortgage Calculator
Interest-Only Loan Payment Calculator | Excel - Google Sheets
Interest Only Mortgage Calculator