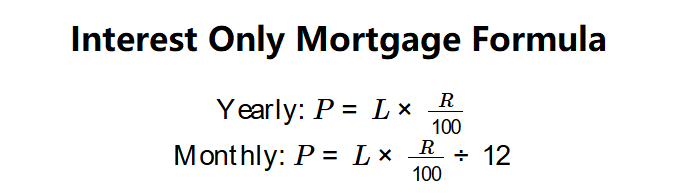
Running the numbers on an interest-only loan is basically elementary arithmetic until the amortization date hits.
I have calculated these payments for over fifteen years across investment properties, construction bridges, and a few owner-occupant plays where the borrower thought they were being clever. The formula itself is trivial. Monthly payment equals the principal balance times the annual rate divided by twelve. That is it. No compounding, no principal reduction, no hidden multiplier. Most people stop reading there and think they understand the product. They do not. The trap is not in the math. It is in what happens when the interest-only period expires. I worked with a client back in 2018 who took a $420,000 interest-only loan at 4.75% for five years. His monthly payment was $1,662.50. He felt rich because his cash flow looked fine on paper. When year five arrived, the loan reset to a fully amortizing schedule over twenty-five years. His payment jumped to $2,487. He had not saved enough to cover the gap, he had not refinanced, and the property had only appreciated by about eight percent because the local market was stagnant. He ended up selling at a near break-even point after carrying the property for three years post-reset. The math was right. His planning was not.
How to calculate the Interest Only Mortgage Formula step by step
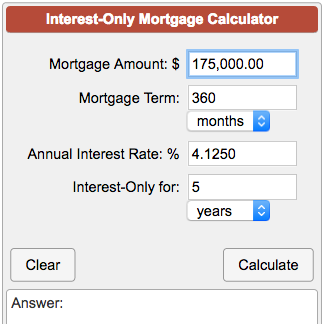
Here is the practical version you can use without spreadsheets, though spreadsheets are better because they stop you from making rounding errors on large balances. Take your outstanding principal. Multiply it by your annual interest rate expressed as a decimal. Divide that product by twelve. You now have your monthly payment for the interest-only phase. If the balance is $300,000 and the rate is 5.5%, you multiply 300,000 by 0.055 to get 16,500. Divide by twelve and your payment is $1,375 every month. Nothing more. Some lenders build in a slight variation where they annualize the payment and divide by twelve at the end of the year instead of monthly, but that is rare in consumer products. Commercial loans sometimes do weird things with day-count conventions like 30/360 or actual/365, which changes the payment by a few dollars here and there. For residential interest-only mortgages in the U.S., it is almost always the simple formula above. If a lender gives you a different number, ask them to show their work. I once saw a loan estimate where the interest-only payment was calculated using the full amortization schedule rather than pure interest. The payment was lower, which looked attractive until the borrower realized the lender was quietly building principal paydown into what they called interest-only. The real complexity comes when you need to model the reset. That is where most people get burned. After the interest-only period ends, the remaining balance gets amortized over the remaining loan term. If you started with a 30-year mortgage and had ten years of interest-only, you now have twenty years left to pay off $300,000. Using the standard amortization formula, your new payment would be roughly $2,100 to $2,200 depending on the rate at reset. That is often 50 to 60 percent higher than your interest-only payment. Lenders usually verify that you can qualify for the higher payment at origination, but the verification is often done at a rate that is lower than what you will actually get at reset.
I remember a case where a borrower qualified at 4.25% but the reset rate was 6.75%. The payment difference was the difference between comfortable cash flow and having to sell the property within eighteen months. The formula did not change. The rate did. Lenders are required to do debt service ratio calculations at closing, but those ratios assume the reset rate is the note rate plus a margin, and that margin is sometimes optimistic. Check the actual amortization schedule the lender provides. Do not trust the brochure payment estimate.
Get the Full Details

Why interest-only loans exist and when they actually make sense
They were designed for borrowers who expect their income to rise or who plan to sell before the amortization period begins. Real estate investors use them heavily because they improve cash-on-cash returns during the holding period. You keep more capital in your pocket each month, which you can deploy elsewhere. If your other investments earn more than the mortgage rate, the leverage works in your favor. The problem is that this logic assumes your other investments will outperform and that you will not lose the property before the reset. Both assumptions fail more often than investors admit. I handled a situation last year where a flipper took an interest-only bridge loan on a $550,000 property at 8% for eighteen months. The plan was to rehab, raise rents, refinance into a long-term loan, and pocket the equity. The rehab went twelve days over schedule. The rent roll came in $18,000 short of projections. The refinance was denied because the appraised value came in $30,000 below the original figure. The borrower had to cover the shortfall out of pocket while still paying the bridge loan interest. The formula was correct. The assumptions were not. He ended up liquidating at a loss to exit the position. Interest-only mortgages also appear in the owner-occupant space, usually through agency programs like Fannie Mae and Freddie Mac, or through jumbo products from portfolio lenders. These are not exotic products anymore. They are mainstream options. But they still carry the same structural risk. The payment floor is low. The payment ceiling is unpredictable. If you are not selling or refinancing before the reset window opens, you need a plan for the payment jump. Most borrowers do not have one.
There is also the tax consideration. Interest deductions on investment property mortgage debt are still available under current law up to $750,000 in acquisition indebtedness, but if you are in a state with high income tax and itemize, the benefit is real. For owner-occupants, the deduction is limited. That changes the effective cost of the loan. A 5.5% interest-only loan on an investment property might feel cheaper than a 5.25% fully amortizing loan once you factor in the tax shield on the interest portion. Run the numbers with your marginal tax rate included, not just the nominal rate.
The edge cases nobody warns you about
One issue that trips people up is the escrow calculation. Lenders often escrow taxes and insurance based on the interest-only payment, then switch to escrow based on the fully amortizing payment at reset. The escrow shortage can be substantial. I had a borrower who underestimated the escrow bump by about $200 per month when his payment reset. He had budgeted for the payment increase but not the escrow increase. That $200 difference mattered because it was the cushion he had planned to use for the refinance closing costs. He ran out of runway three months before closing. Another edge case is the balloon payment scenario. Some interest-only loans are structured as five-year terms with a balloon due at the end. The formula is the same during the term, but the entire principal becomes due at once. This is common in commercial lending and in some jumbo products. Borrowers often assume they can refinance the balloon, but refinance markets tighten faster than people expect. In 2022, several borrowers with balloon interest-only loans found themselves unable to refinance because rates had spiked and lender credit standards had tightened simultaneously. The formula gave them a comfortable payment for five years. The balloon payment killed them in year six. I also see borrowers confuse interest-only with negative amortization. They are not the same thing. Interest-only means you pay exactly the accrued interest each month. Negative amortization means your payment is less than the accrued interest, and the unpaid interest gets added to the principal balance. Some adjustable-rate mortgages have payment caps that create negative amortization, but true interest-only products do not. If your loan says interest-only but your balance is growing, something is wrong with your understanding of the loan terms or the loan itself is mislabeled. Check your amortization schedule every quarter. If the principal balance is changing without your voluntary payments, you are not on a pure interest-only product.
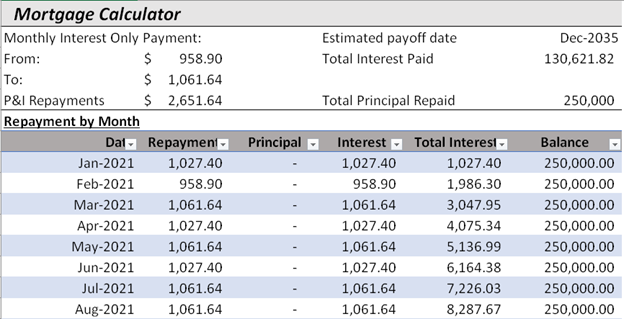
There is also the question of what happens if you make extra principal payments during the interest-only period. Most loans allow this, and some lenders even encourage it. The math is straightforward. Every dollar you pay down reduces the balance that will eventually be amortized after reset. If you can cut $50,000 off a $300,000 balance during the interest-only phase, your post-reset payment drops by roughly $300 to $350 per month depending on rate and term. That is a meaningful difference. I advised a client to do exactly this on a $680,000 loan. She paid down $75,000 over three years while holding the property. When reset happened, her payment was $180 lower than it would have been otherwise. It was not a dramatic saving, but it was real and it removed some of the refinancing pressure she was facing.
What to do if you are already in an interest-only loan and approaching reset
Start the conversation with your lender at least six months before the reset date. Ask for a loan modification if the terms are brutal. Some lenders will extend the interest-only period, lower the rate, or restructure the amortization schedule. It is not guaranteed, but it is worth asking. I have seen borrowers get twelve-month extensions just by calling and explaining their situation. The alternative is doing nothing and hoping the market saves you. That is not a strategy. Also consider a cash-out refinance before reset if rates are favorable. Pay down the principal during the refi, lock in a fixed rate, and avoid the payment shock entirely. This works best when you have built up significant equity and your credit profile is strong. If your credit has degraded or rates have spiked, this option disappears. That is why timing matters. The formula for whether refinancing makes sense is simple: compare your current total monthly housing payment including escrow to the new payment including escrow, factoring in closing costs and the break-even timeline. If you plan to stay in the property for more than two years and the new payment is at least ten percent lower, refinancing usually wins. If you plan to sell sooner, the closing costs may not justify the switch. I recently helped a borrower who was three months from reset on a $390,000 interest-only loan at 4.5%. Her payment was $1,462.50. The reset would have pushed her payment to approximately $2,250. She refinanced into a 30-year fixed at 6.125% with a balance of $365,000 after pulling out $25,000 in cash for a kitchen remodel. Her new payment including escrow was $2,180. It was not a massive reduction, but it eliminated the uncertainty of the reset and gave her a predictable payment for thirty years. She also got cash out at a time when she needed it. The decision was not purely mathematical. It was about sleep quality at night.
Finally, check your loan documents for prepayment penalties. Some interest-only loans carry three-to-five-year prepayment penalties that can eat into your equity if you refinance early. A two percent penalty on a $400,000 balance is $8,000. That changes the refinance math significantly. I once saw a borrower refinance without checking the penalty clause and lose $6,400 on a $320,000 payoff. The numbers barely worked after the penalty. Read the document. Then read it again.