How Interest Only Payments Actually Work
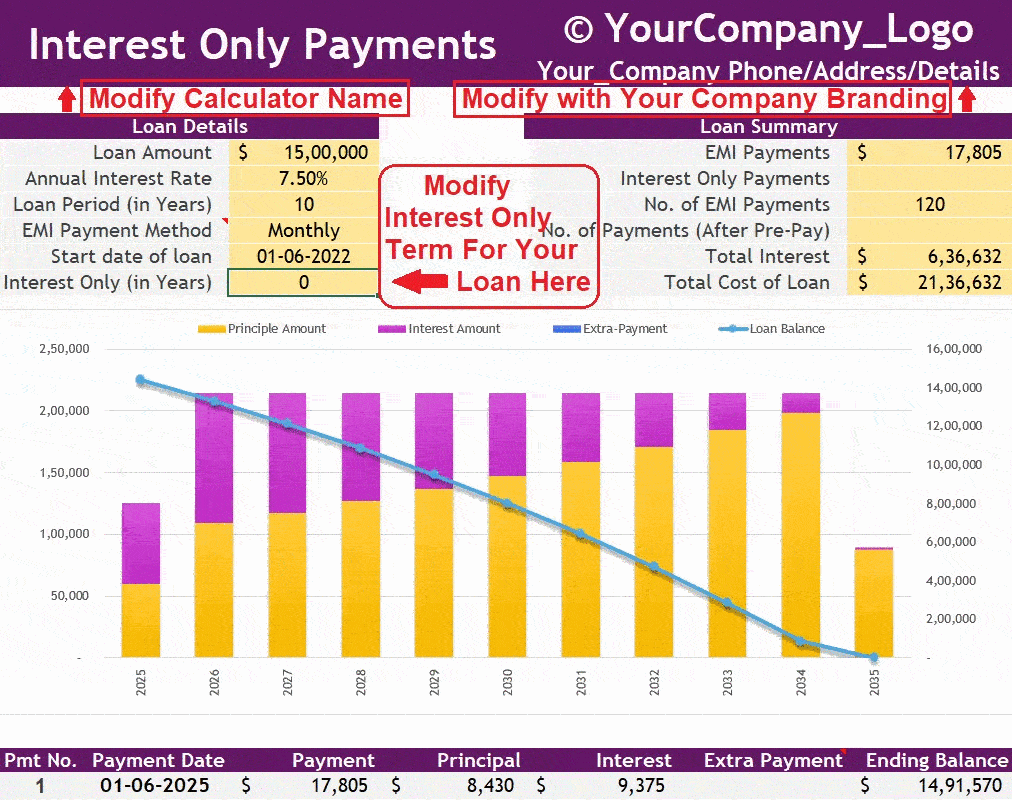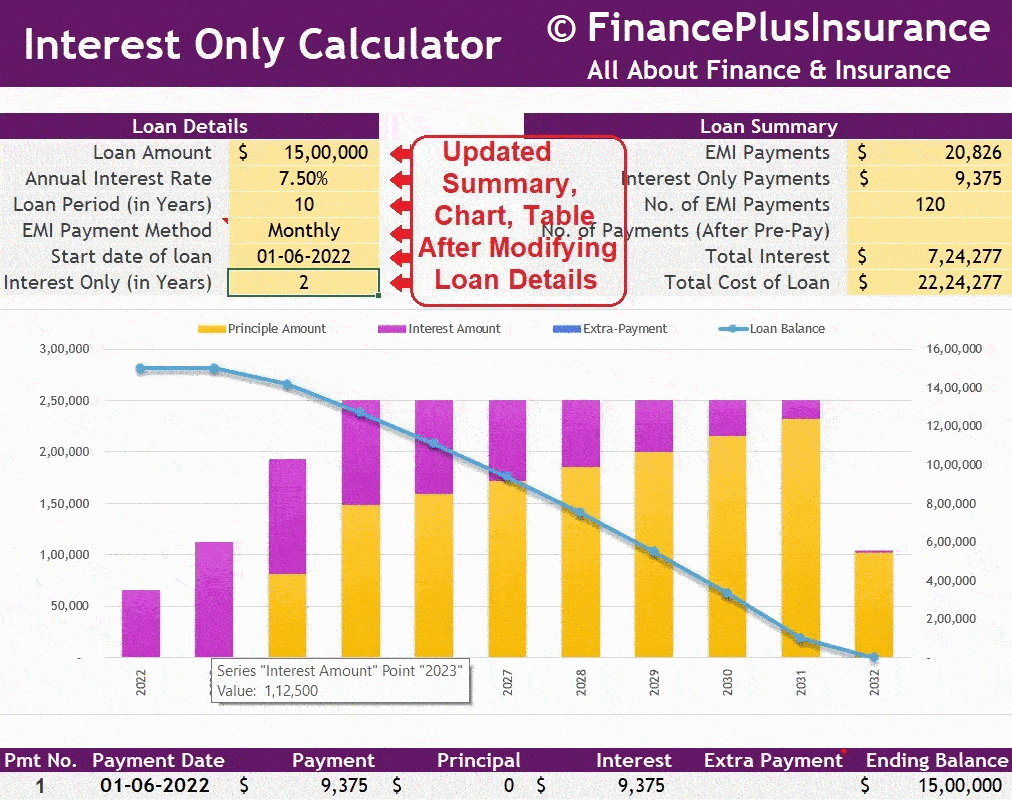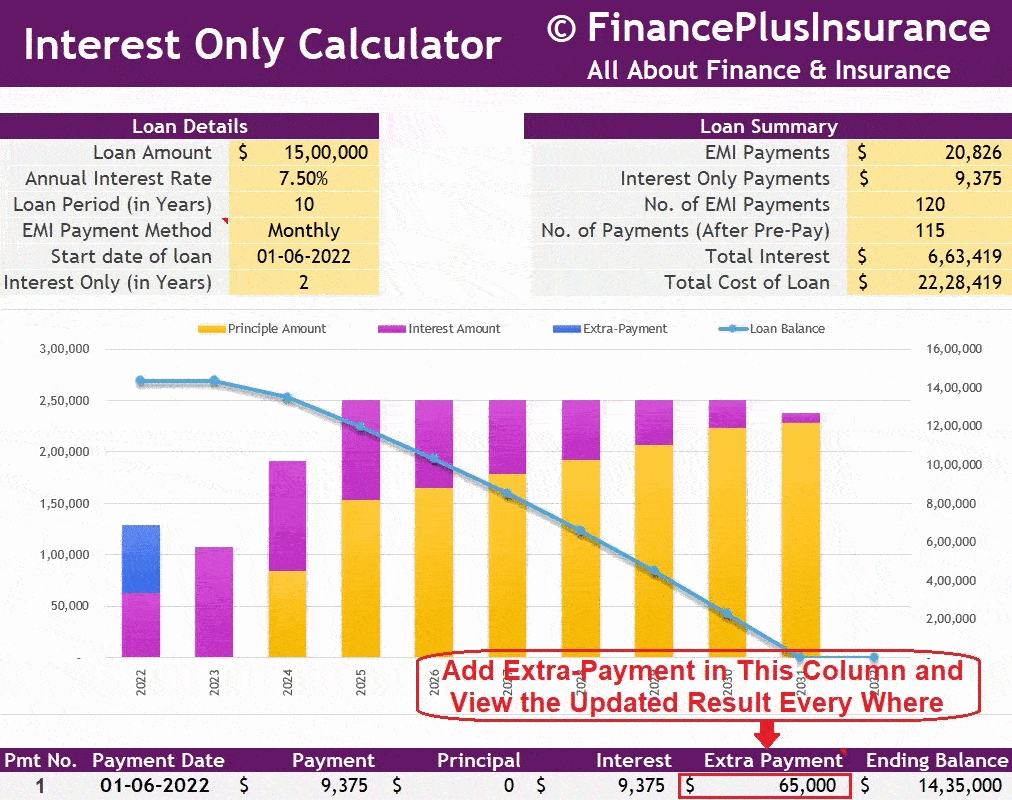
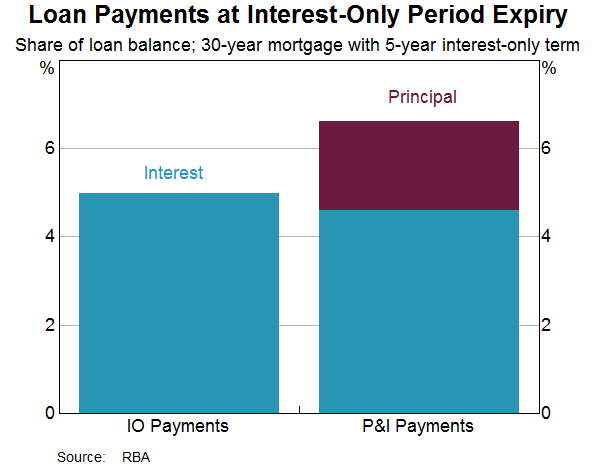
I see people get tripped up on this all the time, usually when they're trying to figure out what their monthly payment will look like on an investment property or a construction loan. The concept itself is straightforward enough, but the way lenders structure it and the hidden costs that show up later are where things get messy. With Interest Only Payments, your monthly payment during the interest-only period covers only the interest portion of the loan. Principal stays untouched. That means after the interest-only period ends, your payment jumps significantly because you now have to start paying down principal on the full original balance. A lot of borrowers don't factor that in before signing.
Interest Only Payments Explained
The calculation is simple arithmetic. Take your loan amount, multiply by your annual interest rate, then divide by 12. If you have a $500,000 loan at 7% interest, your monthly interest-only payment is $2,916.67. During the interest-only period, which typically lasts 5 to 10 years depending on the loan type, that payment stays exactly the same. After that period, the loan usually recalculates on a standard amortization schedule over the remaining term, so a 30-year loan with a 7-year interest-only period would switch to principal-plus-interest payments over the remaining 23 years. Here's what most people miss though. The interest is calculated on the full original balance the entire time. If you had applied even $100,000 toward principal during those first 7 years, you'd have saved roughly $14,000 to $18,000 in total interest over the life of the loan, depending on the rate and term. You're not locking anything in unless you actually make extra payments. I worked with a client last year who took out an interest-only commercial line on a multi-family property she was rehabbing. She assumed her monthly payments would stay low while she renovated and flipped it. The problem was the interest-only period was only 5 years, and the property hadn't sold by month 58. When the payment recalculated, her monthly obligation went from about $4,200 to roughly $7,800 because the entire $620,000 balance was still outstanding and now needed to be amortized over the remaining 25 years. She had to refinance into a different product and pay a $12,000 origination fee just to avoid defaulting. The lesson here is that interest-only structures are fine if you have a concrete exit strategy, but they punish people who just assume things will work out.
There are also some less obvious mechanics worth knowing. In some loans, particularly adjustable-rate interest-only products, your rate can reset during the interest-only period itself. That doesn't change the fact that you're only paying interest, but it changes how much interest you're paying month to month. A half-percent rate increase on a $400,000 balance adds about $167 to your monthly payment, which compounds poorly when you still haven't built any equity through principal reduction. Another thing nobody warns you about: property tax and insurance escrows. Most lenders require those to be included in your monthly payment even during the interest-only phase. On a $500,000 loan in a high-tax area, your actual monthly outflow might be $3,600 instead of the $2,916 payment you calculated, and nobody highlights that difference in the initial marketing materials. Factor it in before you commit. For rental properties specifically, there's a useful tactical angle. If the property cash-flows positively during the interest-only period, you can use the tenant's rent to cover the payment and still come out ahead on paper. But the math only works if vacancy stays below 10% and maintenance costs don't spike. I've seen landlords count on rental income to service interest-only debt and get blindsided when a unit went vacant for four months during a rate reset. Always underwrite the worst-case vacancy scenario, not the best case.
Get the Full Details

If you're considering an interest-only structure, the practical recommendation is to run the numbers for the post-interest-only payment at least three different interest rate scenarios, then check whether you could afford the higher payment even if your income dropped by 20%. Most people skip that exercise and regret it when the balloon hits.