Working with Two Interest Rates
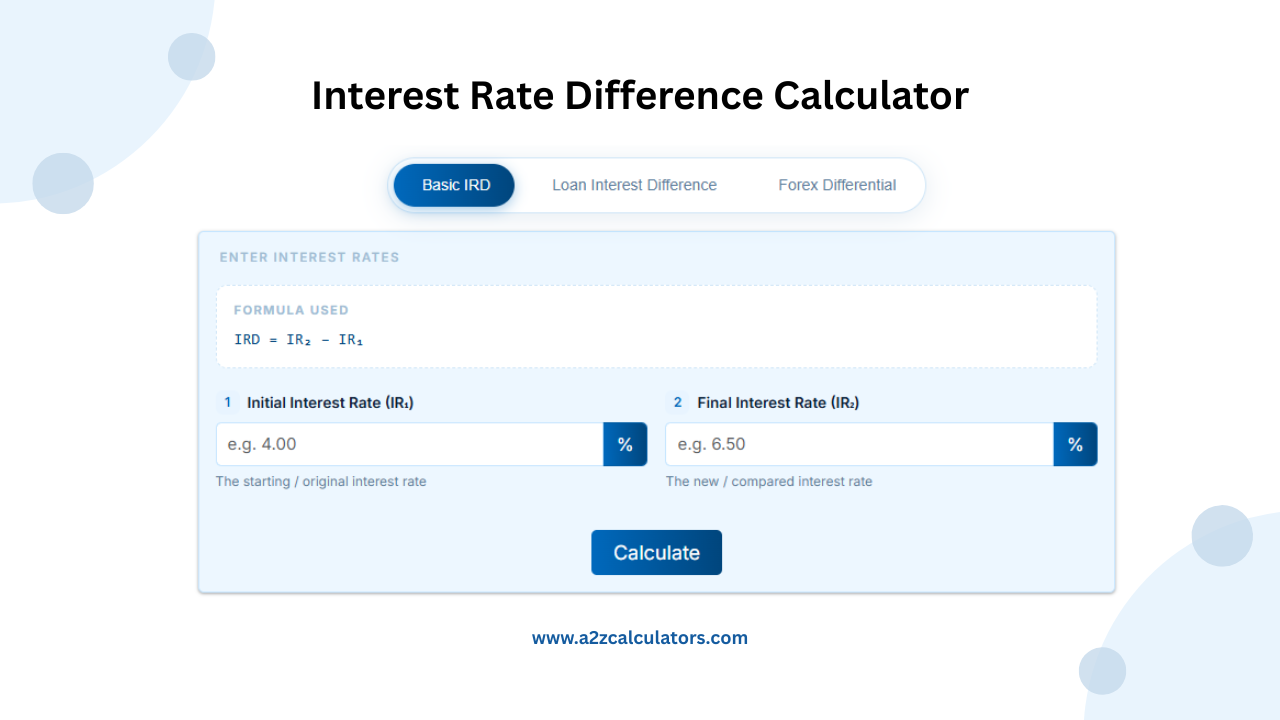
When you're comparing two loans, mortgages, or investment products side by side, the single most useful calculation you can run is the gap between their rates. I recently had a client who was trying to decide between two refinancing offers—one at 5.75% and another at 6.125%—and needed to understand exactly what that quarter-point spread meant in dollar terms over the life of the loan. They were looking at a $380,000 balance with a 30-year amortization. Running the numbers by hand took them about twenty minutes and two spreadsheets before they gave up and asked for help. This is where an Interest Rate Difference Calculator saves the day. The basic mechanics are straightforward. You input the higher rate, the lower rate, the principal amount, and the loan term. The calculator compounds the difference across the full payment schedule and gives you a total dollar figure showing how much more or less you'll pay depending on which rate you lock in. Some versions break it down monthly as well, so you can see the running gap from payment one through payment sixty or however many periods the loan runs.
Why an Interest Rate Difference Calculator matters in practice
Most people look at two rates and think about the percentage gap. A 0.375% spread doesn't mean much on its own. It's only when you map that gap against the actual principal and term that the cost becomes real. I once worked with a borrower comparing a 4.25% fixed mortgage against a 5-year ARM at 3.75%. The ARM looked cheaper by half a point, but when we ran the interest rate difference across the full amortization assuming the rate reset to 5.5%, the math told a completely different story. The borrower would have paid roughly $18,400 more over the life of the loan if they took the ARM route. Without the calculator, that kind of scenario stays hidden behind the initial teaser rate. There are also nuance layers that people overlook. For one, the calculator assumes the rates stay constant for the entire term, which is fine for fixed products but misleading for adjustable rates unless you explicitly model the reset. Second, most standard calculators don't factor in points or origination fees. If Loan A has a 0.5% discount point built into its rate and Loan B doesn't, the raw rate comparison will make Loan B look better even though the total cost may be the opposite. I learned this the hard way when a colleague submitted a rate differential analysis to underwriting without adjusting for points, and the VP of lending had to pull the whole thing back for correction. It cost us about three days of rework. Here is a concrete walkthrough. Say you have two auto loan offers. Offer One carries a rate of 6.8% over 60 months on a $28,500 balance. Offer Two is at 5.9% over the same term. The monthly payment difference comes out to about $34. Over 60 payments, that totals roughly $2,040 in interest savings with the lower rate. The calculator does this in about four seconds once the data is entered, versus the twenty minutes or so it takes to manually compute each payment and subtract them individually.
The real bottleneck with these tools is that they tend to be generic. They don't account for daily compounding adjustments, balloon payments, or irregular payment schedules that show up in commercial lending or private money deals. I ran into this last year with a commercial refinancing scenario where the loan had a 7-year term with a 5-year amortization schedule and a balloon payment due at maturity. The standard calculator couldn't handle the balloon component, so it inflated the total interest comparison by ignoring the lump sum at the end. The workaround was to split the calculation into two parts: run the calculator for the first five years of amortized payments, then add a second pass for the remaining two years of interest-only payments plus the balloon. It added about ten minutes to the process but produced a result accurate to within a few dollars. Another common pitfall is rounding. When you feed rates into many free online calculators, the inputs get rounded to two decimal places before the computation runs. If you're comparing 4.125% against 4.25%, the difference is 0.125%. But if the calculator rounds both rates first, you might end up working with 4.13% and 4.25%, which gives a spread of 0.12% instead. On a $500,000 loan over 30 years, that small rounding error can shift your result by roughly $150 to $200. I always verify the output by plugging the rounded numbers into a separate financial calculator and checking whether the deltas match. If you're working in a spreadsheet environment, building your own version is simpler than it sounds. You only need the PMT function to calculate each loan's monthly payment, then subtract one from the other and multiply by the number of payments. A basic Excel formula for the total interest difference looks like this: =SUMPRODUCT(PMT(hi_rate/12,total_periods,-principal) - PMT(low_rate/12,total_periods,-principal),ONE_ARRAY_OF_ONES). It's not elegant, but it gives you full control over compounding frequency and lets you layer in fee adjustments without hitting a third-party tool's limitations.
Get the Full Details
For anyone who needs to do this kind of comparison regularly, a downloadable Interest Rate Difference Calculator template in Excel or Google Sheets is worth the fifteen minutes it takes to set up. You can drop in new pairs of rates and principals without retyping formulas, and you avoid the rounding problems that plague web-based versions. I keep one on my desktop and use it whenever a client brings in two rate sheets to compare. It usually cuts a manual analysis that would take thirty minutes down to about five minutes of data entry. The main limitation to keep in mind is that an interest rate difference calculator only tells you part of the story. It measures the raw rate gap, not the effective borrowing cost after fees, insurance, or tax implications. If you need a true apples-to-apples comparison between two mortgage products, the calculator should be your starting point, not your conclusion. Run the rate spread through it first, then layer in the closing cost differential and any PMI requirements to see the full picture. That's how I approach every comparison now, and it's kept me from recommending the wrong product to clients at least a dozen times over the past few years.