How multi-curve actually works in practice
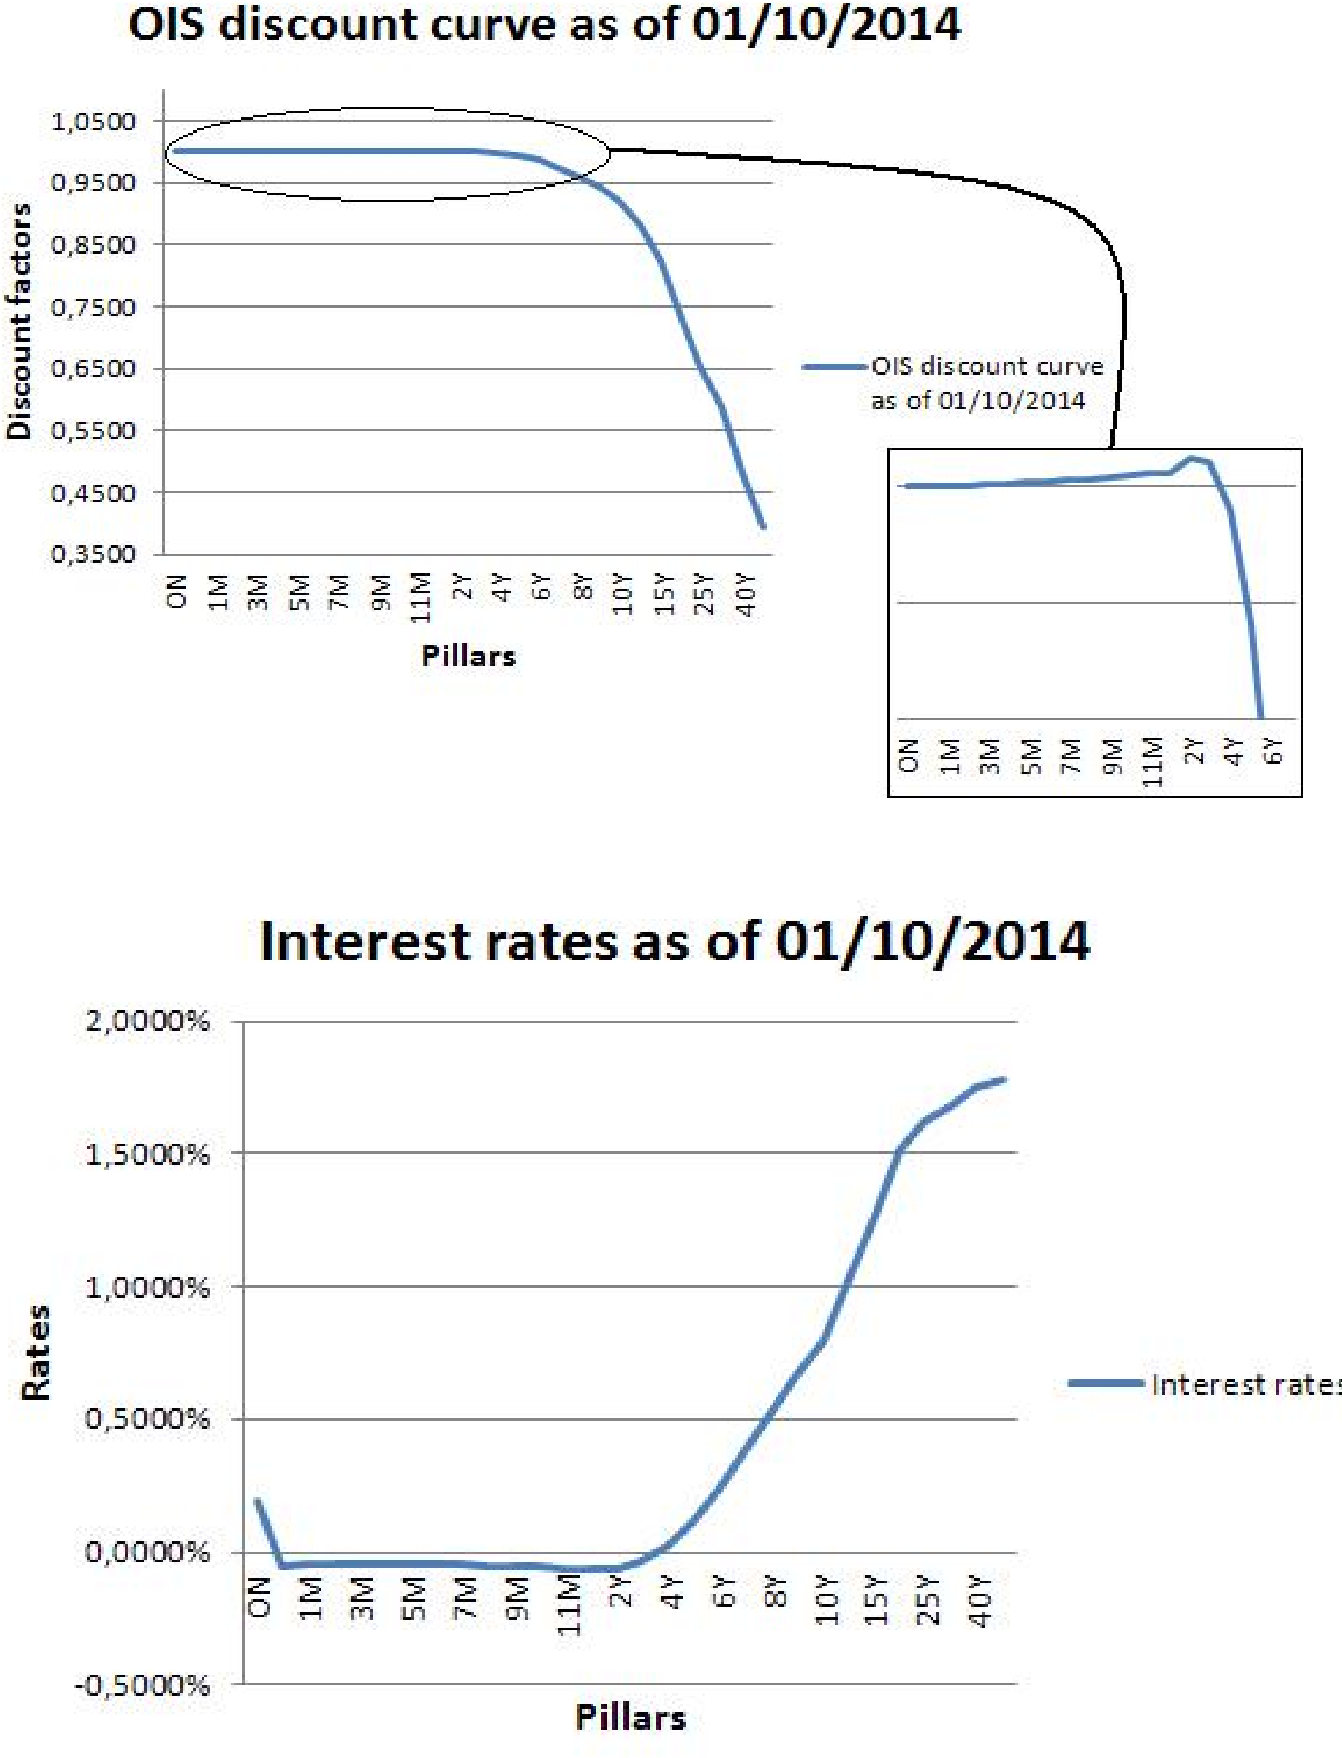
The shift from single-curve to multi-curve happened because LIBOR stopped being reliable during the financial crisis, and nobody had anticipated the downstream consequences when rebuilding models on top of that assumption. Before 2008, people used one discount curve for everything. Afterward, they realized that funding costs diverged from forward rates, and you needed separate curves for discounting versus projection. This is not theoretical anymore. It is the baseline every institution uses, even if some still hide behind a single curve for certain products. The mathematical core is straightforward: the discount factor comes from OIS-linked swaps, while the forward rate comes from LIBOR or SOFR-linked swaps. The two curves are built independently using bootstrap procedures, and the difference between them is the spread that embeds counterparty credit risk. That spread is what traders call the basis. If you ignore it, your valuations will be off by basis points across every interest rate product you touch. During the crisis, the spread between LIBOR and overnight indexed swap rates exploded. Traders noticed their models produced mispricings, especially on longer tenors, because the model assumed a single curve could handle both discounting and forward rate estimation simultaneously. The fix was to decouple them. You now have a discount curve derived from OIS swaps and a forwarding curve derived from LIBOR futures and swaps. Cross-currency basis swaps add a third curve when you are dealing with non-USD currencies.
I worked on a cross-currency basis desk around 2012 when the EUR/USD basis spread blew out to negative 80 basis points. The standard textbook approach would have you borrow at LIBOR and swap to OIS. That broke immediately because the basis was too large to hedge cost-effectively with a single instrument. We ended up using a three-curve framework with a Fed Funds curve, a LIBOR curve, and a basis adjustment layer between them. The workaround involved fitting a piecewise linear spread function between the two curves rather than trying to bootstrap through the basis directly. It was messy but accurate enough for P&L attribution, which is the real requirement.
Curve construction step by step
Start with the shortest tenor. For the discount curve, use OIS rates. Bootstrap them sequentially from overnight to ten-year maturities. Each segment depends on the previous ones, so any error propagates forward. For the forwarding curve, start with futures prices for the near term, then switch to swap rates for longer tenors. The transition point matters. If you use futures past six months, the convexity adjustment becomes significant and you need to apply it before bootstrapping. A common mistake is assuming the forward curve and discount curve share the same tenor structure. They do not. The discount curve is built from overnight-based instruments while the forwarding curve is built from tenor-specific instruments. Mixing them up will produce wrong present values, especially on exotics where cash flows land at odd dates. I have seen traders miss this on CMS products, where the fix date and payment date differ by a quarter. The discrepancy was small on vanilla swaps but massive on option pricing.
Get the Full Details

Implementation details that matter
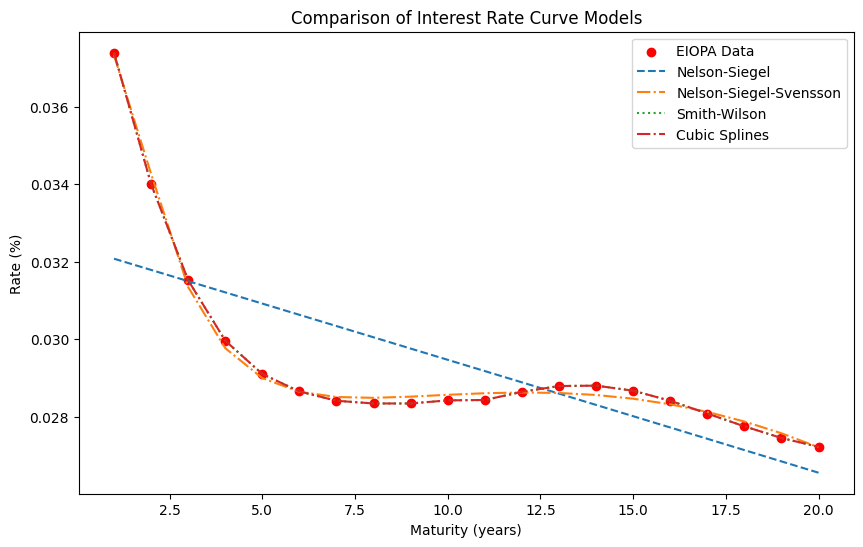
The first thing you need is a robust bootstrapping engine. Do not write your own unless you enjoy debugging numerical instability at 2 AM. Use an established library like QuantLib and extend it. The library handles the basic curves but does not implement cross-currency basis adjustments out of the box. You will need to add that yourself. When building the bootstrap, iterate until convergence. Linear interpolation between tenors is standard for the short end, but switch to cubic spline or forward-rate interpolation for the long end. A linear interpolation on a ten-year curve will introduce artifacts that show up in spread sheet calculations. The artifact is subtle. Your P&L attribution will not match because the curve behaves differently under parallel shifts versus twist scenarios. This is not a small issue. It cost my desk roughly 15 thousand dollars in mispriced trades during one quarterly reconciliation before we switched interpolation methods.
What people get wrong
The biggest misconception is that multi-curve means more accuracy. It means more complexity. If you are pricing a plain vanilla interest rate swap, the difference between single-curve and multi-curve pricing is maybe one or two basis points after the crisis adjustment. For most retail or smaller institutional desks, that difference is noise. The framework matters most when you are dealing with products that span multiple tenors or currencies, like cross-currency basis swaps, CMS spreads, or structured notes with embedded options. Another trap is using the wrong day count convention on one of the curves and not noticing. The OIS curve typically uses Actual/360 or Actual/365 depending on the currency. The LIBOR curve uses the tenor-specific convention. If you mix these up during bootstrap, the error compounds over time and becomes indistinguishable from market noise until you calibrate against a large set of derivatives. By then, debugging is expensive.
The basis swap layer
Cross-currency basis swaps are the glue that holds the multi-curve framework together. Without them, you cannot convert one currency's OIS curve into another currency's funding curve. The basis spread reflects liquidity premiums and regulatory constraints, not just credit risk. After Dodd-Frank and Basel III, the basis widened structurally because banks had to hold more capital against uncollateralized exposures. This is not a temporary distortion. It is the new normal. In practice, you extract the basis from the market by observing the spread between the two currencies' OIS rates embedded in cross-currency swaps. You then feed that spread into your model as a basis adjustment layer. The adjustment applies to every cash flow conversion between the two curves. If you skip this step, your valuation will be systematically biased toward the cheaper funding currency.
Model limitations you should know about
Multi-curve frameworks assume that basis spreads are stable enough to bootstrap from observed data. They are not always stable. During periods of market stress, basis spreads can widen by dozens of basis points in a single day. A curve built on calm market conditions will produce stale valuations under stress. This happened in March 2020 when COVID hit and LIBOR-OIS spreads spiked again. Models that relied on pre-crisis calibration produced garbage outputs for about two weeks until traders rebuilt the curves from fresh data. There is also the problem of negative rates. The multi-curve framework was designed for positive rate environments. When central banks pushed rates below zero, the bootstrap algorithms started producing nonsensical results because overnight rates could not go meaningfully lower than the policy floor. The workaround is to impose a floor on the discount curve or switch to a shifted-lognormal framework for the short end. Neither solution is elegant. Both are necessary.
A practical implementation checklist
First, ensure your data sources cover both OIS and the relevant LIBOR or alternative reference rates. Second, validate your bootstrap against known market prices before deploying. Third, implement a convexity adjustment for futures-to-swap transitions. Fourth, test your model against both parallel shifts and curve twists to check for interpolation artifacts. Fifth, document which day count conventions apply to each curve. Sixth, run a comparison between single-curve and multi-curve outputs on a standard product to understand the magnitude of the adjustment. Seventh, set up automated revalidation on a daily basis so you catch stale curve data before it affects trading decisions. The multi-curve framework is not glamorous. It is engineering work. The people who do it well are the ones who spend their time debugging interpolation schemes and validating against market data rather than writing fancy papers about stochastic volatility. If you want to build something that works, start with the data, validate aggressively, and accept that the model will never be perfect. It just needs to be good enough to price the book without embarrassing you during a risk review.