Getting Your Head Around Interest Rate Swaps And Their Derivatives
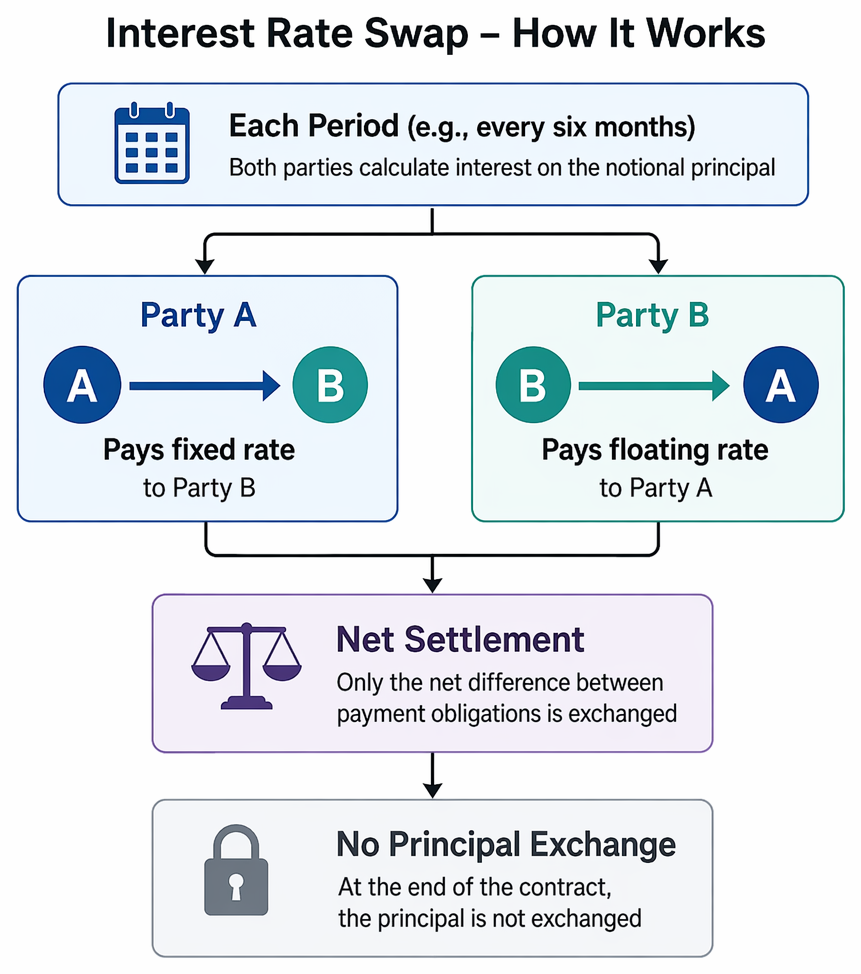
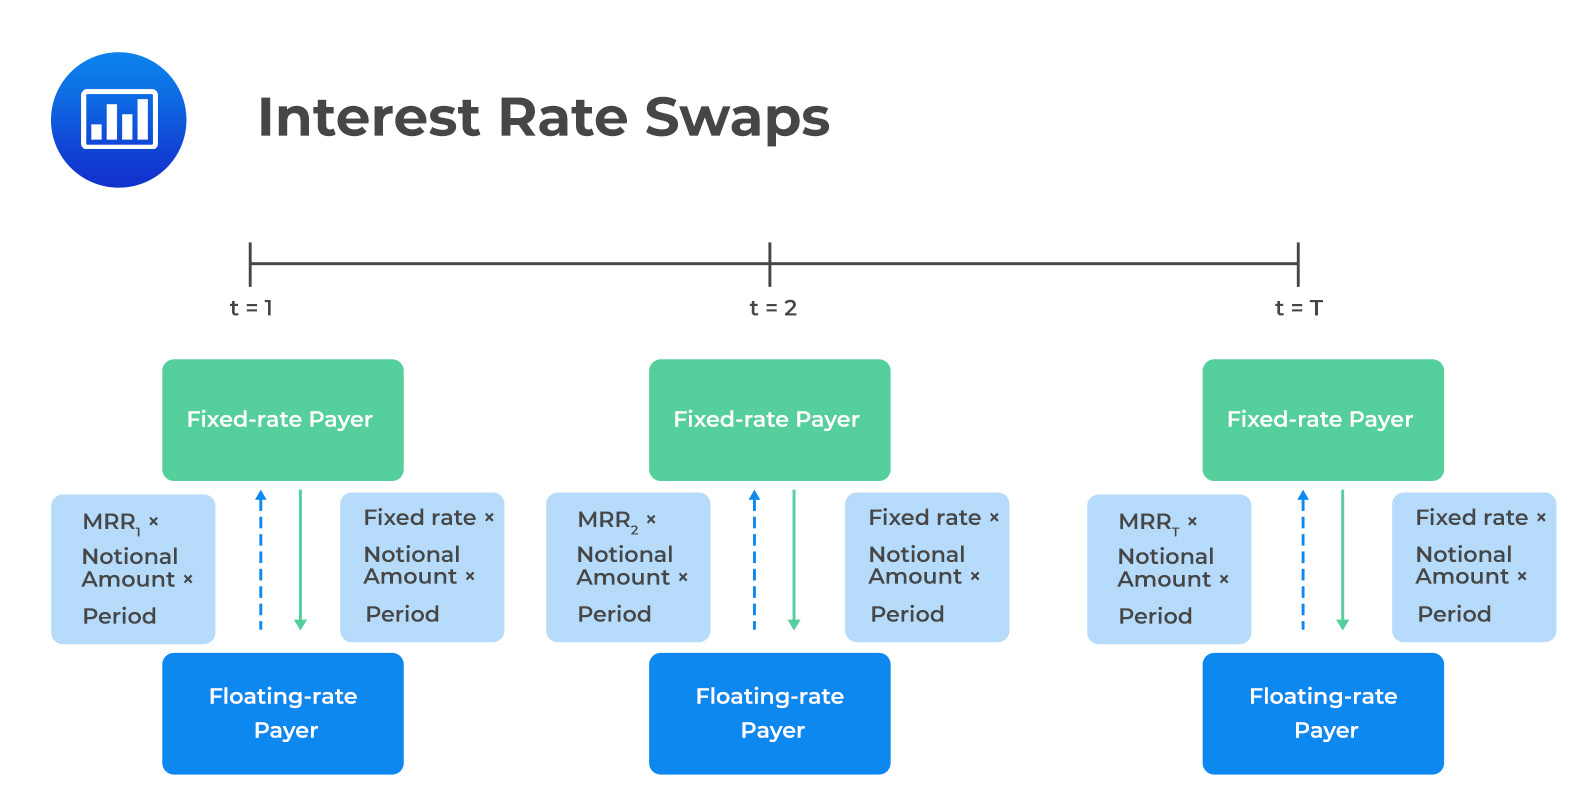
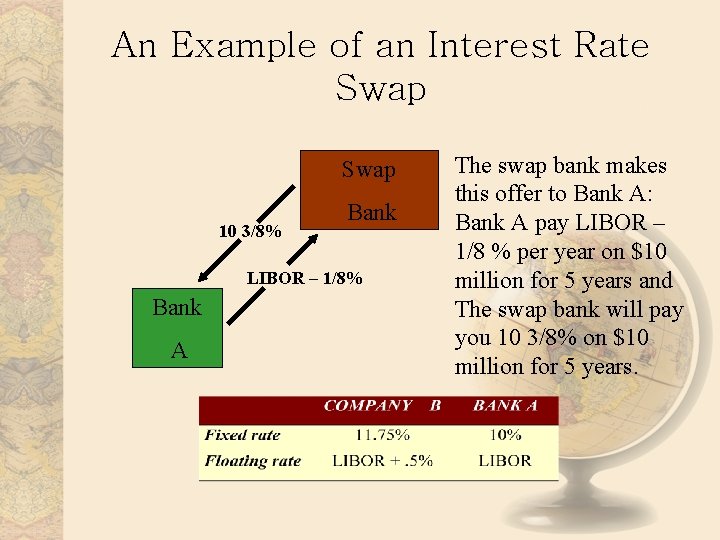
Most people think swaps are complicated until they actually sit down and map out the cash flows. Then it's just arithmetic with more steps than usual. I've been dealing with these instruments since the early 2000s, and honestly, the concept hasn't changed much. What changes is the market structure around them and how clearing works. An interest rate swap is an agreement where two parties exchange interest payment streams on a notional principal amount. One party pays fixed, the other pays floating. The notional never actually changes hands. You just settle the net difference between what each side owes. That's the entire mechanism. Everything else builds on top of that basic exchange.
Interest Rate Swaps And Their Derivatives
The derivatives built off swaps fall into a few categories. There are swaptions, which give you the right to enter into a swap at a future date. You'd buy a payer swaption if you think rates are going up and want the option to lock in a fixed rate later. Receiver swaptions work the opposite way. Then there are swap futures, which are standardized contracts traded on exchanges. They're less flexible but way easier to trade because you don't need to negotiate terms with a counterparty. I remember working through a cross-currency swap trade where the basis spread between EURIBOR and SOFR was quoted inconsistently between two desks. One desk was using OIS as the discounting curve and the other was still pegging to LIBOR. The P&L looked fine until someone actually tried to execute it. We spent about four hours reworking the term structure before realizing the model was using conflicting day count conventions. One desk used Actual/360 and the other was on Actual/365. Small detail, massive impact on the valuation. I started requiring both desks to document their curve assumptions in writing before any trade submission. Saved us from another embarrassing situation like that one.
How To Value A Plain Vanilla Swap
Start by building a discount curve. These days that's almost always an OIS curve, not the old LIBOR-based curve you used to see everywhere. Take your floating rate predictions from the market's implied forward curve, discount each expected cash flow back to today, and calculate the present value. For the fixed leg, solve for the rate that makes the present value of fixed payments equal to the present value of floating payments. That's your swap rate. The math itself is straightforward. The floating leg value at any point in time equals the notional minus the present value of the notional discounted at the OIS rate, adjusted for any accrued interest. The fixed leg is just an annuity calculation. Set them equal and you get the par swap rate. Where people mess this up is in the bootstrap process. If your curve isn't bootstrapped correctly from the shortest tenor to the longest, errors compound. I've seen junior traders skip the intermediate tenors and just interpolate linearly between two-year and five-year points. That produces garbage for any swap with a three-year maturity. Use cubic splines or at least piecewise linear interpolation with enough knots. Most pricing libraries handle this, but you need to verify the output against market quotes at regular intervals.
Get the Full Details
Practical Trading Considerations
The biggest shift in recent years has been central clearing. Post-crisis regulations require most standardized swaps to go through a central counterparty. That changes how you think about counterparty risk. It's no longer a bilateral concern, but you do face margin requirements. Initial margin and variation margin both matter. Initial margin is set by the CCP based on portfolio stress scenarios, and variation margin gets exchanged daily based on mark-to-market movements. If you're trading swaps for hedging purposes rather than speculation, make sure the hedge effectiveness documentation is in order from the start. Regulatory frameworks like IFRS 9 and ASC 815 have specific requirements for hedge accounting. Getting this wrong means your hedging gains and losses hit the income statement at different times than the underlying exposure, which creates accounting mismatch even when the economics are fine. Another thing nobody warns you about enough is convexity. Swaps have embedded convexity because the floating rate resets periodically. When rates move sharply, the relationship between rate changes and swap value isn't perfectly linear. For small moves you can approximate with duration. For larger moves, you need to account for convexity explicitly. I once advised a client who was hedging a large fixed-rate liability with a swap and only used duration. When rates dropped twenty-five basis points in a single week, the hedge underperformed by nearly a hundred thousand dollars because nobody had priced in the convexity adjustment. After that, I made sure every swap hedge analysis included at least a second-order approximation.
Common Mistakes And How To Avoid Them
One frequent error is confusing the swap rate with the yield on a bond. They're related but not identical. A swap rate reflects the market's expectation of future short-term rates plus a small basis spread. A bond yield includes credit risk, liquidity premium, and tax considerations. Don't use bond yields as a proxy for swap rates without adjusting for these factors. Another mistake is ignoring the effect of compounding conventions. Some swaps compound floating rate payments quarterly instead of paying simple interest. A basis point difference in compounding can matter significantly over long tenors. Always check the reset frequency and whether there's any compounding in the floating leg before pricing. There's also the issue of tenor mismatch between your swap and your underlying exposure. If you're hedging a ten-year bond with a five-year swap, you have basis risk on the back end of the curve. The five-to-ten-year spread can move independently of short-term rates. This isn't necessarily fatal to the hedge, but it does reduce effectiveness. You'd be better off using a longer-dated swap or combining multiple tenors to better match the exposure.
Tools And Resources
For anyone looking to work with these instruments directly, the main pricing platforms most institutions use are Bloomberg's SWPM function, Reuters Eikon's swap module, or dedicated risk systems like MSCI RiskManager or FlexInvest. If you're doing this from scratch in Python, QuantLib is the most complete open-source library. It handles swap valuation, swaption pricing, and curve construction. The documentation is adequate but not great. You'll spend more time debugging than reading the docs initially. Fed funds futures and SOFR-based futures are now the primary benchmark instruments for the current rate environment. If you're building a curve from market data, start with overnight index swaps, then layer in FRAs, then federal funds futures, then Eurodollar or SOFR futures, and finally vanilla interest rate swaps for the longer end. Don't try to bootstrap directly from swap rates without anchoring to the shorter instruments first. The long-end swaps alone can't pin down the near-term curve. The market for these instruments is deep and liquid, especially for standard tenors up to thirty years. Anything outside that range gets wider spreads and less transparency. If you need a twenty-year swap, you'll still get reasonable execution. But if you're trading a forty-year swap or something exotic like a constant maturity swap, be prepared for tighter bid-ask spreads and potentially longer settlement times. The liquidity drops off fairly sharply beyond the standard maturities.
One last thing that catches people out is the rollover risk on swap positions. If you're running a swap that matures and you need to replace it, the new swap rate might be meaningfully different from what you locked in originally. This isn't a flaw in the instrument, it's just how markets work. Plan for it when you're structuring hedges. Don't assume you can roll at the same rate indefinitely.