What the Internal Revenue Allotment Actually Is
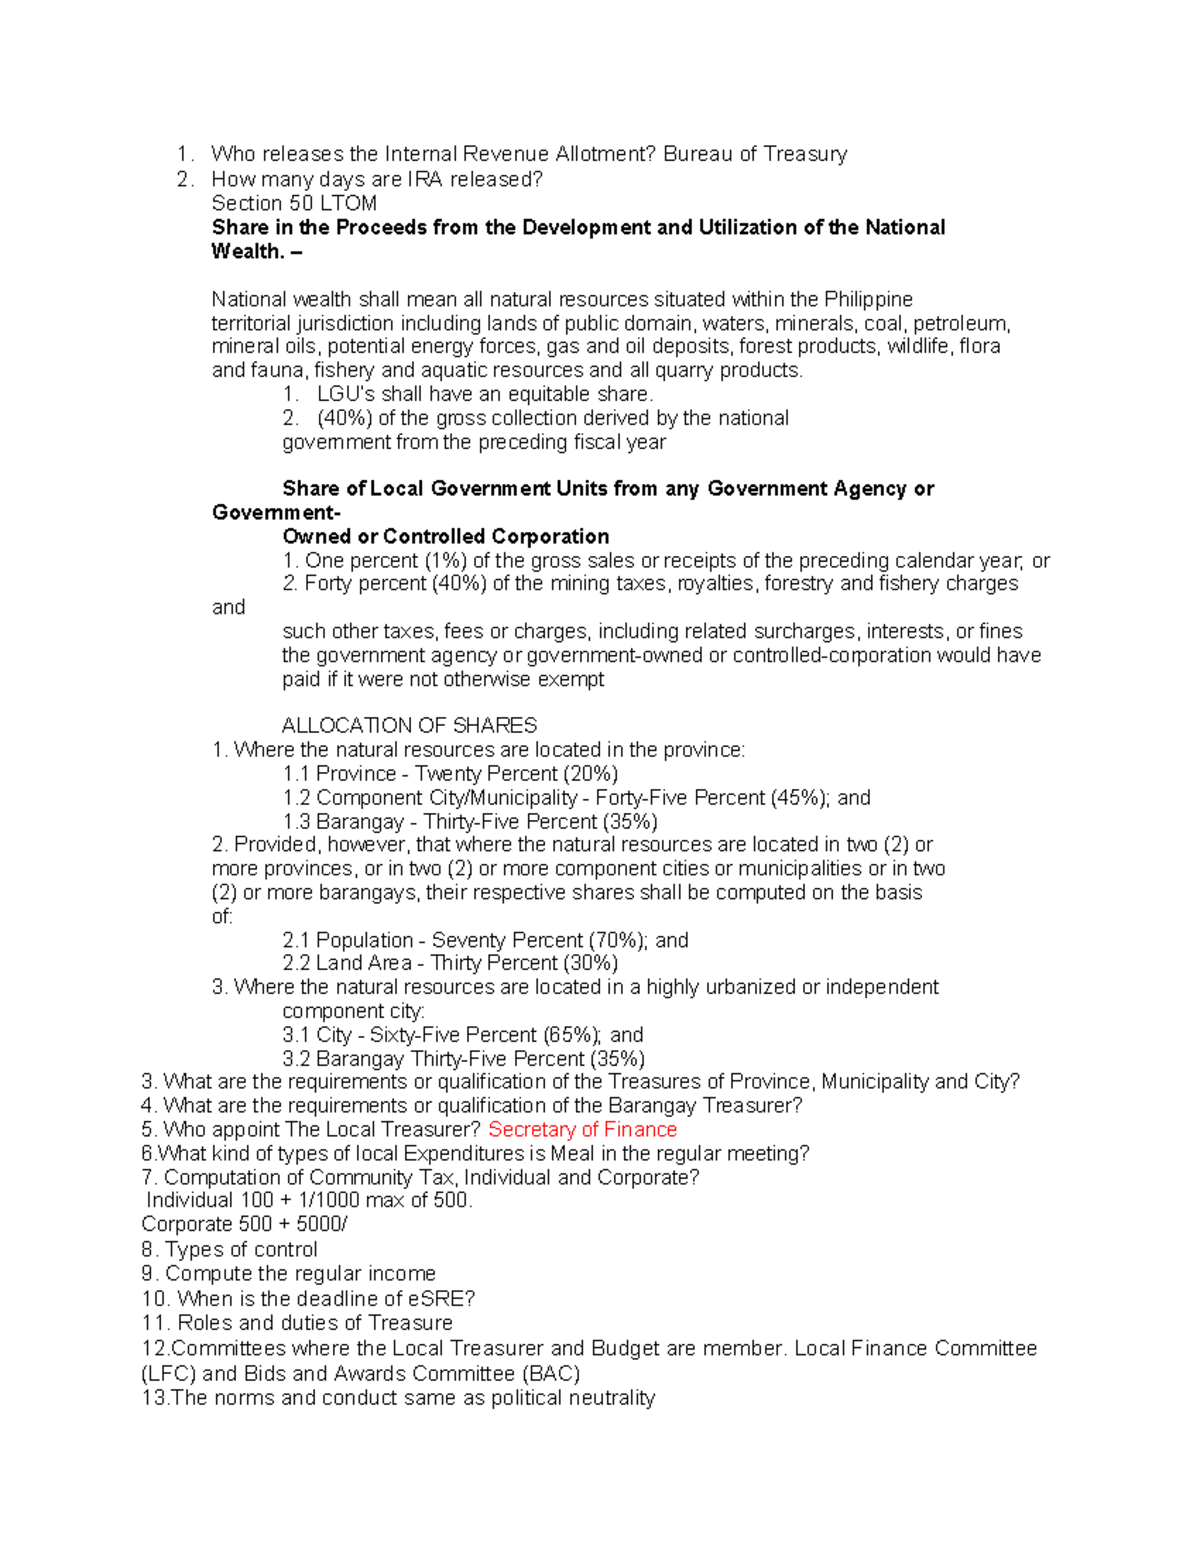
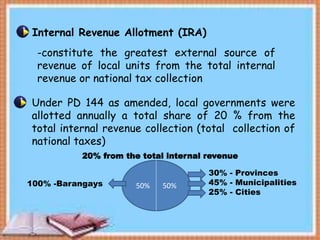
The Internal Revenue Allotment, commonly called IRA, is the portion of national internal revenue taxes that the Philippine government distributes to local government units every quarter. It's mandated by the Local Government Code of 1991, and it currently makes up 40% of all national internal revenue collections. That 40% gets split among provinces, cities, municipalities, and barangays according to a formula that considers population, land area, and equal sharing. At its core, the IRA is a fiscal decentralization mechanism. The national government collects taxes, then sends a chunk back to LGUs so they can fund basic services without relying entirely on their own locally-generated revenue. Most LGUs, especially rural municipalities, depend heavily on this transfer. In some areas, IRA accounts for over 70% of total local budget. That dependency is the first thing you need to understand before anything else. The calculation itself is straightforward on paper. DILG determines the total IRA pool from BIR and BOC collections, applies the 40% share, then distributes it using the constitutional formula. But the actual mechanics of receiving and accounting for it are where people run into problems.
I remember working with a third-class municipality that consistently had IRA disbursements delayed by three to four weeks every quarter. The issue wasn't the national government. It was their own local treasury. They were still using a manual tracking system for IRA receipts, and the National Local Government Finance Center (NLGFC) reconciliation would flag discrepancies because their recorded amounts didn't match the Department of Budget and Management's (DBM) certified schedule. The workaround was simple but painful: we had them request the DBM-certified schedule directly from the DBM Regional Office before each quarter started, then manually matched line by line against their cash book entries. It added about two days of work per quarter but eliminated the reconciliation headaches entirely. Going forward, they migrated to the Electronic IRA Clearing System (eRICS), which automated most of that matching process.
The Distribution Formula Breakdown
The IRA is allocated as follows: 50% equally among all qualified local government units, 25% based on population, 25% based on land area, with a minimum guarantee of 5 million pesos per barangay. There's also a separate 5% allocation for autonomous regions like BARMM that operates under a different calculation method. Here's something most people miss. The 50% equal sharing portion means a small rural municipality with 20,000 people receives the exact same base amount as a component city with 300,000 people. The population and land area adjustments then modify that base, but the floor is already set. This is intentional by design, but it also means highly urbanized cities often argue the formula undercompensates them relative to their service delivery responsibilities. The debate resurfaces every budget cycle and has been the subject of multiple legislative attempts to revise the sharing ratios.
Get the Full Details

When IRA Gets Complicated
The clean theoretical model breaks down in several practical scenarios. First, collection shortfalls. If BIR and BOC collections fall behind targets in a given quarter, the total IRA pool shrinks proportionally. LGUs don't get penalized differently, but everyone gets less. I've seen entire quarters where the IRA release was only 85% of the projected amount because national tax collections dipped. There's no cushion fund. The LGU just budgets what actually comes in. Second, the timing gap. IRA is supposed to be released on a quarterly basis, with the first quarter disbursement coming in January. But the actual release date depends on when the national government certifies collections. I've seen releases slip into late February or even March multiple times across different regions. Budget execution gets messy when your first quarter allocation arrives three weeks late. You either delay procurement or use prior year unreleased allocations, which has its own set of complications under the General Appropriations Act. Third, the ARMM conversion and BARMM special case. The Bangsamoro Autonomous Region in Muslim Mindanao receives its share under a different legal framework. The transition from ARMM to BARMM created a period of uncertainty where some LGUs weren't sure which formula applied. The Supreme Court eventually clarified it, but that took time and legal consultation that smaller treasuries couldn't easily afford.
Common Pitfalls
The most frequent error I see is LGUs budgeting IRA based on previous year's figures without adjusting for actual collection performance. If last year's IRA was 2.4 billion pesos, that doesn't mean this year's will be the same. Tax collection varies. Budget authors who don't account for this end up with unrealistic revenue estimates, and the resulting underspend creates suspension orders from the DBM. Another issue is the classification trap. An LGU's IRA share changes if it upgrades its income classification. A municipality converting to a component city will see its population weight increase in the formula, but the transition isn't automatic. The DTI certification and PNGRC approval process can take months, and during that window, the LGU is oftening based on ambiguous status. I once tracked a case where a newly classified city received IRA as a municipality for an entire fiscal year because the DBM hadn't processed the reclassification in time. That's a real financial hit, not a theoretical one. There's also the barangay level confusion. Barangay IRA comes from the same pool but is managed differently. Some LGU treasuries commingle barangay IRA with municipal funds, which creates accounting problems during COA audits. The rules say barangay allocations should be tracked separately, and COA has cited multiple LGUs for exactly this violation.
How to Track Your IRA Properly
Start with the DBM's quarterly IRA schedule. It's published on the DBM website and lists the exact amount allocated to each LGU. Cross-reference it with your actual bank receipts. The NLGFC also provides the eRICS portal where LGUs can monitor their IRA releases in near real-time. If you're running a large city treasury, set up a quarterly reconciliation check where you compare DBM schedule, eRICS data, and your cash book within five working days of each release. It takes about an hour and catches mismatches before they compound. For barangay treasuries, the process is simpler but less automated. Your municipality should provide the barangay IRA schedule, but don't assume they'll do it proactively. Request it in writing and keep a copy. COA auditors will ask for it, and having the paper trail saved me from a qualification on an audit report once. The IRA is not discretionary spending. It's a constitutional mandate with specific usage requirements. While LGUs have flexibility in how they spend it within their powers under the Local Government Code, diverting IRA to purposes outside those powers is a recurring COA finding. Keep your IRA-funded projects within the statutory mandate. That's the safest path.