Getting From HQ to the Rest of the World Without Losing Your Mind
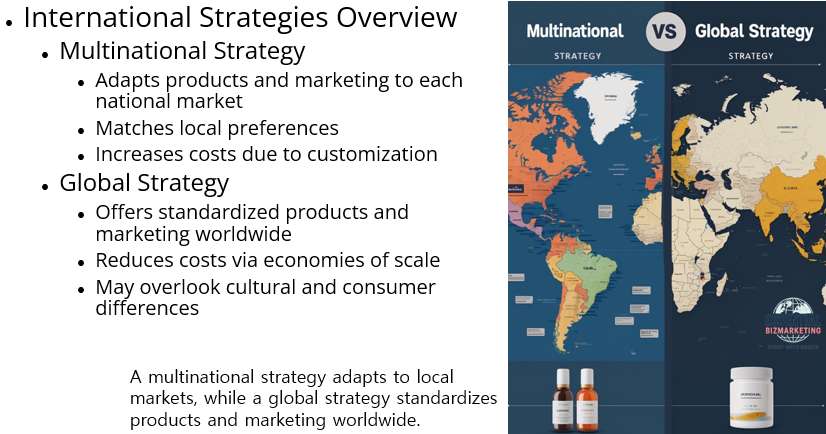
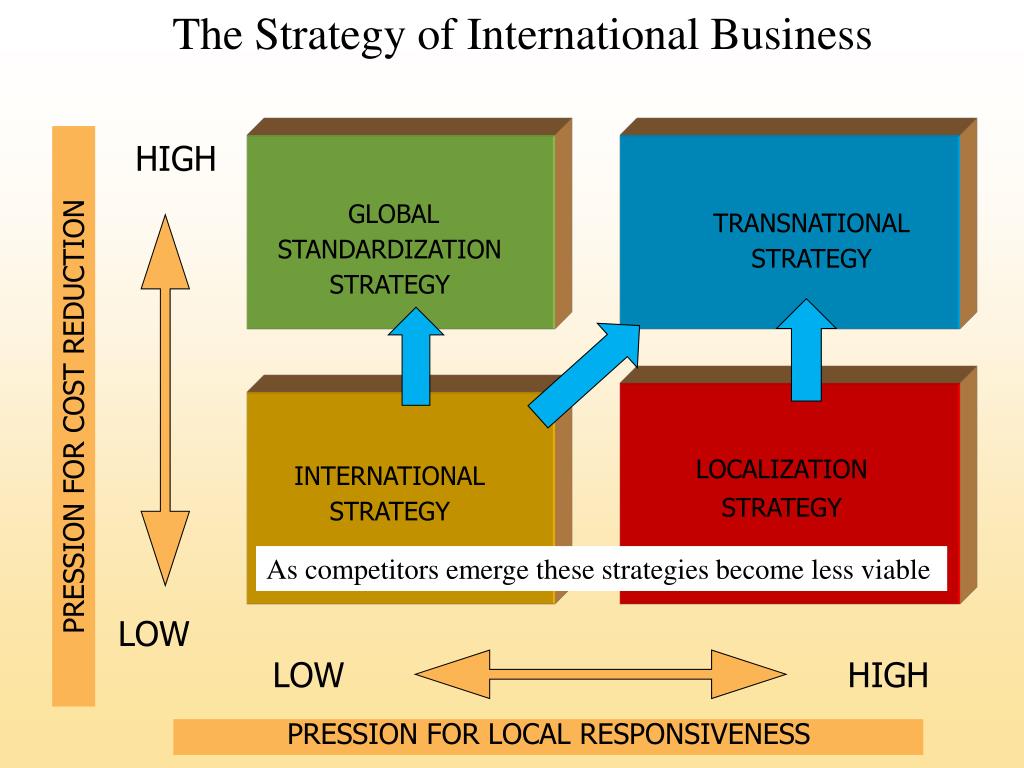
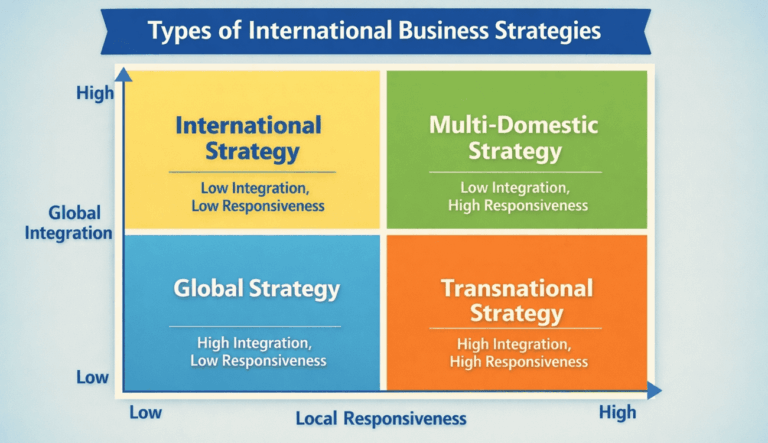
Most people think multinational strategy is about picking a country and opening an office there. It isn't. It's about figuring out which decisions stay centralized and which ones have to go local, then making sure the people actually doing the work understand the difference. I learned this the hard way when we tried to roll out a single pricing model across twelve markets in Southeast Asia and Southern Europe within the same quarter. The framework most people use is the integration-responsiveness grid. It's straightforward on paper. High global integration, low local responsiveness means you standardize everything. High local responsiveness, low integration means you let each market run independently. The messy middle is where most companies live, and it's also where they fail because nobody wrote down what "the messy middle" actually means for their org. Here's what the grid doesn't tell you. The decision about centralization isn't really about efficiency. It's about control and information flow. When I ran our European expansion, we centralized product specs but decentralized sales compensation. That meant the engineering team in Munich could ship one platform, and the sales teams in Berlin, Warsaw, and Lisbon could structure deals differently without causing version drift. The workaround was simple but easy to miss. We built a feature flag system that let regional sales toggle pricing logic per market while the product codebase stayed unified. Without it, every localization request became a full dev cycle.
The second thing people get wrong is assuming "local responsiveness" means hiring local people. It doesn't. It means giving local people the authority to make decisions that outsiders wouldn't understand. We had a market manager in Mexico City who could authorize discounts up to eighteen percent below list price without escalation. The next level up needed VP approval for anything above fifteen. This wasn't in any textbook. It came from watching us lose three deals in ninety days because the approval chain ran through London and each step added four business days. The entry mode decision is where the math gets real. Greenfield investment gives you full control but takes eighteen to twenty-four months before you see revenue. Acquisition is faster but you're inheriting someone else's cultural and operational problems. Licensing is the easiest path and also the worst for building lasting competitive advantage. Joint ventures sit somewhere in between but introduce a new risk layer entirely: your partner becomes your competitor the moment the contract expires. I've seen it happen twice. Both times the joint venture partner used your training materials and supplier contacts to spin up a rival operation within eighteen months of dissolution. Supply chain strategy matters more than most executives admit. We moved our assembly from Shanghai to (Vietnam) after tariff shifts in 2019. The landed cost per unit dropped fourteen percent, but lead time increased by eleven days because the new supplier had to build tooling from scratch. For high-margin products with long reorder cycles this was fine. For our faster-moving SKUs it caused stockouts that cost us more than the tariff savings recovered. The fix was dual-sourcing: keep the China line for volume orders and use Vietnam for the margin-sensitive segments.
Tax structure is not a sidebar. It's a core strategic variable. Transfer pricing between entities in different jurisdictions determines how much profit shows up where. Set it too aggressively toward low-tax jurisdictions and you invite audit exposure. Set it too conservatively and you leave money on the table. The arm's length principle governs this, but the OECD's Base Erosion and Profit Shifting framework has made documentation requirements substantially heavier. Companies that were comfortable with light paperwork in 2018 are now spending real engineering hours building transfer pricing support files. Factor in Pillar Two's global minimum tax at fifteen percent and the old playbook for routing profits through Ireland or the Netherlands stopped working cleanly. Culture eats strategy, but the specific mechanism is understated. When we entered Brazil, our performance review cycle assumed annual reviews with clear goal setting. The local team treated it as bureaucratic noise and the system produced zero actionable data for two years. The workaround was dropping the formal review entirely and replacing it with quarterly skip-level meetings between regional leads and VP sponsors. Headcount management in Brazil shifted from a planning exercise to a reactive cost center, but visibility improved dramatically.
Get the Full Details
What Actually Goes Wrong
Currency risk is the silent margin killer. A ten percent swing against your reporting currency erodes reported profit without changing anything about actual operations. Hedging helps but introduces its own costs and sometimes locks you into positions that hurt when rates move favorably. The practical solution most teams ignore is natural hedging: match revenue and expense currencies wherever possible. If you're selling in euros and your production costs are in euros, you don't need a forward contract. Regulatory fragmentation is another one. Data localization laws now exist in Russia, China, India, and several other markets. Storing EU customer data in a US cloud region can violate GDPR requirements depending on how you structure access. We had to build separate data pipelines for Russia after Roskomnadzor flagged our infrastructure. The workaround was a regional data hub in Moscow with automatic replication to the primary cluster, controlled by geographic routing at the application layer. It added about forty thousand dollars in annual infrastructure costs and three weeks of engineering time to set up. The biggest blind spot I've seen is assuming that a strategy which worked in one international market will transfer to another. It won't. Market A and Market B might both be in the same region and share a language, but their distribution channels, consumer expectations, and competitive landscapes can be completely different. We learned this when our German entry playbook failed in Austria. Same language, different procurement norms, different relationship dynamics with distributors. The playbook had to be rewritten from scratch, not adapted.
Here's the blunt part. International business strategy has real limitations. You cannot optimize for everything at once. High integration and high responsiveness pull in opposite directions. The deeper you go into any single market, the more local knowledge you need, and the less you can replicate what works elsewhere. This isn't a flaw in the framework. It's the framework describing reality. Companies that pretend otherwise burn through capital and trust. The alternative is accepting that some markets will always be harder, slower, and less profitable than others, and building a portfolio strategy that reflects that instead of pretending they're all the same.