Why the Math Matters Before You Touch a Brokerage Account
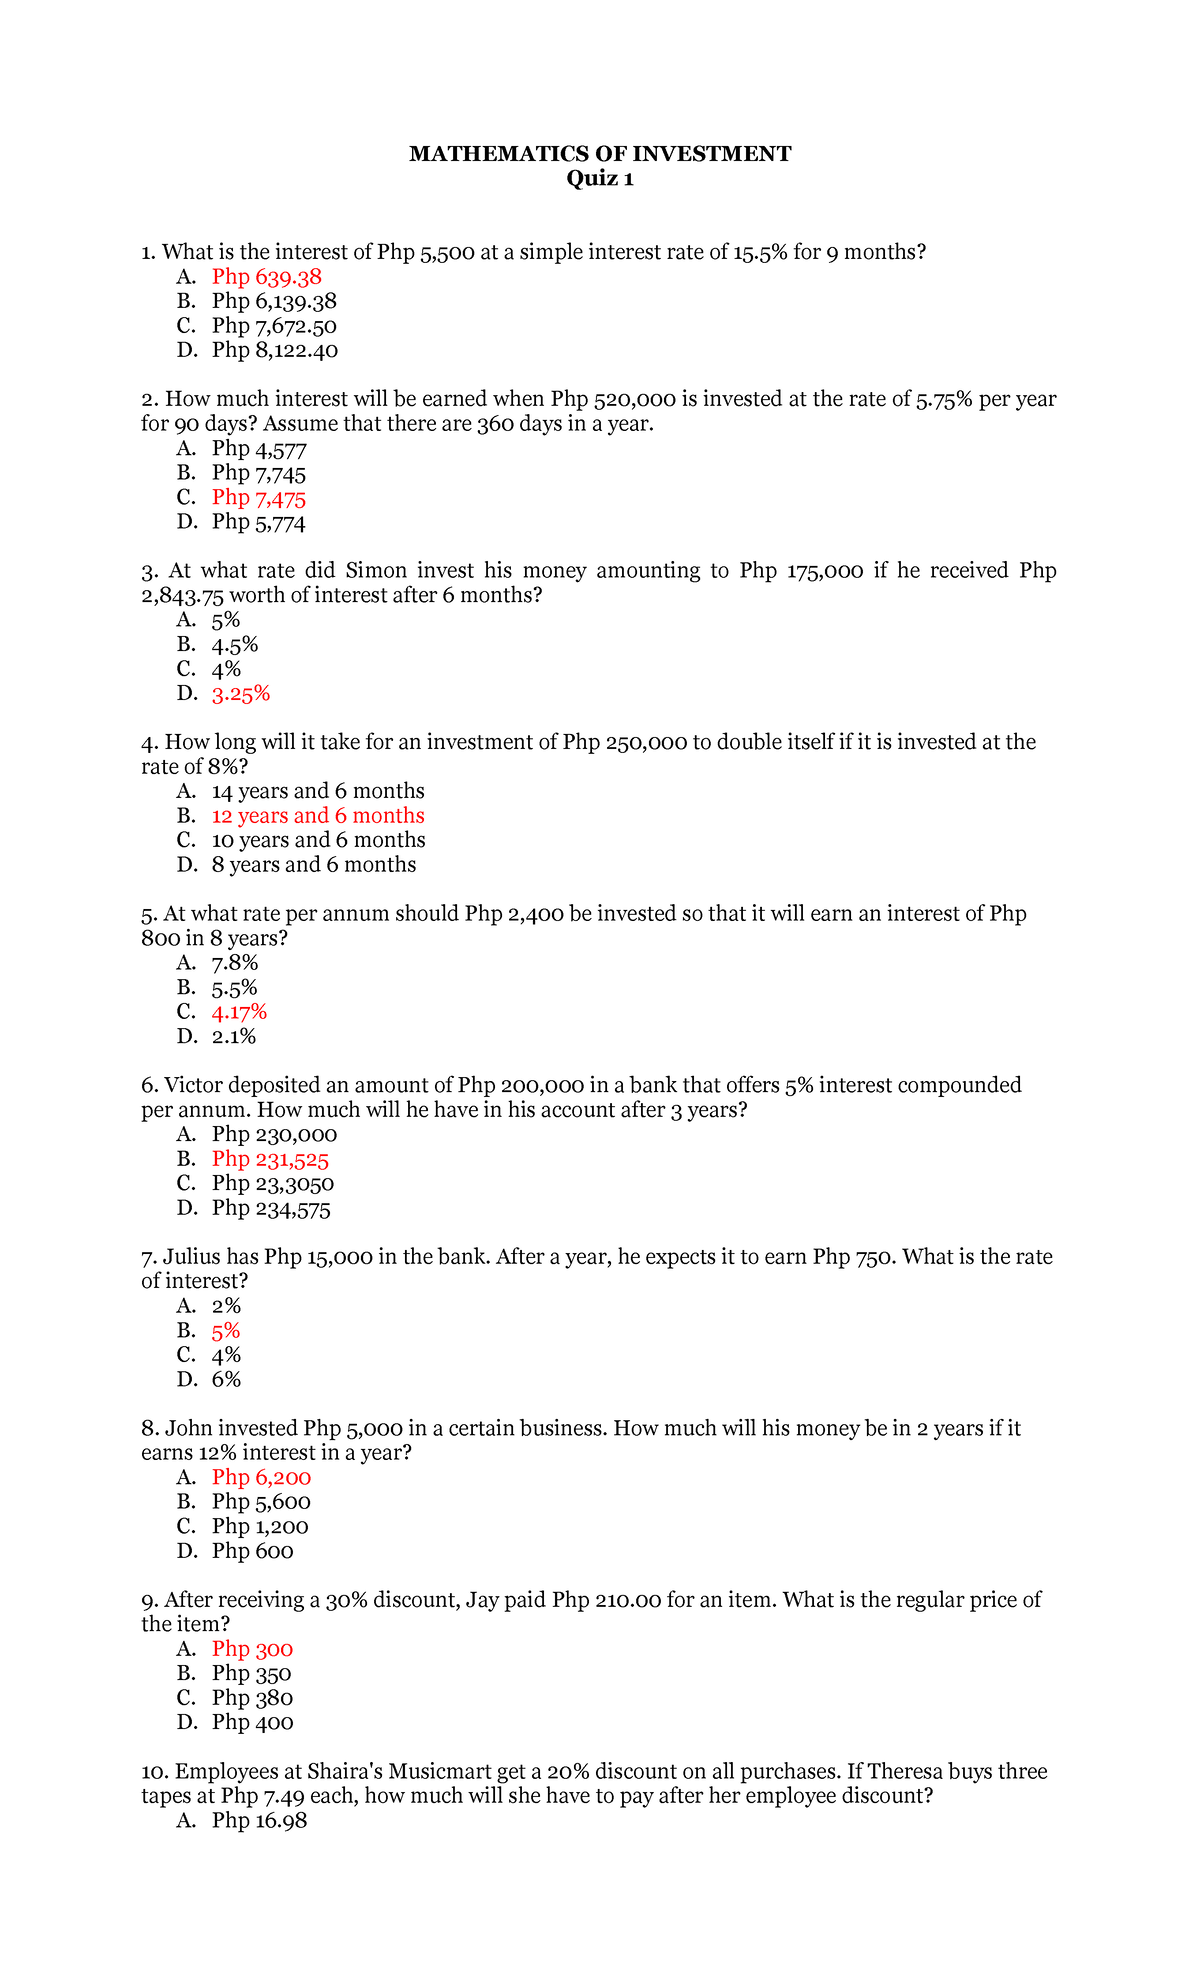
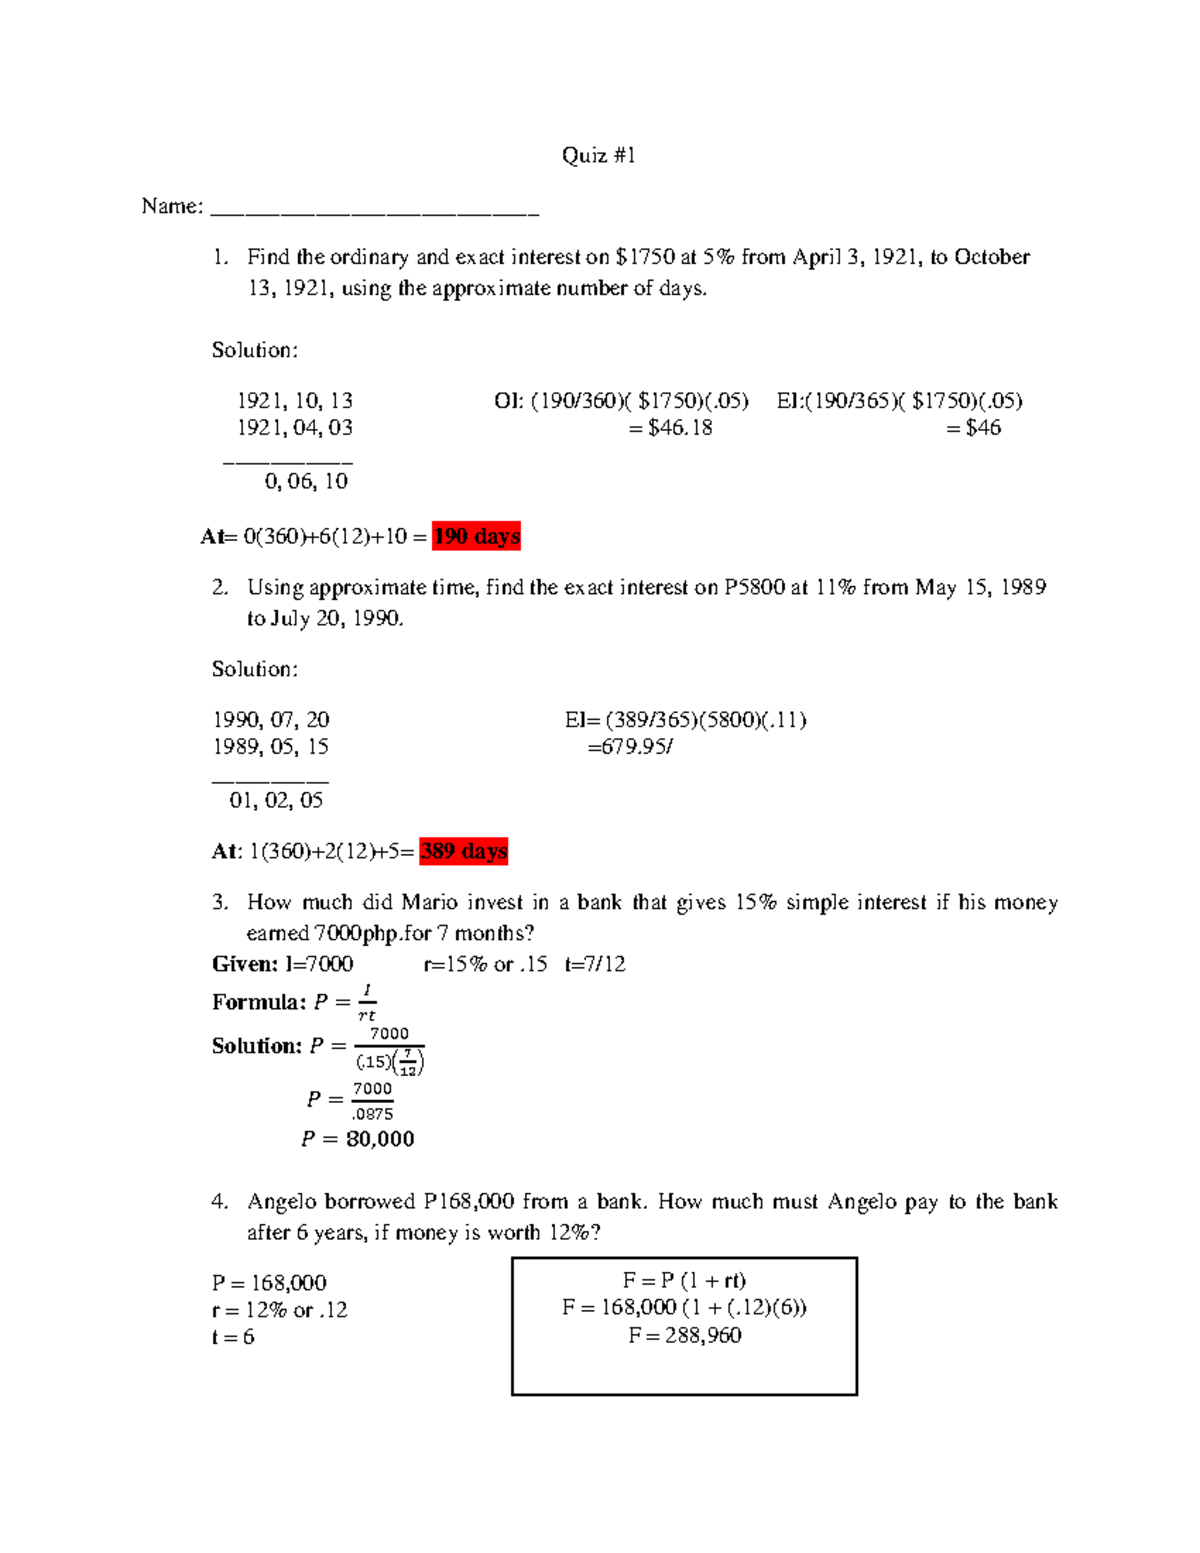
Most people skip the arithmetic and jump straight into picking stocks or crypto. That usually ends badly. The Intro To Investing Math Quiz covers the foundational calculations that separate people who actually understand their money from people who are just guessing. You need to know how returns compound, how fees eat into gains, and what real numbers look like before you put a dollar somewhere. It's not about memorizing formulas. It's about knowing which calculation applies when. You'll see questions on compound interest, simple interest, annual percentage yield, internal rate of return, present value, and basic portfolio weighting. The ones people bomb are the time-value-of-money problems where you have to work backward from a future value to find what you need to invest today. I spent months tutoring beginners through these concepts and the pattern was always the same. People could calculate compound interest if the variables lined up neatly. The moment the compounding frequency changed from annual to quarterly, they'd pick the wrong formula and get confident about a wrong answer. Switch your calculator to match the actual compounding period. A 5% rate compounded quarterly is not the same as 5% compounded annually. It compounds to about 5.09%. Small difference in isolation, massive difference over thirty years.
The Core Concepts You Need to Actually Pass
Compound Interest and the Rule of 72
Compound interest is the engine of long-term investing. The formula is straightforward: A = P(1 + r/n)^(nt). But understanding it intuitively matters more. Money earns money, and those earnings earn more earnings. The Rule of 72 is a shortcut. Divide 72 by your expected annual return and you get the approximate number of years to double your money. At 8% that's roughly 9 years. At 6% it's 12 years. It's not perfect but it's close enough for quick mental math and shows you why early investing matters so much. One edge case that trips people up every time: the Rule of 72 breaks down at very high or very low rates. If you're projecting something at 25% returns, the rule gives you about 2.9 years to double, but the actual calculation is closer to 3.1. At 2%, it says 36 years but reality is around 35. For most retail investing scenarios between 4% and 12%, it's reliable enough to use on a napkin.
Internal Rate of Return and Net Present Value
These two concepts are where most beginner resources stop explaining things properly. IRR is the discount rate that makes the net present value of all cash flows equal zero. NPV discounts future cash flows back to today's dollars so you can compare apples to actual apples. You don't need a financial calculator for basic versions. Excel's IRR function does the heavy lifting, but you should understand what it's actually telling you. Here's what nobody warns you about: IRR assumes that interim cash flows get reinvested at the same rate as the IRR itself. That assumption is almost never true in practice. A project showing a 18% IRR might actually be more like 11% in real terms if you're plausibly reinvesting at 7%. Modified Internal Rate of Return, or MIRR, fixes this by letting you specify a realistic reinvestment rate. Use MIRR when someone hands you an IRR number and seems too excited about it.
Get the Full Details

Weighted Averages and Portfolio Math
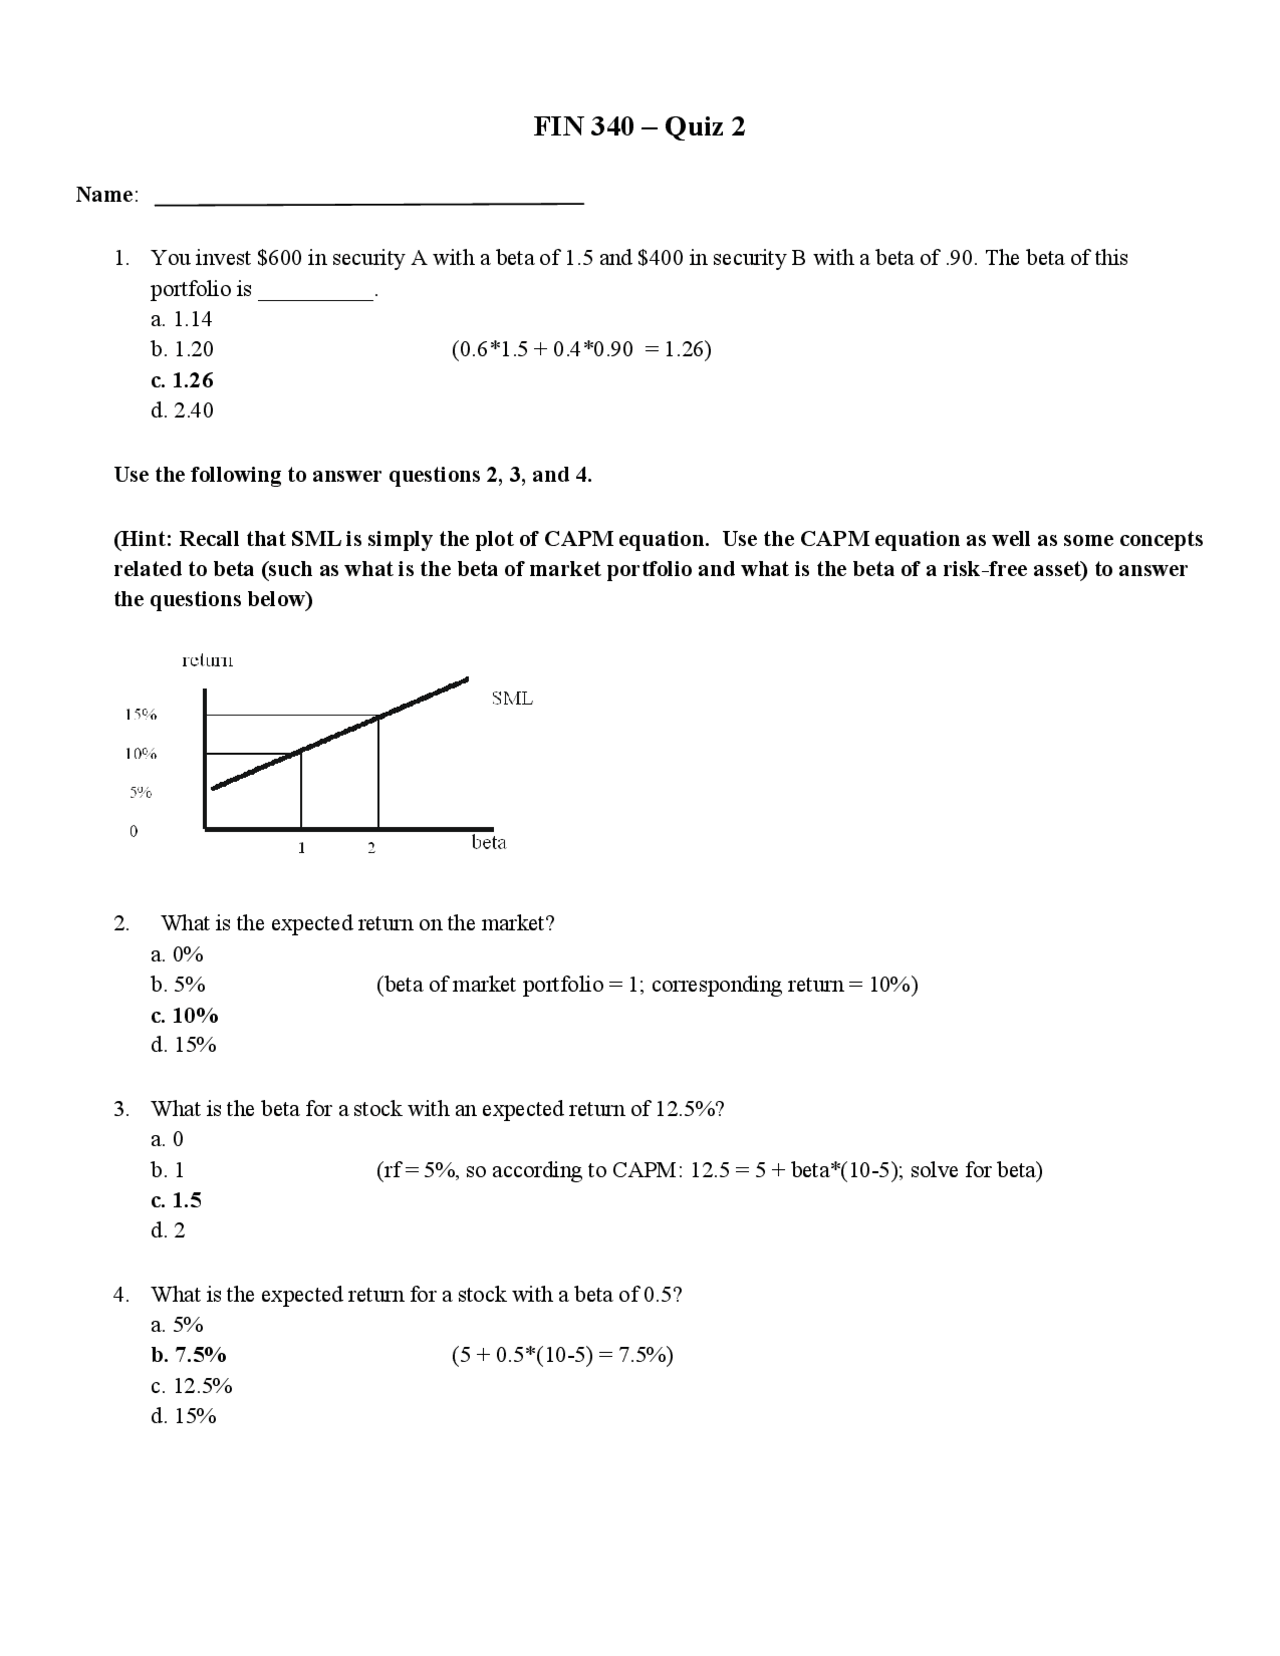
Portfolio returns aren't just averages of individual asset returns. They're weighted averages. If you put 80% of your money in an index fund returning 10% and 20% in a speculative position returning -30%, your portfolio doesn't return -10%. It returns 4%. The math is simple but people consistently misjudge their own exposure because they think in terms of number of holdings rather than dollar allocation. Ten positions that each moved 5% doesn't tell you anything useful. What matters is how much capital is actually in each one. The biggest mistake is mixing up nominal and real returns. A 7% return sounds solid until inflation eats 3% and your real purchasing power only grew 4%. The Fisher equation approximates this: real rate nominal rate minus inflation rate. It's not exact but it's close enough for the kind of questions these quizzes ask. The exact version divides (1 + nominal) by (1 + inflation) and subtracts one, which gives you 3.88% instead of 4%. On a test, they'll usually accept the approximation unless they specifically want the precise calculation. Another trap is confusing money-weighted and time-weighted returns. Money-weighted returns account for the timing and size of your contributions and withdrawals. Time-weighted returns strip out the effect of cash flows and measure pure investment performance. If you dumped a large sum into an investment right before a market crash, your money-weighted return will look terrible even if the underlying asset performed fine. Fund managers are judged on time-weighted returns because that's the only way to compare them fairly. Your personal returns are money-weighted because your life isn't fair.
I ran into this exact problem when helping a client review a retirement account. Their statement showed a negative 8% return for the year, but the underlying fund was up 5%. The issue was they'd contributed $50,000 in October after the market had already dropped hard that year. Their money-weighted return crushed the fund's time-weighted return. Nothing wrong with the investments. Just bad timing on contributions. This happens constantly and nobody explains the difference until you ask.
How to Actually Prepare for This Kind of Quiz
Do practice problems, not readings. The math sticks when you calculate it yourself. Start with compound interest until you can do it in your head, then move to present value and future value scenarios. Try calculating what you'd need to save monthly to reach a specific retirement number at different return rates. Work through IRR problems with a spreadsheet so you see how the numbers converge. The free resources that actually help are Khan Academy's finance modules and the CFA Institute's introductory materials. Commercial test prep courses for these quizzes tend to overcomplicate things and charge too much. You don't need a course. You need repetition with feedback on wrong answers. Keep a equivalent, whatever the correct translation is, and review your mistakes weekly until the patterns become obvious. If you're looking for a structured way to test yourself, search for an Intro To Investing Math Quiz from a reputable financial education source. Make sure it actually covers TVM calculations and not just vocabulary. Some quizzes disguise themselves as comprehensive but only test definitions. You'll pass with a high score and still not know how to calculate a present value. That's worse than failing because it gives you false confidence.
When These Calculations Aren't Enough
Math literacy gets you through the quiz and keeps you from making stupid mistakes. It doesn't make you a good investor. Understanding valuation, risk assessment, market cycles, and your own behavioral biases matters just as much. The arithmetic is the floor, not the ceiling. Also, these calculations assume certain conditions that don't always hold. Taxes change everything. Fee structures matter more than most people calculate. And projections are only as good as the assumptions behind them. But you can't navigate any of that without first being comfortable with the numbers. Start with the math. Get it solid. Then build outward from there.