What Actually Matters When You're Learning Accounting
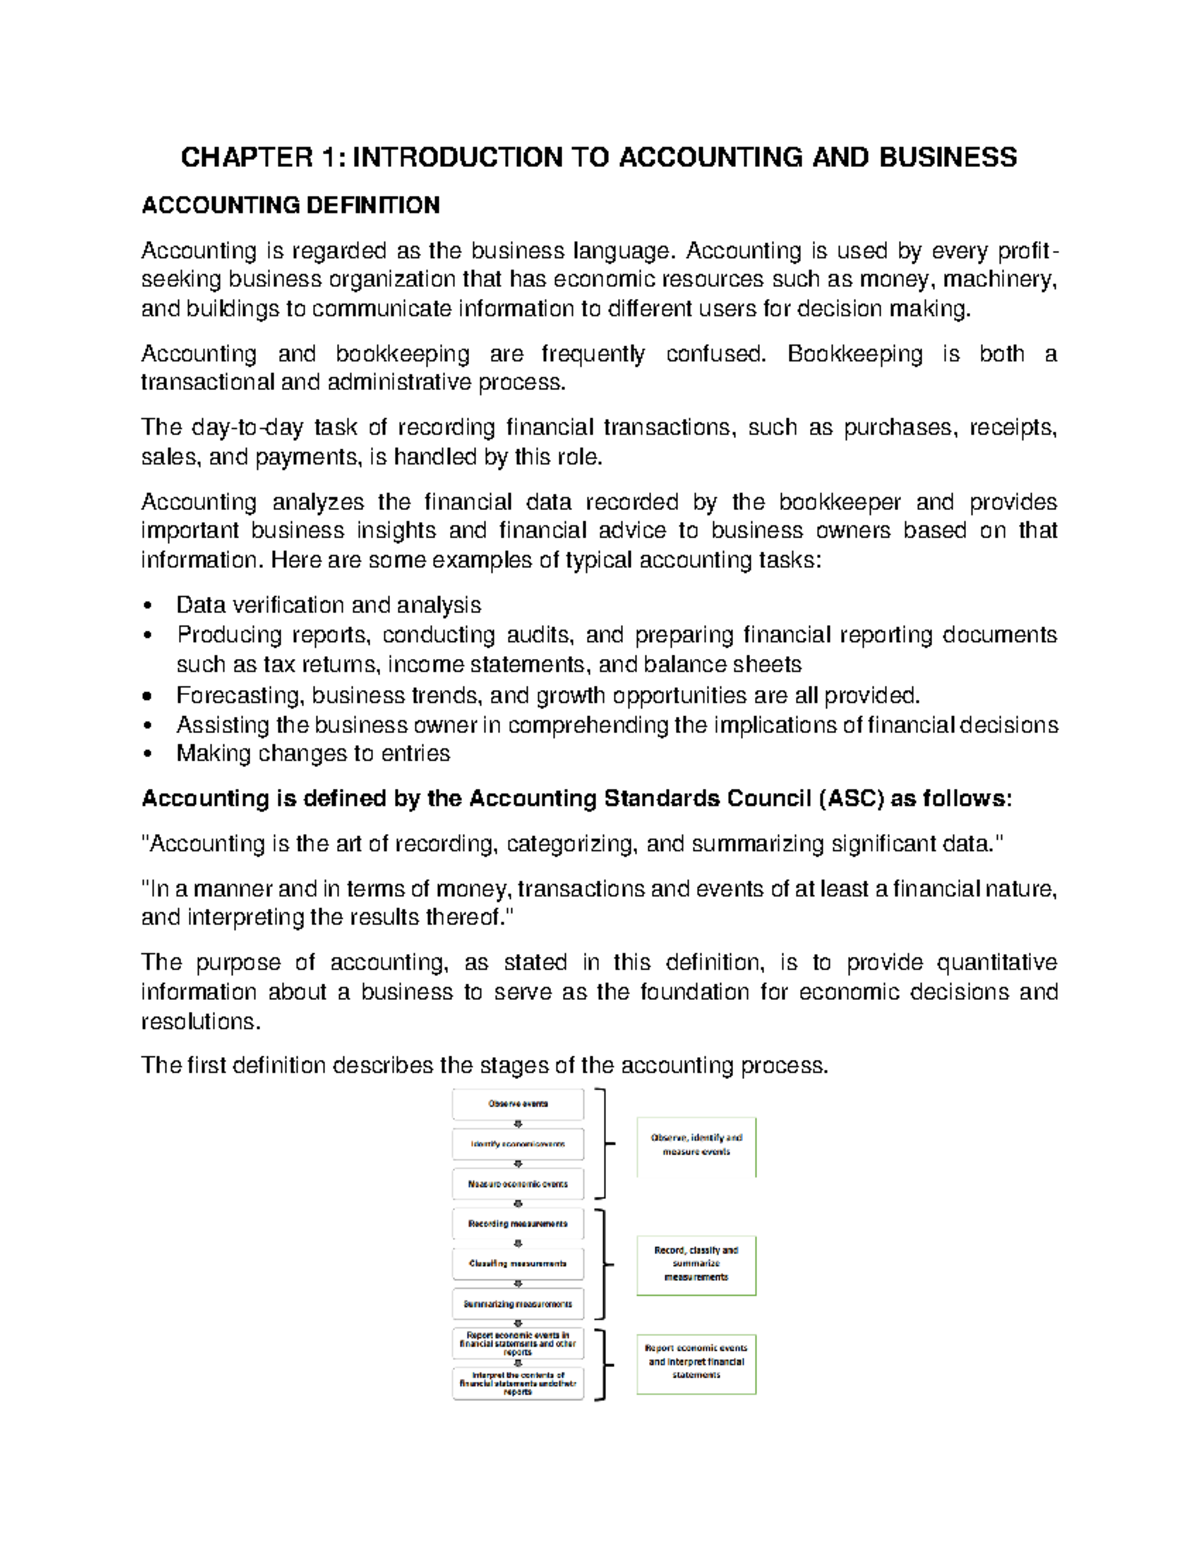
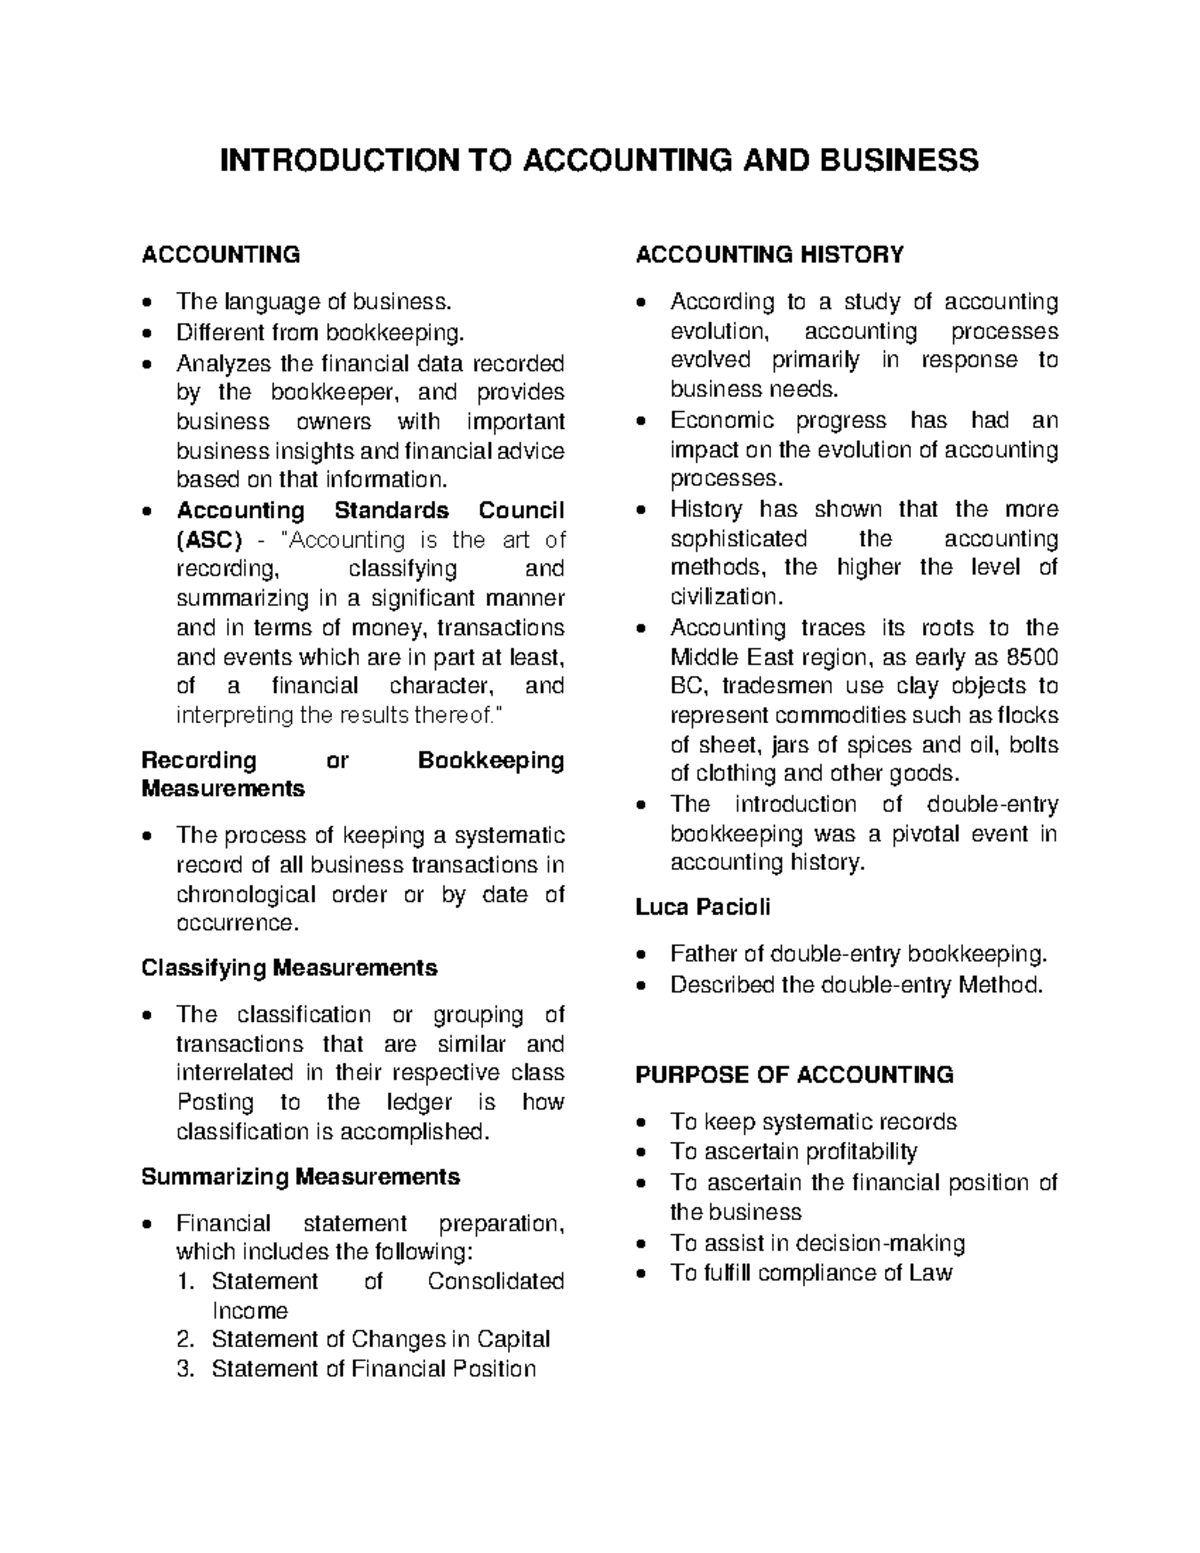
Most people stumble over the same concepts in their first accounting course. I've seen it repeatedly over the years, and it usually comes down to two things: confusing the timing of revenue recognition with the timing of cash flow, and not understanding that debits and credits aren't inherently good or bad—they just indicate direction. Accounting is the language businesses use to communicate financial reality. It's not optional, even if you're running a small operation or working as a consultant. When you can read a balance sheet or follow a journal entry backward from a financial statement, you suddenly have access to information most people miss entirely. I remember one time when a client's books showed $200,000 in revenue for the quarter, which looked great on paper. But when I traced through the receivables aging report, most of it was 90-plus days past due. The cash was never actually there. That distinction between accrual-based revenue and actual liquidity is something most introductory courses gloss over, and it's the difference between making a bad hire or spotting a real problem.
Introduction To Accounting And Business Fundamentals
The core framework rests on the accounting equation: Assets equal Liabilities plus Equity. Everything in financial accounting traces back to that relationship. If it doesn't balance, something is wrong. Period. This isn't theory—it's the mechanical check that catches errors before they compound into larger problems. I've spent more hours than I care to admit tracking down a single cent that refused to reconcile, only to find it was a transposition error on an invoice from three months prior. The five main types of accounts are assets, liabilities, equity, revenue, and expenses. Each account has a normal balance side—assets and expenses increase on the debit side, while liabilities, equity, and revenue increase on the credit side. Beginners always get tripped up by the fact that expenses reduce equity yet sit on the debit side. The shortcut is to think of each account type's relationship to the equation rather than memorizing rules in isolation. Assets on one side, everything else on the other. Debits and credits maintain the balance. Financial statements are where this machinery produces output. The balance sheet shows position at a point in time. The income statement shows performance over a period. The cash flow statement reconciles the gap between accrual earnings and actual cash movement. You need all three to get a complete picture. A profitable company can still go bankrupt if cash flow is negative. I learned that the hard way watching a previously reliable vendor collapse—they were profitable on paper but had stretched their payables too far and couldn't roll over short-term obligations.
Double-entry bookkeeping means every transaction affects at least two accounts. When you buy equipment for $5,000 cash, you debit Equipment and credit Cash. When you earn revenue on credit, you debit Accounts Receivable and credit Revenue. The system self-checks because every entry must balance. Modern accounting software handles this automatically, which is convenient until something goes wrong and you don't understand why the numbers won't tie out. I had a situation once where automated recurring entries had created a phantom liability because a vendor code got reassigned between fiscal years. The software never flagged it because each individual entry balanced perfectly. It took me three hours of manual ledger review to find it.
Get the Full Details
Practical Steps For Getting Started
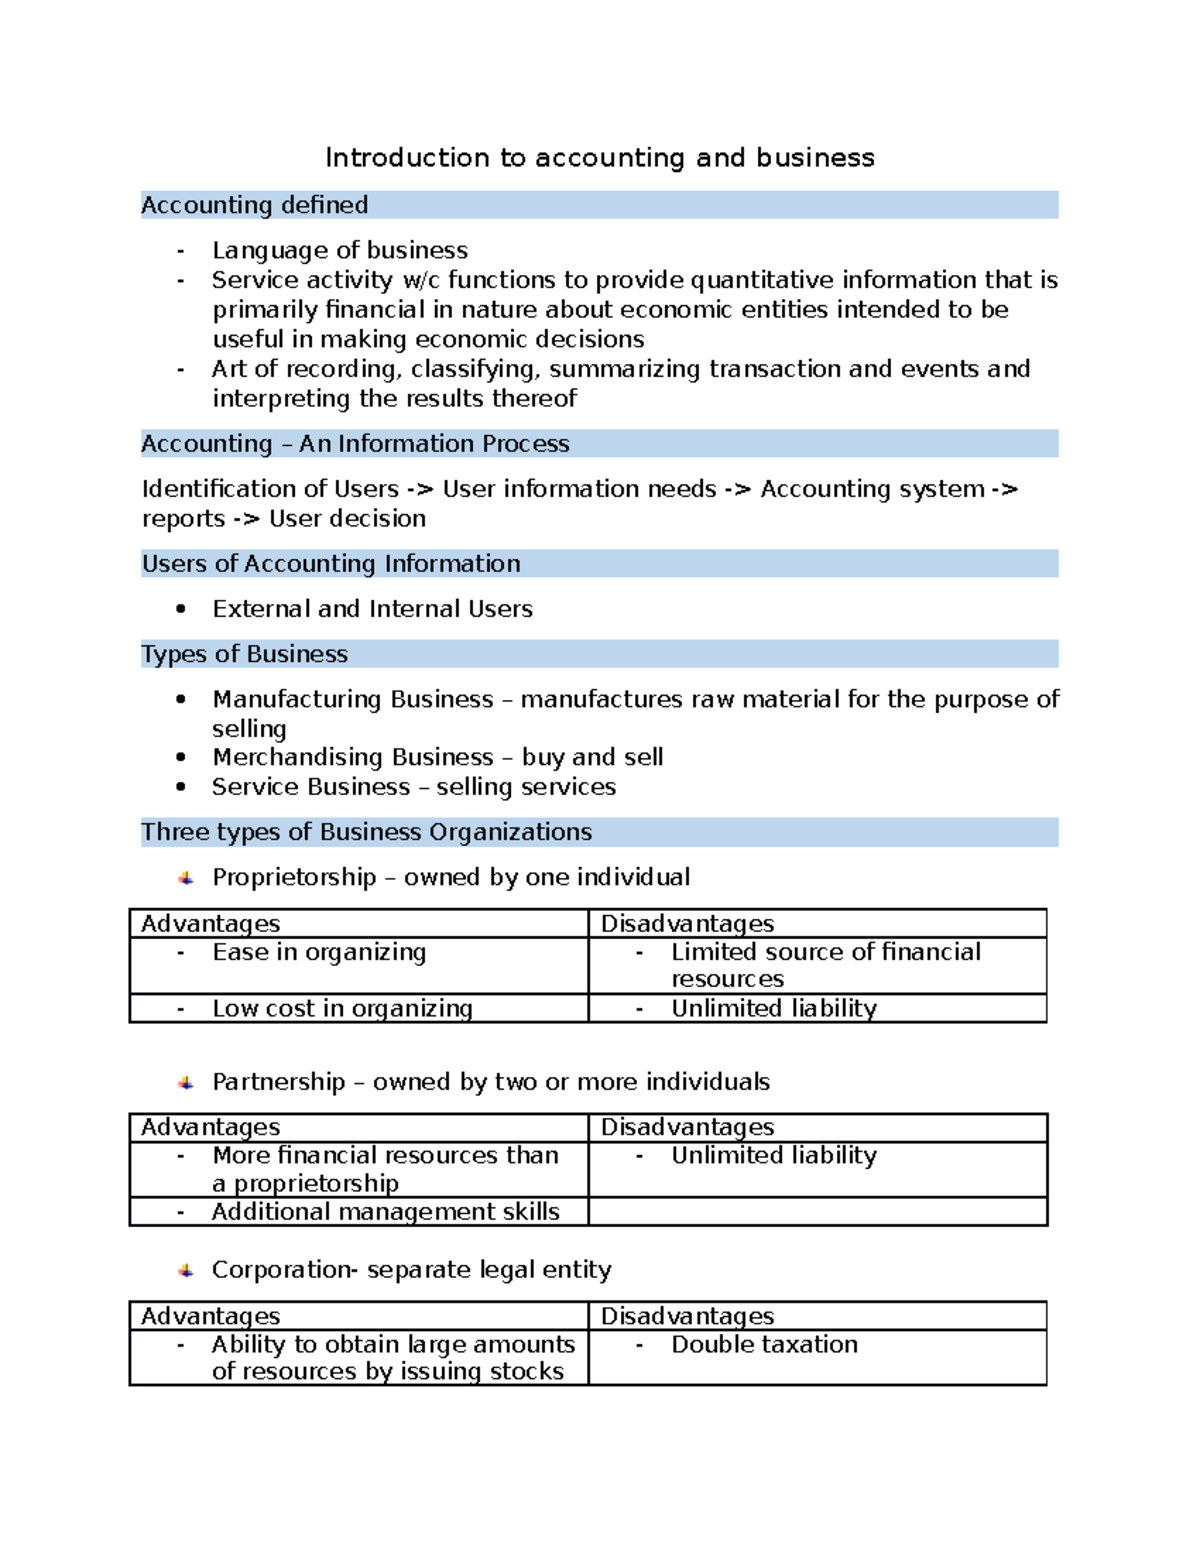
Start with small business scenarios before moving to corporate structures. Use a spreadsheet to map out transactions manually. This forces you to think through the mechanics instead of relying on software to hide them from you. I recommend working through at least twenty common transaction types by hand before you touch QuickBooks or Xero. The muscle memory matters more than you'd expect when you're dealing with unexpected situations. Learn to read a trial balance and understand what each line represents. A trial balance that balances doesn't mean your books are correct—it just means debits equal credits. Errors like omitting an entire transaction, posting to the wrong account, or recording the wrong amount will all slip through a trial balance check. The next step is reviewing the general ledger detail and reconciling each account against external evidence: bank statements, credit card statements, vendor invoices. Understand the difference between cash basis and accrual basis accounting. Cash basis records revenue when received and expenses when paid. Accrual basis records revenue when earned and expenses when incurred regardless of cash movement. Most small businesses start on cash basis and then get forced into accrual as they grow or seek financing. The transition is jarring because profitability looks completely different under each method. A business can appear highly profitable on cash basis while carrying substantial unpaid obligations on accrual.
Pick up a copy of the financial statements from a public company you're familiar with. Read the notes. The notes contain more information than the statements themselves—they disclose contingencies, accounting policies, segment data, and related-party transactions that materially affect your interpretation. I regularly find that the notes reveal risk factors the income statement masks entirely. One particularly useful habit is comparing the statement of cash flows against net income. The larger the gap, the more you need to understand what's driving it. A consistently large gap between net income and operating cash flow is usually a red flag, whether it comes from aggressive revenue recognition or growing receivables.
Common Mistakes That Waste Time
The biggest mistake beginners make is treating accounting as a series of isolated rules rather than an interconnected system. When you don't understand how one account affects another, every adjustment becomes a guessing game. Recording a depreciation entry, for example, reduces accumulated depreciation on the balance sheet, reduces net income on the income statement, and reduces cash flow from operations on the cash flow statement through the indirect method reconciliation. If you treat each statement in isolation, you'll produce inconsistent numbers. Another frequent error is ignoring the timing of transactions near period boundaries. Revenue recognized in the wrong month distorts both the income statement and balance sheet. I once spent an entire week correcting a distributor's books because they had recorded freight charges as part of cost of goods sold instead of as a separate operating expense. The gross margin percentages looked reasonable, but the operating expense line was understated and the COGS line was overstated. It didn't affect net income, but it made the company look fundamentally less efficient than it actually was, and it threw off benchmark comparisons against industry peers. Don't rely solely on automated software outputs. I've seen too many people accept whatever the system produces without verification. The system will happily post transactions to the wrong accounts if the chart of accounts is poorly structured or if someone selects the wrong account during data entry. Schedule monthly reviews where you actually open the general ledger and verify that unusual entries make sense. This takes about thirty minutes if your books are clean and significantly longer if they aren't.

When Basic Accounting Falls Short
Standard bookkeeping won't give you answers for inventory valuation under varying cost flow assumptions, lease accounting under ASC 842, or revenue recognition under ASC 606 for complex contracts. These areas require deeper study or professional assistance. Attempting to handle these without proper training usually produces results that look correct on the surface but contain material errors. The software interfaces for these topics are often simplified representations that obscure important judgment calls. If you're working with a business that has inventory, learn FIFO, LIFO, and weighted average costing. Different methods produce different inventory values and different cost of goods sold figures under the same physical flow. In periods of rising prices, LIFO produces lower taxable income than FIFO. This isn't a minor detail—it can represent tens of thousands in tax difference annually. I worked with a wholesale operation that switched from LIFO to FIFO during an inventory count and found their reported inventory value jumped by eighteen percent overnight. Their tax liability increased proportionally, and they had never considered how their choice of cost flow assumption was affecting their bottom line. For most small business applications, a solid grasp of the basic framework combined with the ability to read and question financial statements is sufficient. You don't need to be a CPA to understand your own business finances. What you need is the ability to look at numbers and ask the right questions about where they came from and whether they make sense. The best accountants I know spend more time questioning their assumptions than they do crunching numbers.
If you want resources, the Financial Accounting Standards Board website at fasb.org maintains the authoritative literature for US accounting standards. The SEC's EDGAR database contains all filed financial statements from public companies, which is useful for practicing on real data. Free courses from platforms like Khan Academy cover the fundamentals adequately, though they tend to stay at an introductory level. For practical application, nothing beats working through actual transactions in a real business environment or a detailed case study where you can see how decisions cascade across all three financial statements. The field moves slowly compared to technology or marketing, but that doesn't mean it's simple. The fundamentals haven't changed much in centuries because the underlying economics haven't changed. What changes are the regulations, the software interfaces, and the complexity of business models. Your job is to understand the constants well enough to recognize when the variables matter.