What You Actually Need From Managerial Accounting Study Materials
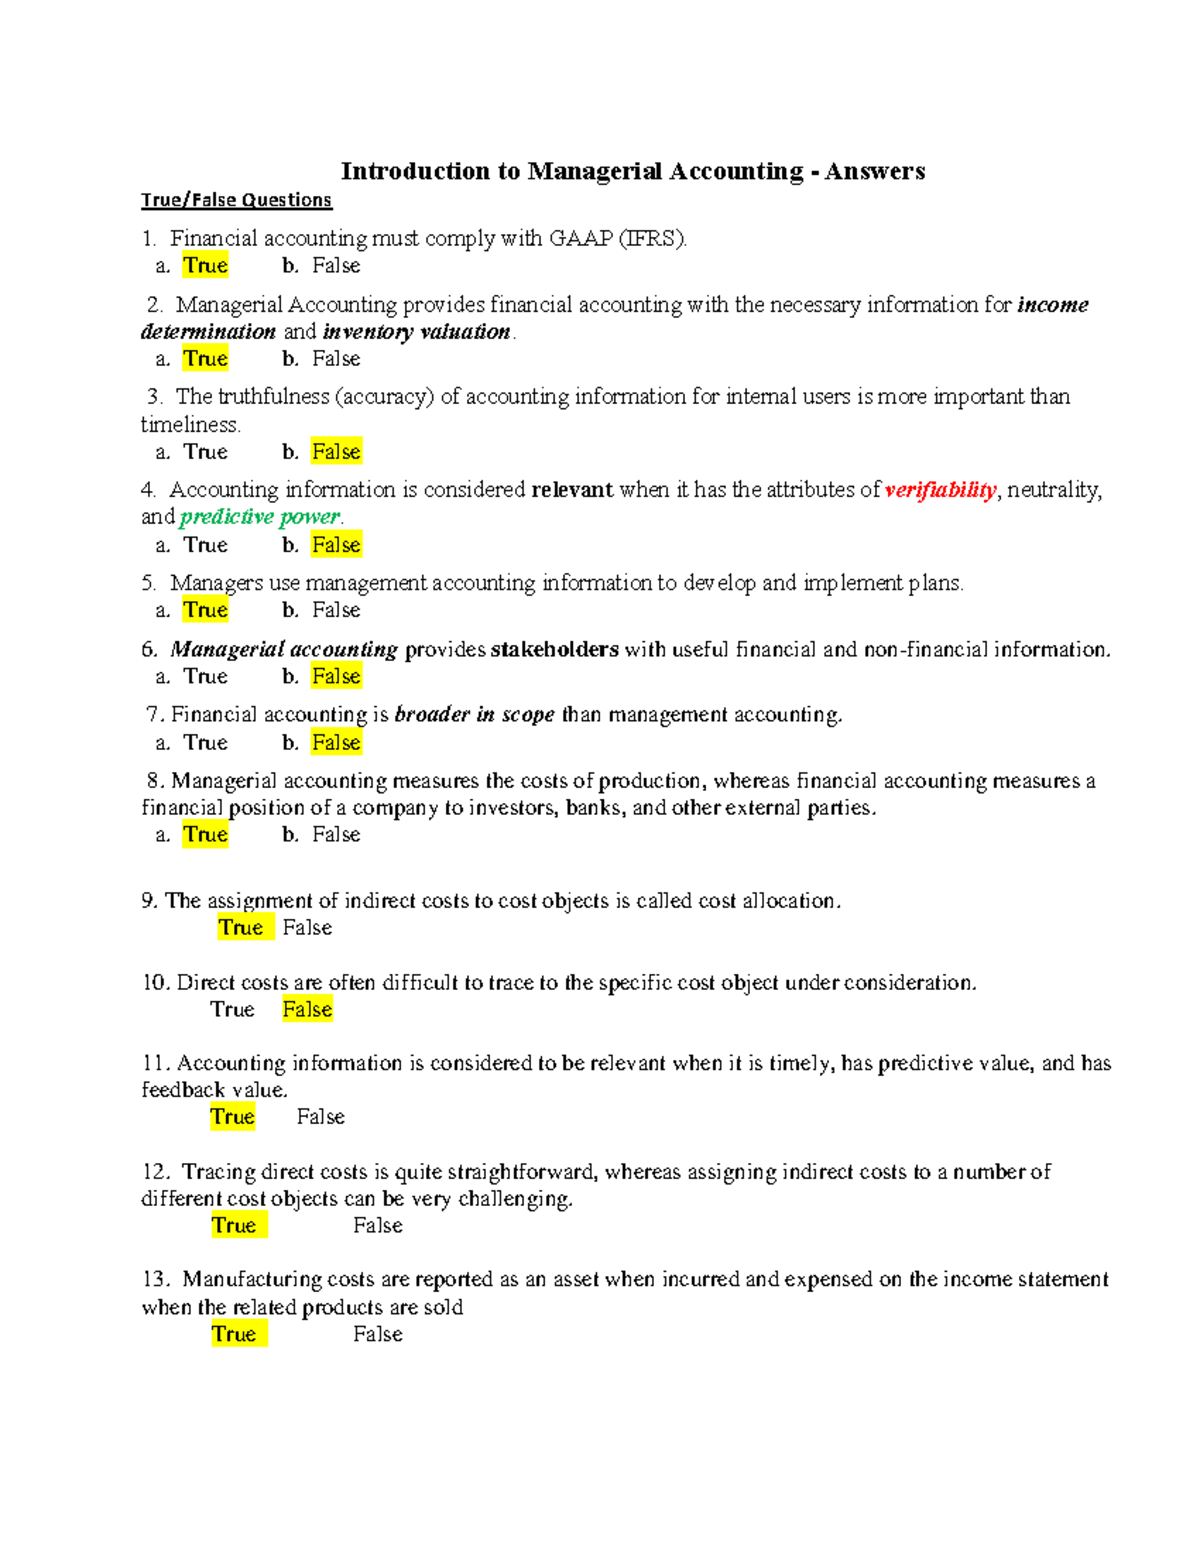
Most people looking for Introduction To Managerial Accounting Answers are stuck somewhere between variable costing chapters and break-even analysis, trying to figure out which number goes where on a worksheet that seems designed to confuse them. The internet is flooded with these things. A lot of it is copy-pasted from quizlet dumps or Chegg answers that were two years out of date when they were posted. Some of it is accurate. Most of it is just noise. I spent about three semesters grading managerial accounting midterms and finals before moving into actual corporate controller work. What I found repeatedly was that students don't actually need the answers to the textbook problems. They need to understand why the answer matters. That distinction is the difference between passing a course and actually knowing something you can use in a job.
Finding Reliable Introduction To Managerial Accounting Answers
Let me walk through how this actually works in practice, because there's a real difference between having the right final number and understanding the path to get there. I once spent a full week debugging a student's absorption versus variable costing problem. The textbook answer key said the answer was $47,300. The student's spreadsheet showed $45,800. Everyone assumed the student was wrong until I traced every line item. The issue was that the textbook had misclassified a $1,500 material handling cost as a period expense rather than a product cost. That's the kind of thing you will never learn from just reading an answer key. The real value is in spotting where the key itself might be shaky. When you are hunting for these resources, look for sources that show their work. Any single answer without the supporting calculation is basically useless to you. You are going to see the same problem type on every managerial accounting exam, and the numbers will change. If you only memorized the final answer, you have nothing to fall back on. The people who actually learn this stuff write out every step, note which cost pool each expense belongs to, and flag any assumptions they made along the way. Here is the practical workflow I recommend. Take your textbook problem first. Solve it on paper without any help, even if you think you will get it wrong. Write down each calculation. Then compare your work against a verified source. The gap between your attempt and the correct solution is where the actual learning happens. Reading someone else's correct work before you have struggled with the problem yourself is almost never effective. Your brain is not wired to retain information it has not earned.
There is also a specific problem type that trips up nearly everyone, and it comes up in almost every introductory course. It is the fixed manufacturing overhead volume variance. Students understand the formula: Budgeted fixed overhead applied minus budgeted fixed overhead actual. But they consistently mess up the denominator level. Some textbooks use normal capacity, some use practical capacity, some use expected actual production. If your answer key does not specify which one it used, the answer could be wrong for your class. I learned this the hard way during my second semester when I got a problem marked incorrect even though my math was right. The instructor had used practical capacity while the answer key used expected actual. We argued about it for twenty minutes. He was technically correct per the textbook edition, but the question should have stated which basis to use. I still think about that moment because it shaped how I approach cost accounting in real work environments where the assumptions are rarely spelled out clearly. If you want legitimate study materials, look for resources from established educational publishers or university departments. Many professors post solution manuals through official channels. Some textbooks have companion websites with worked examples. Avoid sites that promise instant downloads of entire test banks. Those are usually illegal and often inaccurate. The people running those operations do not care about correctness. They care about ad revenue and email captures. Another thing nobody tells you about managerial accounting: the concepts repeat across different chapter names but test the same underlying mechanics. Direct materials price variance and direct labor rate variance use the exact same formula structure. Overhead spending variance and selling expense budget variance follow identical logic. When you recognize the pattern, you can solve problems faster and catch errors more easily. The subject is not about memorizing twelve separate topics. It is about recognizing that most of them are the same topic wearing different costumes.
Get the Full Details
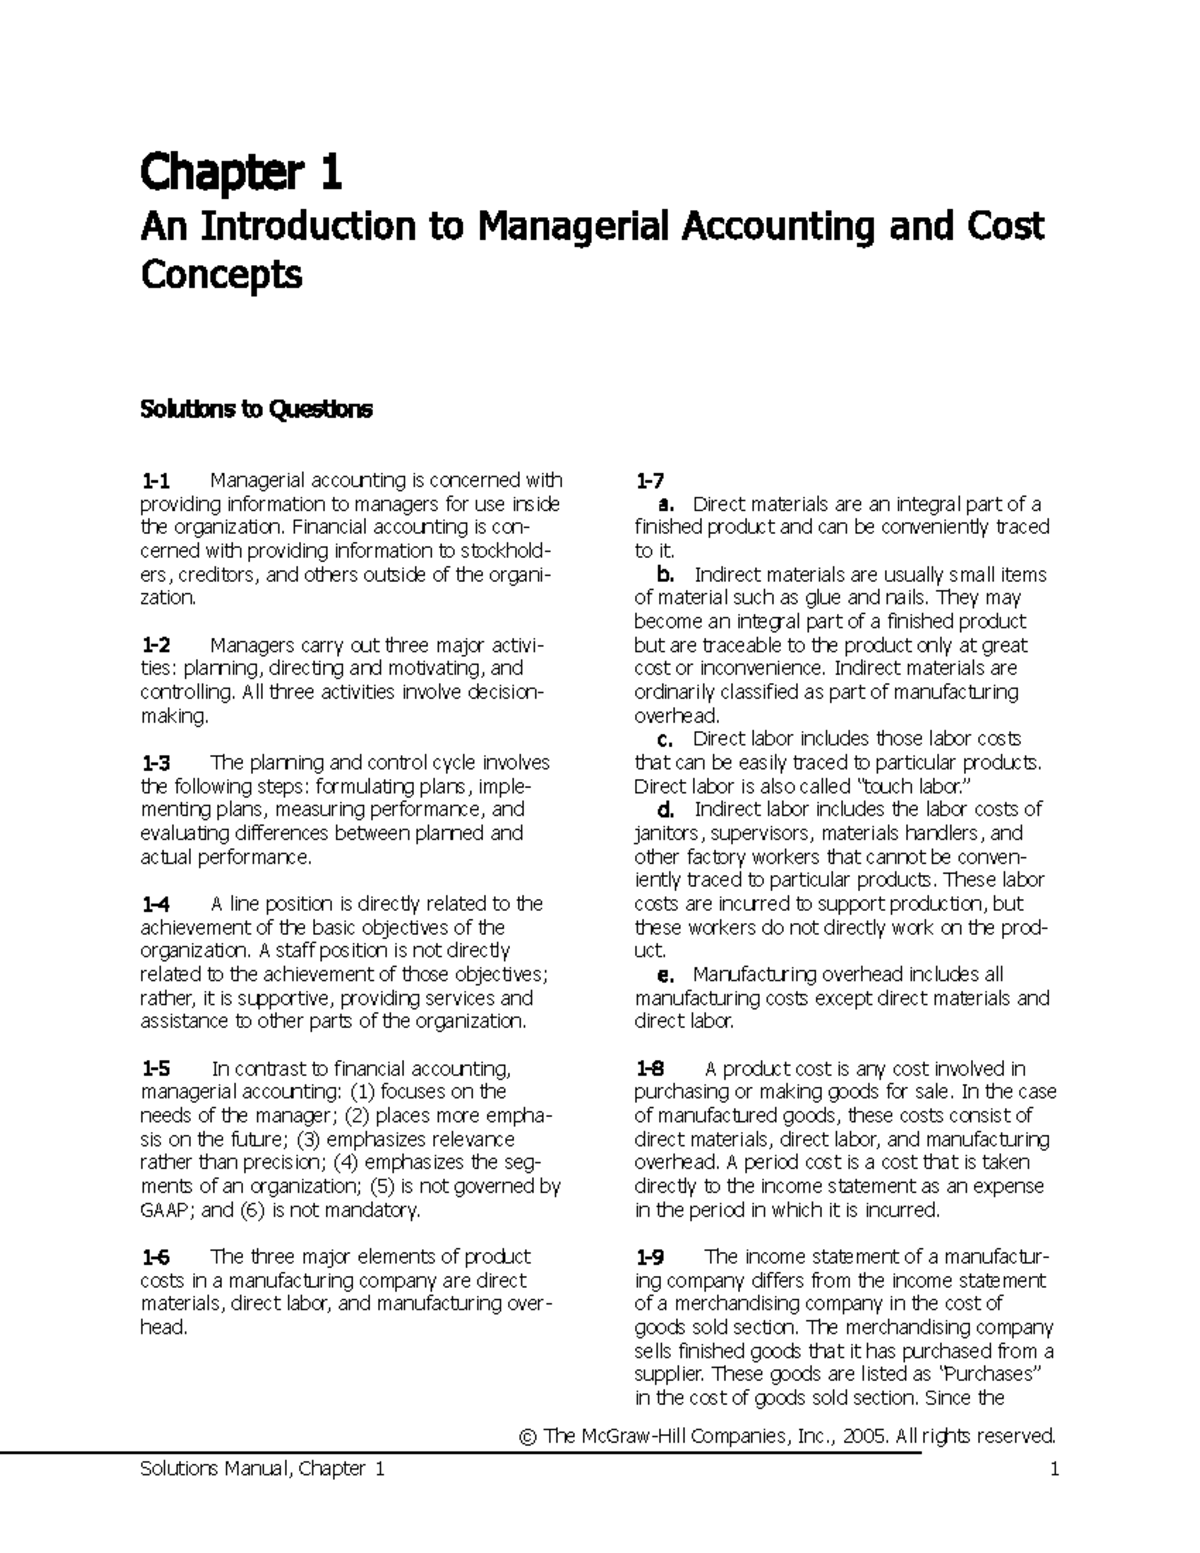
The biggest mistake I see students make is treating managerial accounting like financial accounting. In financial accounting, there is usually one right answer and it is governed by GAAP. In managerial accounting, the framework is flexible. Companies choose their own cost allocation methods. Different textbooks make different assumptions about what counts as a product cost versus a period cost. Your answer needs to match your textbook's approach, not some universal standard that does not actually exist. This is why checking your specific edition and professor's preference matters so much. I also want to mention that some of the most useful study aids are not answer keys at all. Practice problems with partial solutions where you fill in the blanks tend to be better than complete worked examples. They force you to engage with the problem rather than passively reading someone else's logic. Look for study guides that give you the problem setup and a few guided steps, then ask you to finish it yourself. If you are dealing with a specific problem right now and need help understanding the approach rather than just getting a number, that is the most productive use of your time. Take a photo of the problem, identify which concept it is testing, and work through it methodically. Variable costing income statements always follow the same format: sales minus variable costs equals contribution margin minus fixed costs equals net operating income. Contribution margin income statements look slightly different but use the same building blocks. Process costing problems always flow through equivalent units first, then assign costs to completed units and ending WIP. Once you see the skeleton of each problem type, the individual numbers become much easier to handle.
One last thing that might save you some headaches. Spreadsheet templates for managerial accounting problems are genuinely helpful if you set them up correctly. Instead of writing everything in one cell, build separate sections for given data, formulas, and results. When your answer does not match the key, you can trace exactly which input or formula is causing the drift. I use this approach in my current job when validating cost reports from different divisions. It catches errors that would otherwise take hours to find. The bottom line is that Introduction To Managerial Accounting Answers are only useful if you understand the mechanism behind them. Without that, you are just collecting numbers that will disappear from your memory within a week of the exam. Build the understanding first. The answers will follow.