What You Actually Need To Know Before Buying Another Textbook
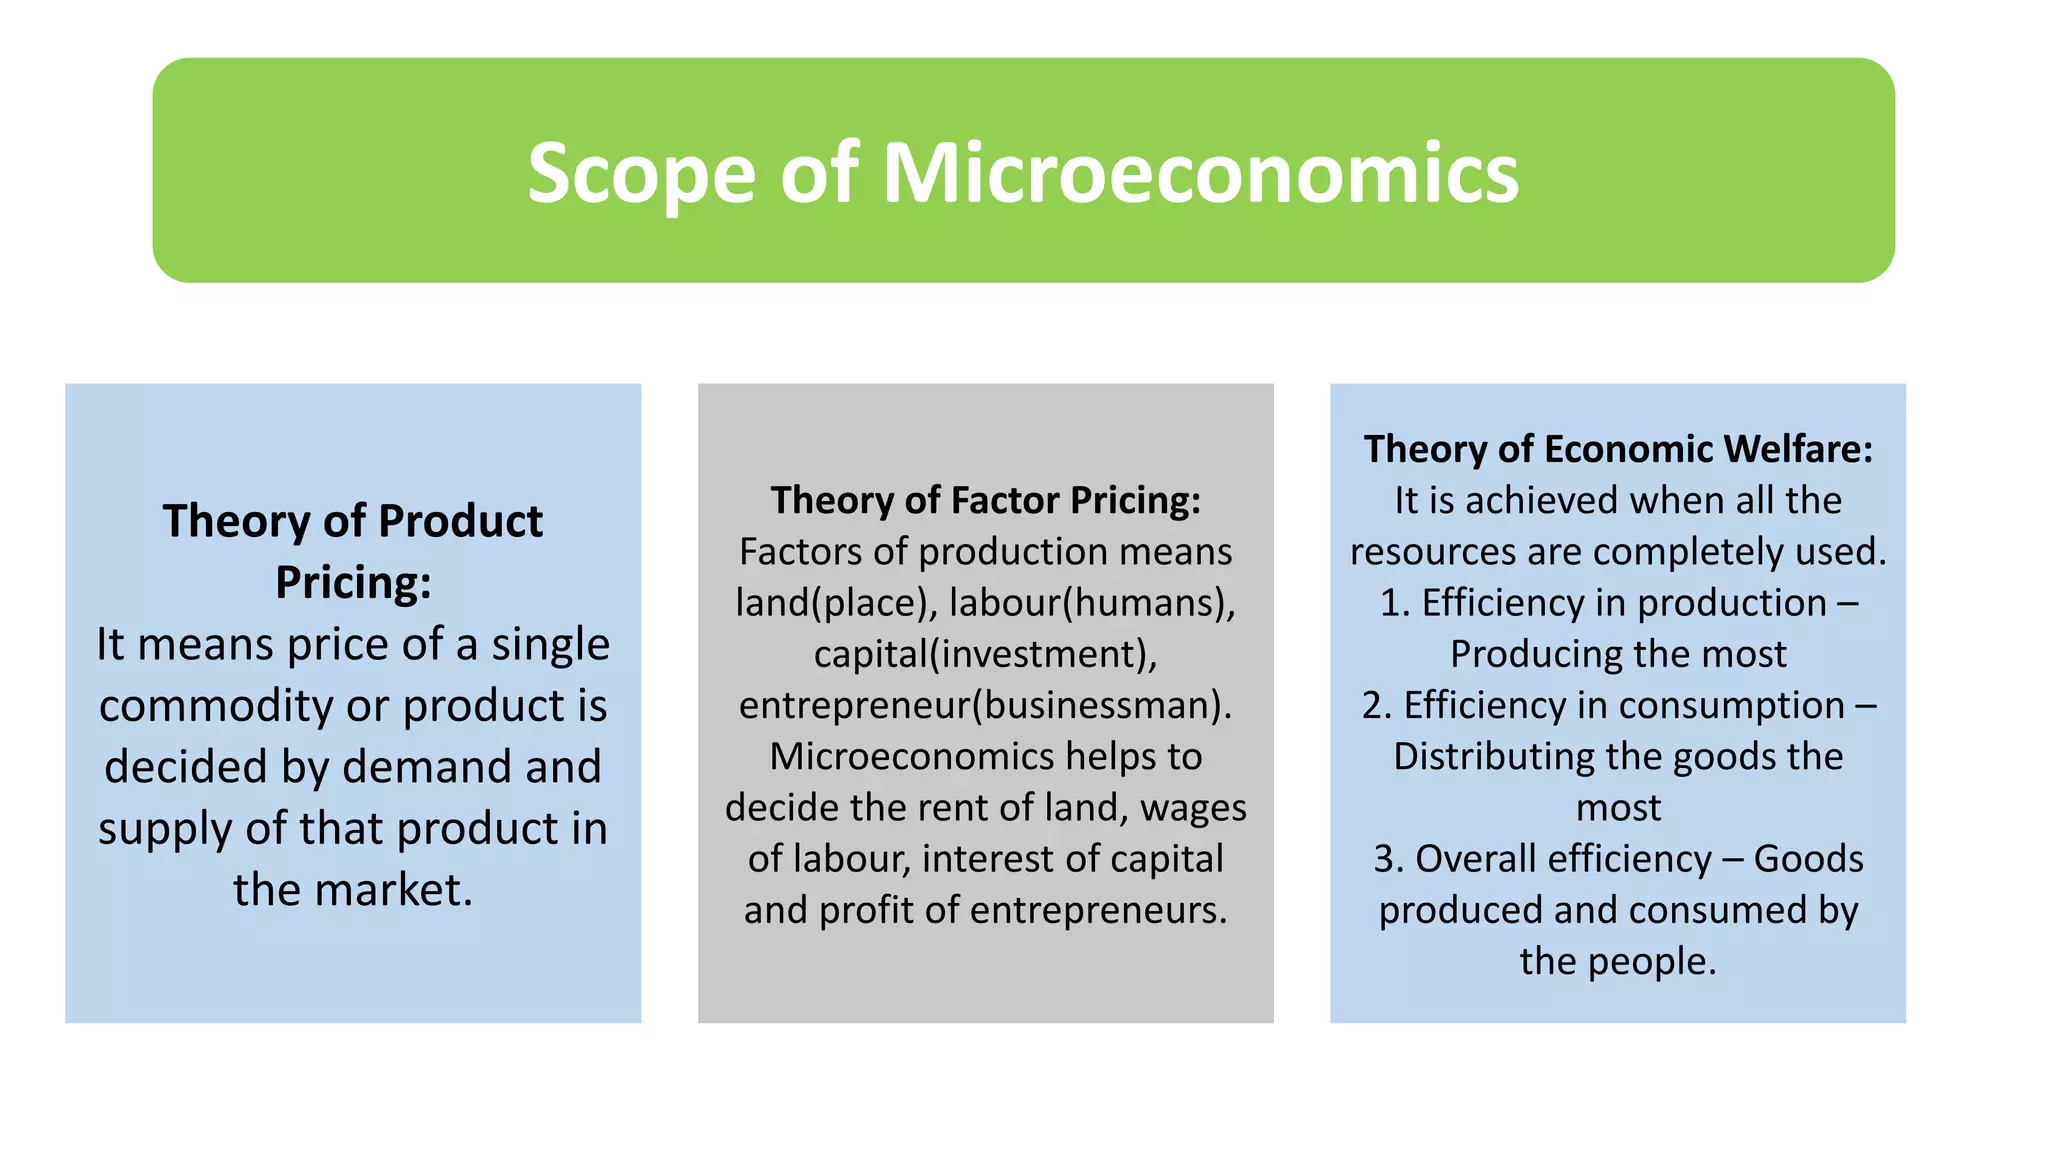
Most people approach micro and macro economics as two separate subjects that happen to share a campus building. They're not. You can't understand why a central bank raises interest rates if you've never sat down and traced how that decision ripples through a single household's budget. The textbooks pretend there's a clean boundary. There isn't one. The first thing I'd tell anyone opening this for the first time is to stop treating supply and demand curves like they're sacred geometry. They're shorthand for human behavior under constraints. That's it. A demand curve is just a bunch of people deciding how much they'll buy at different prices. A supply curve is a bunch of producers deciding how much they'll sell. Draw it on a napkin. You've done economics. I learned this the hard way during my second semester. I was working through a problem set on price ceilings for apartment rentals, trying to calculate the exact deadweight loss using the standard triangle formula. The numbers kept coming out wrong because the textbook example assumed linear supply and demand, but the real city data I pulled from the housing authority showed the curves were clearly convex. I spent three hours trying to force the standard formula to work before I just accepted that the model was too crude for that dataset. What I should have done upfront is use a numerical simulation or even just calculate the areas with basic trapezoids instead of assuming neat triangles. The insight matters more than the pretty diagram.
Here's what most intro courses gloss over: micro and macro aren't just different scales. They rest on different assumptions about how rational actors behave. In micro, we assume individuals optimize. In macro, we often assume the whole economy behaves like one giant optimizing agent, which falls apart the moment you introduce heterogeneous expectations or financial frictions. That mismatch shows up everywhere. Take the paradox of thrift — micro says saving more is sensible for one family. Macro says if every family saves more at once, aggregate demand collapses and everyone ends up poorer. The paradox only exists because the micro foundation doesn't scale up cleanly. When you're learning both tracks simultaneously, the trick is to keep a running list of where the micro reasoning breaks at the macro level. I kept a notebook titled "where does this fail?" and every time a model gave me an answer that felt wrong when I thought about the whole economy, I wrote it down. That list became more useful than any of the problem sets. Another thing nobody stresses enough: the difference between stock and flow variables. Micro teachers mention it once in chapter two and move on. Macro students who don't internalize this concept will struggle for an entire semester. Money supply is a stock. Inflation is a flow. Government debt is a stock. Budget deficit is a flow. Confusing them leads to nonsense like "we need to reduce the debt flow" when what you actually mean is the deficit flow that adds to the debt stock. Get this straight early and you'll save yourself a lot of confusion later.
If you're looking for a starting resource, Introduction To Micro And Macro Economics by Parkin is probably the most common undergraduate text for a reason. It's thorough, if a bit dry. The free resources from MIT OpenCourseWare (14.01 for micro, 14.02 for macro) are genuinely excellent and you won't spend a dime. Khan Academy still works fine for the basics, though it skims over the mathematical rigor you'll need in a proper course. For something that connects both sides more honestly, Mankiewicz's Economics covers the integration better than most, even if his writing style leans toward the conversational. The biggest trap beginners fall into is treating elasticity as a fixed number. It isn't. It varies along the curve. A linear demand curve has constant slope but changing elasticity, and students who memorize the midpoint formula without understanding that distinction will make mistakes on every exam question that deviates from perfect symmetry. Calculate point elasticity using the tangent method when you need precision. The arc elasticity formula is fine for rough estimates between two points but it's an approximation, not a law. GDP measurement has its own minefield. Nominal GDP grows when prices rise even if nothing actually gets produced more. Real GDP fixes that with a base year, but the base year gets stale and the basket of goods doesn't update fast enough to reflect new products. I once saw a student confidently argue that real GDP overstates living standards because hedonic adjustments aren't fully captured in the CPI. Technically correct, but the answer required acknowledging that no measure is perfect and that understate it too, you get the opposite problem. The Bureau of Economic Analysis does revision cycles — the first estimate for a quarter is usually wrong by a meaningful margin. Don't cite quarter-one GDP figures as fact.
Get the Full Details
Monetary policy transmission is another area where micro and macro collide awkwardly. The standard story goes: central bank buys bonds, reserves rise, interest rates fall, investment rises, output rises. In practice, when rates are already near zero, the Fed's balance sheet expanded from under a trillion to over four trillion dollars and the impact on borrowing costs for small businesses was marginal at best. The transmission channel clogged. Quantitative easing works through portfolio rebalancing and signaling, not through the textbook interest rate channel. If your course hasn't covered the zero lower bound or liquidity traps, you're missing a critical piece. For studying, don't just read the chapters. Work through the graphs yourself. Draw them from memory. If you can't reproduce the AD-AS model on a blank page without looking, you don't understand it yet — you've just recognized it. Same with the IS-LM framework. Cover the derivation and re-derive it. You'll spot exactly where your intuition is fuzzy. One practical tip: use spreadsheets for the quantitative parts. Build a simple supply-demand model where you can change parameters and watch equilibrium shift. It takes ten minutes to set up and immediately makes comparative statics feel concrete instead of abstract. I did this for a homework problem on tax incidence and realized within five minutes why the side of the market that's more inelastic bears more of the burden, something the prose explanation in the textbook had taken three pages to muddle through.
The math you actually need is basic calculus and algebra. If you're comfortable with derivatives, you can handle marginal analysis in micro. If you can solve systems of linear equations, macro's IS-LM model is straightforward. Anything beyond that — dynamic stochastic general equilibrium models, for instance — comes in graduate courses and isn't required for an introduction. Don't let the equations intimidate you. They're tools, not the subject itself. Watch out for the Phillips curve confusion. The original short-run tradeoff between unemployment and inflation got pummeled in the 1970s and the expectations-augmented version replaced it. But even that version has frayed under recent evidence where inflation ran hot with unemployment still low. The relationship isn't dead, but it's not stable either. Treat it as an empirical regularity that can break, not a structural law. I've seen too many students treat it like the laws of thermodynamics. Open economies add another layer that intro courses often rush. The Mundell-Fleming model shows how fiscal and monetary policy effectiveness depends on exchange rate regime. Under floating rates, monetary policy works well and fiscal policy is crowded out by currency appreciation. Under fixed rates, it's the opposite. This is counter-intuitive if you've only been thinking in closed-economy terms. The trilemma — you can only have two of free capital mobility, fixed exchange rates, and independent monetary policy — is the takeaway that matters. Everything else is detail.
Don't skip the behavioral economics sections even if they seem like filler. Standard models assume consistent preferences and perfect information. Real people have present bias, loss aversion, and herd behavior. These aren't quirks, they're systematic deviations that explain why markets don't always clear and why policy interventions can have unintended consequences. The 2008 financial crisis wasn't a failure of economics, it was a failure to incorporate the fact that humans aren't always rational agents. If you're self-studying, plan for about four to six hours per week over a semester to actually absorb the material instead of just skimming it. Two hours of reading, two hours of problem sets, and the rest reviewing and connecting concepts. Economies of scale, marginal utility, multiplier effects, opportunity cost — these ideas recur across topics. When you notice the recurrence, the whole subject starts feeling like one coherent framework instead of a collection of unrelated models. One final piece of advice that might sound obvious but genuinely helps: follow a few economics newsletters or podcasts in the background while you're studying. Not the opinion pieces, the ones that explain what's actually happening. Stories about a specific company raising prices, a central bank meeting, a trade policy change — these ground the abstract models in reality. It takes maybe twenty minutes a day and makes the textbook content stick far better than any amount of re-reading.