Computing The Inverse Of A 3x3 Matrix
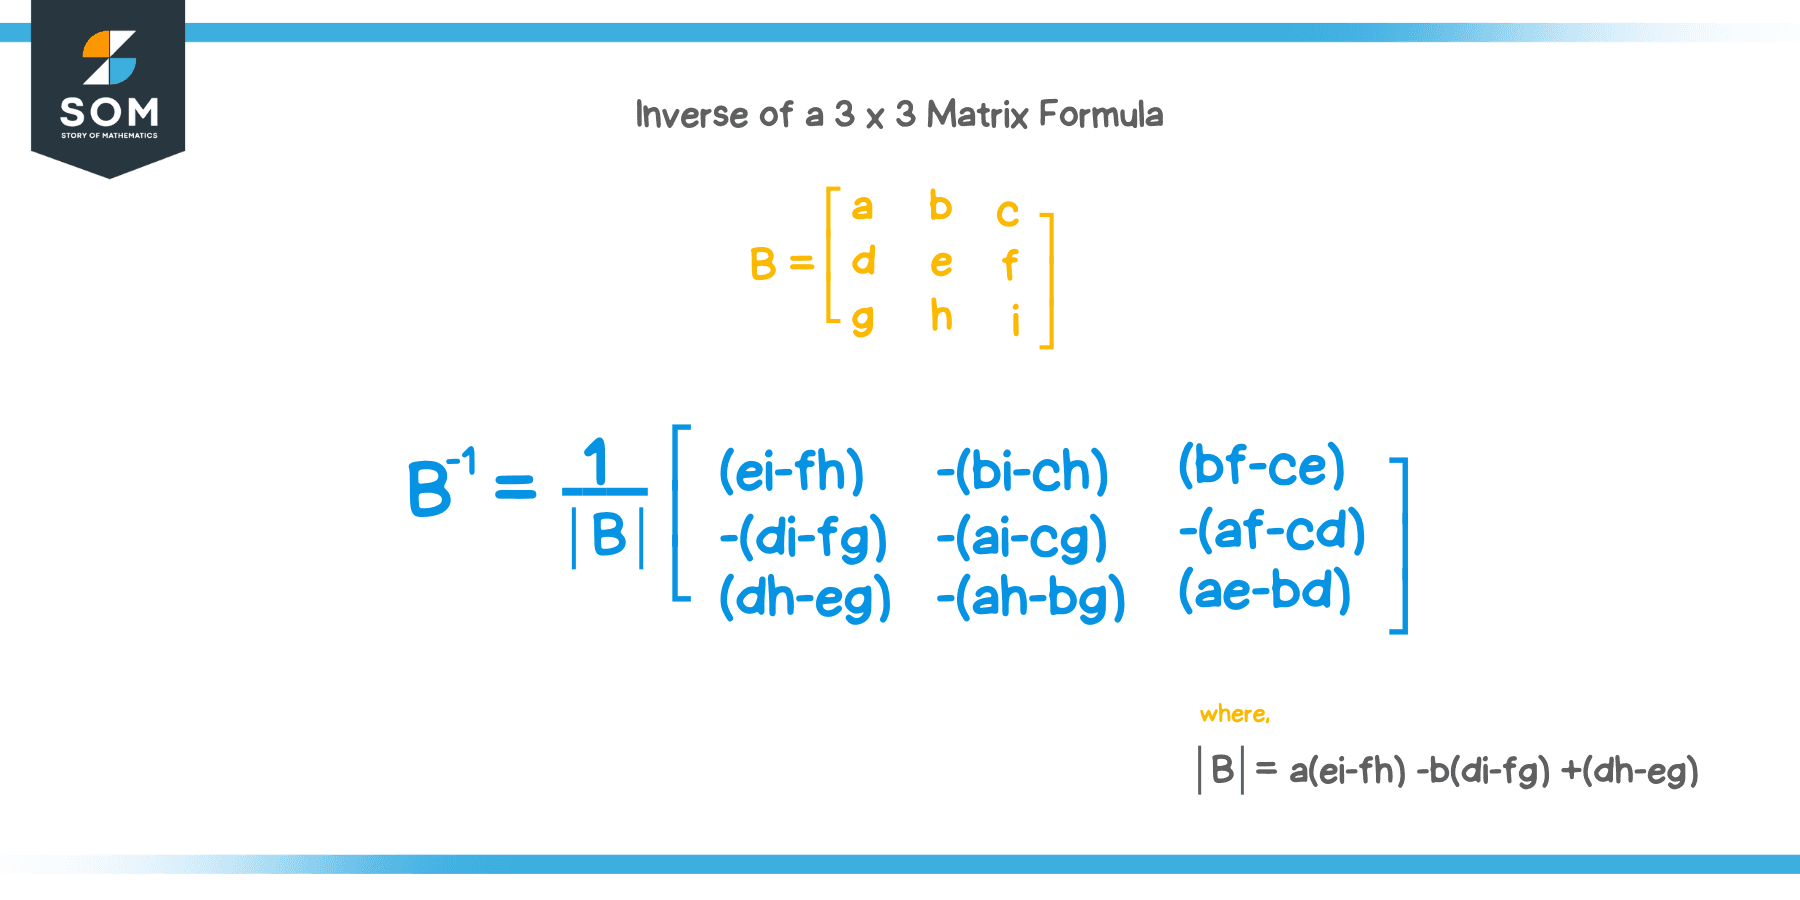
The shortcut most people learn involves the determinant, cofactor matrix, and adjugate. Here is the practical version that actually works on paper without turning your notebook into a mess. You need three things: the determinant of A, the matrix of cofactors, and the adjugate (the transpose of the cofactor matrix). The formula is straightforward: A inverse equals 1 over det(A) times adj(A). If the determinant is zero, you are done. The matrix is singular and there is no inverse. Period. No special handling needed, just move on to whatever problem you were actually trying to solve.
What People Mean When They Say Inverse Of 3x3 Matrix
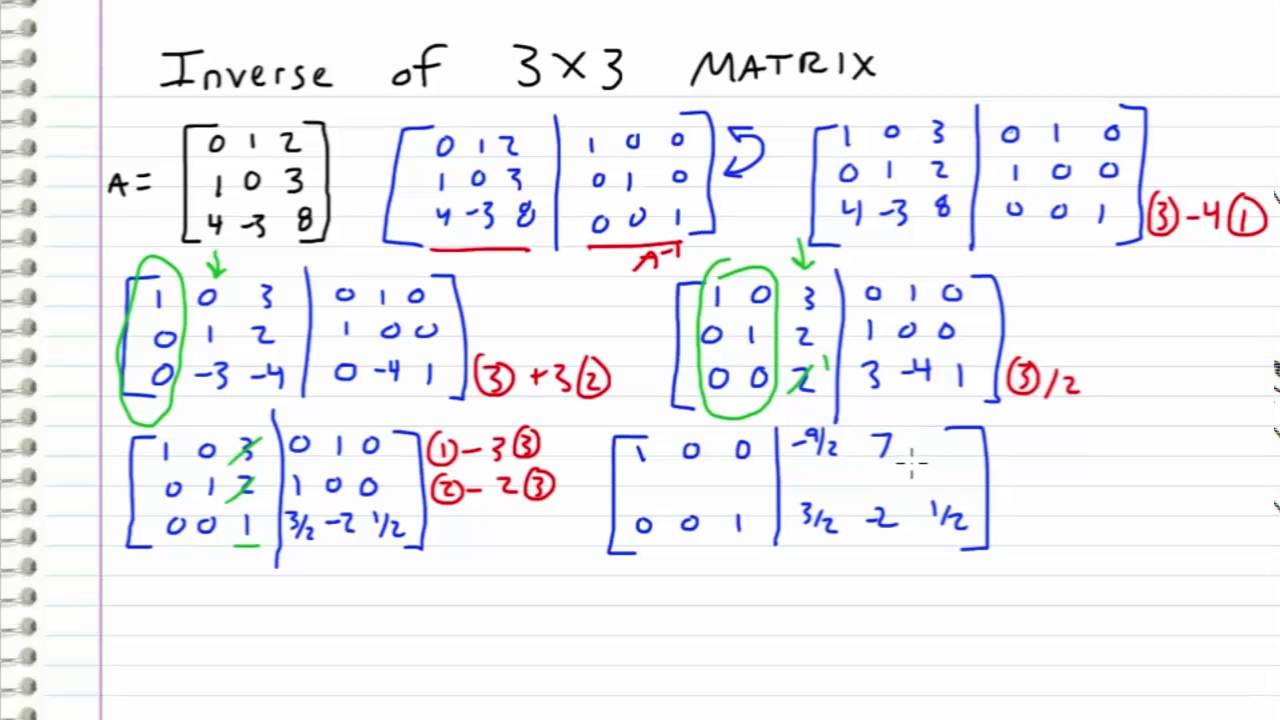
An inverse of a square matrix A is another matrix, call it A inverse, such that multiplying A by A inverse in either order gives you the identity matrix. For a 3x3, that means a diagonal matrix with 1s on the main diagonal and 0s everywhere else. It is the matrix equivalent of dividing by a number. A times A inverse equals I. That is all there is to it. The cofactor method works like this. Take your 3x3 matrix. For each element, remove the row and column it sits in to get a 2x2 submatrix. Compute the determinant of that submatrix. Multiply by plus or minus 1 depending on whether the sum of the row index and column index is even or odd. Do this for all nine positions. That gives you the cofactor matrix. Transpose it to get the adjugate. Divide every entry by the determinant of the original matrix. I have seen people skip the transpose step and wonder why their answer is wrong. The adjugate is the transpose of the cofactor matrix, not the cofactor matrix itself. This trips people up constantly. Write out the cofactors in order, then flip rows and columns before you divide by the determinant.
Worked Example
Consider this matrix: A = 2 3 1
0 1 4
5 2 3 Step one, the determinant. Using the rule of Sarrus or cofactor expansion along the first row:
Get the Full Details
det(A) = 2(1×3 - 4×2) - 3(0×3 - 4×5) + 1(0×2 - 1×5)
= 2(3 - 8) - 3(0 - 20) + 1(0 - 5)
= 2(-5) - 3(-20) + 1(-5)
= -10 + 60 - 5
= 45 Determinant is 45. Not zero, so an inverse exists. Step two, cofactors. C11 = +(1×3 - 4×2) = -5. C12 = -(0×3 - 4×5) = 20. C13 = +(0×2 - 1×5) = -5. C21 = -(3×3 - 1×2) = -7. C22 = +(2×3 - 1×5) = 1. C23 = -(2×2 - 3×5) = 11. C31 = +(3×4 - 1×1) = 11. C32 = -(2×4 - 1×0) = -8. C33 = +(2×1 - 3×0) = 2.
Cofactor matrix: -5 20 -5
-7 1 11
11 -8 2 Step three, transpose to get the adjugate:
-5 -7 11
20 1 -8
-5 11 2 Step four, divide by the determinant: A inverse = 1/45 × adj(A)
-1/9 -7/45 11/45
4/9 1/45 -8/45
-1/9 11/45 2/45 Multiply A by this result and you get the identity matrix. You can verify this by hand if you want to be sure, though it takes about ten minutes of tedious arithmetic.
Things That Actually Go Wrong
Sign errors are the most common mistake. The checkerboard pattern for cofactor signs is plus, minus, plus across each row, alternating. If you mess up one sign, the entire adjugate shifts and your final answer will be wrong. I usually compute the determinant first and use it as a sanity check. If the determinant comes out to zero after you have already computed cofactors, you made an arithmetic error somewhere, because a singular matrix is the exception, not the rule, in practice problems. Another issue is floating point precision when you do this on a computer. If your matrix entries are decimals rather than integers, rounding errors accumulate quickly through the cofactor calculations. A 3x3 inverse computed via cofactors on a standard double-precision system is usually fine for textbook problems, but real-world data with values spread across several orders of magnitude will give you garbage results. In those cases, switch to Gaussian elimination or use a numerical library that implements LU decomposition with partial pivoting. It is faster and more stable, usually completing in under a second for a single 3x3 inversion on modern hardware compared to the manual cofactor approach which takes minutes by hand. I ran into this exact problem last year when I was processing sensor calibration data. The matrix entries were measured values with noise, and the cofactor method produced an inverse that looked mathematically correct but multiplied back to something clearly not the identity within the tolerance I needed. The determinant was tiny but nonzero, around 10 to the negative 14, which signaled near-singularity. I switched to computing the SVD instead, truncated the smallest singular value, and got a result that actually worked in the downstream application. The cofactor inverse was numerically unstable for that dataset. This is worth knowing because textbooks never mention it.
When This Method Fails Completely
If the determinant is exactly zero, the inverse does not exist. There is no workaround. The matrix is singular. This happens when the rows or columns are linearly dependent. A quick check: if one row is a scalar multiple of another, or if any row can be expressed as a combination of the others, the matrix has no inverse. You will see this often in systems of equations where the equations describe the same plane or line. The inverse of 3x3 matrix simply does not exist in those cases, and you need to use a pseudoinverse or reformulate the problem entirely. Even when the determinant is not zero but is very small relative to the size of the matrix entries, the inverse will exist in exact arithmetic but be numerically unreliable. Condition number is the metric that tells you this before you invest time in the calculation. A condition number above 1 over machine epsilon means you should not trust a direct inversion at all. For double precision, that threshold is roughly 10 to the power of 16. Anything above 10 to the 12 is suspect for most engineering applications. Check the condition number first. It takes one line of code in any reasonable library and saves you from debugging a broken pipeline later.

Practical Notes
For manual computation, the cofactor-adjugate method is fine for a one-off calculation. It is clear, explicit, and shows you exactly what is happening. For repeated use, or when you are building something that inverts many matrices, use Gaussian elimination with row reduction. It scales better and is less prone to sign errors once you are comfortable with it. The time difference is negligible for a single matrix but becomes obvious if you are processing batches. Most people who need this are working in computer graphics, robotics kinematics, or structural analysis. In all three fields, a 3x3 inverse shows up constantly. The graphics people use it for transforming coordinates. The robotics people use it for Jacobian inversion. The structural analysts use it for stiffness matrix solving. The math is the same regardless of the field. The difference is in how sensitive your results are to errors in the inverse. If you are doing real-time rendering, a slightly wrong inverse causes a visual glitch. If you are calculating forces in a bridge, it causes a catastrophic failure. Pick your method accordingly. The Python implementation using numpy is roughly five lines of code and handles the numerical stability for you. The Rust or C implementation requires you to write the cofactor logic yourself or pull in a crate like nalgebra. Neither is particularly difficult, but the manual method remains useful for understanding what the code is actually doing under the hood. I still compute a 3x3 inverse by hand when I need to verify that a library function is not returning something subtly wrong. It takes about four minutes and catches issues that unit tests miss.