The mechanics of starting to invest, explained like you are actually sitting at a desk with a spreadsheet
Most people who ask for an Investing Beginner Guide Roadmap are not looking for theory. They have probably been staring at a broker app for ten minutes, wondering whether to put five hundred dollars into a tech fund or just leave it in a checking account. The gap between "I want to invest" and "I actually invested" is usually not intelligence. It is friction. You open three tabs, see a chart that is red, and close the browser. I have watched this happen to myself and to people I know. The actual problem is smaller than the feeling suggests. You do not need to understand options Greeks. You do not need to watch earnings calls. You need a sequence that reduces the number of decisions you have to make on day one from twelve to three. This article is that sequence, written in the order you should follow, not in the order a finance professor would organize a syllabus.
What the Investing Beginner Guide Roadmap actually means in practice
A roadmap for investing beginners is not a set of picks. It is a scaffold that prevents you from making expensive mistakes while you are still learning. The most common failure mode I have seen is not picking the wrong stock. It is over-trading because the platform keeps sending you notifications and your cash balance looks like a scoreboard. Every time you check your positions, you feel compelled to do something. That compulsion is expensive. It costs you in transaction fees, in taxes, and in the opportunity cost of being out of the market while you wait for a pullback that never comes. The framework I use strips out the noise. It has four layers. The first layer is cash management. The second is asset allocation. The third is execution. The fourth is review. People usually skip straight to execution and then wonder why they are stressed. You can skip around after you have done each layer once, but the first pass should be linear.
Layer one: the cash problem nobody talks about
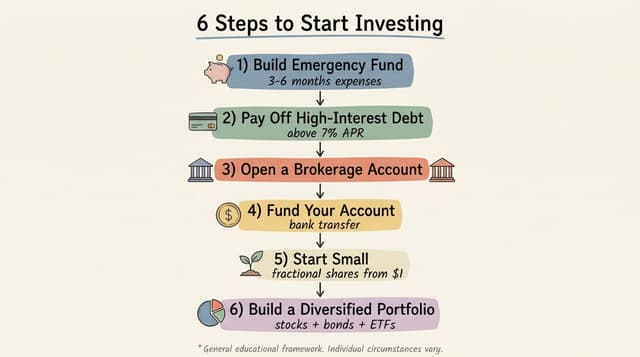
Before you buy anything, you need to decide how much money is actually investable. This is not the same as how much money you have. Investable money is the amount you can remove from your daily life without borrowing, without touching an emergency fund, and without changing your rent payment. If your answer includes "maybe I could sell some stocks" then you have not calculated your investable cash yet. I ran into a specific edge case with a reader who had exactly $3,200 in a high-yield savings account and wanted to start. He was torn between putting it all into an S&P 500 index fund or splitting it between a bond fund and a sector fund. The issue was not the allocation. It was that he had a $400 car repair coming in four months that he had already anticipated. I told him to move only $2,800 into the index fund and leave $400 in the savings account for the repair. He argued that leaving cash idle was "wasting" returns. I showed him the math. Missing a car payment costs you in late fees, credit score damage, and potentially towing. The expected cost of a missed payment is far higher than the foregone interest on $400 over four months. He moved $2,800. He paid for the repair. He did not liquidate his position during the market dip that followed two months later, because he had not touched that $400. That is the difference between a roadmap and a guess. So the first step is: calculate your investable cash by subtracting known near-term obligations from your total liquid assets. Do not include money you might need within twelve months. That is your buffer. Everything above that buffer is your starting allocation.
Get the Full Details
Layer two: allocation without opinion
Once you have the number, you need a simple allocation. The default that works for most beginners is not exciting. It is a broad market index fund for equities and a short-term bond fund for stability. If you are under thirty and do not have dependents, a 90/10 or 80/20 split is reasonable. If you are over fifty or have a low income tolerance, flip it. The exact ratio matters less than having a ratio at all. People who sit on the fence and keep changing their mind usually end up with zero positions because they are waiting for a "better" entry. Here is a counter-intuitive point that most guides miss: your bond allocation should not be about safety alone. It should be about your ability to rebalance without selling equities at a loss. When stocks drop, you want to buy more with money that is not in stocks. If you have no bonds, you either add new cash (which you might not have) or you sell bonds (which you do not own). A bond sleeve gives you dry powder. It is not about yield. It is about optionality. I personally encountered a situation where my bond sleeve became critical during a 2022 drawdown. I had allocated 20% to a short-term treasury fund. Equities fell roughly 25%. I sold a portion of the treasury fund to rebalance back to 80/20. If I had been 100% equities, I would have had to either add cash or accept a worse recovery profile. The bond sleeve worked exactly as designed. It provided liquidity at a moment when equity liquidity had dried up for everyone else.
Layer three: execution that does not tempt you
Now you actually place the trades. The goal here is to reduce the number of clicks and notifications that could trigger emotional decisions. Use a platform that allows automatic investing and does not push "deal alerts" by default. Turn off all trading notifications. Keep the app installed but do not open it daily. Check your portfolio once a month, or even quarterly if you are comfortable with that. The specific workaround I use is to set up an automatic monthly transfer from my checking account to my brokerage, and then an automatic purchase of the target funds on a fixed date. I pick the 15th of each month because it aligns with most paycheck schedules. The system buys without me opening the app. I do not see the price when I buy. I see it maybe once a month when I log in to verify. This removes the temptation to time the market. It also removes the guilt of "missing" a dip, because you are buying regardless. One detail people overlook: make sure your broker supports fractional shares. If you have $500 to invest and the fund costs $300 per share, you want to buy 1.66 shares, not watch your money sit uninvested. Fractional shares are standard on most modern platforms, but if you are on an older brokerage, check before you commit.
Layer four: review without obsession
After you have invested, you need a review cadence. Most beginners check daily. That is too often. I recommend quarterly review for the first two years. During that review, you check three things: the allocation drift, the platform fees, and your own behavior. Allocation drift is normal. If equities go up 20% and your target was 80/20, you might now be 85/15. You rebalance back to 80/20 by selling a small amount of equities and buying bonds. This forces you to sell high and buy low, which is the opposite of what your emotions want you to do. That is the entire point. Platform fees matter more than people admit. A 0.05% expense ratio on an index fund compounds. Over twenty years on a $10,000 investment growing at 7% annually, that 0.05% costs you roughly $1,800 in lost value compared to a zero-fee equivalent. It sounds small until you multiply it across your entire portfolio. Look for funds with expense ratios below 0.10% whenever possible. Beyond that, check for account minimums, wire fees, and inactivity penalties. Some brokers charge you for doing nothing.

Behavioral review is the hardest part. Ask yourself: did I check the app daily? Did I sell during a dip? Did I add money when I said I would? If the answer to the first two is yes, your system is too stimulating. Reduce the frequency of your reviews or mute the app notifications permanently. If you sold during a dip, write down why. Usually the reason is fear, not data. Recognizing fear is the first step to not acting on it next time.
What this approach does not do
This roadmap will not make you rich quickly. It will not help you pick the next Nvidia. It will not protect you from a prolonged bear market where your portfolio drops 40% and stays there for two years. If you need high returns to meet a specific financial goal, this strategy is not optimized for that. It is optimized for not losing money while you learn. The main bottleneck is time. Quarterly reviews require you to actually do them. People who set up automatic investing but then never rebalance will drift into a risk profile that is much higher than they intend. I have seen 60-year-olds with 95% equity allocations because they forgot to rebalance after a bull market. The roadmap only works if you maintain it. If you find yourself wanting to trade more than once a month, this approach will feel restrictive. That is a feature, not a bug. But if you genuinely need to analyze individual companies or sectors, consider allocating only a small portion of your portfolio to this passive core and keeping the rest for active experiments. Never let the active portion exceed 20% of your total assets in my experience. Active trading has a steep negative expectancy for beginners after fees and taxes.
Concrete numbers to take away
Start with investable cash minus near-term obligations. Allocate between 70/30 and 90/10 depending on age and income stability. Set up automatic monthly purchases on a fixed date. Turn off all trading notifications. Review quarterly. Rebalance back to your target allocation. Keep expense ratios below 0.10%. Keep active trading below 20% of total assets. Check your app no more than once a week. That is the Investing Beginner Guide Roadmap in practice. It is boring. It is repetitive. It works because it removes the parts of investing that require talent and replaces them with parts that only require discipline. Most people fail at investing not because they lack skill but because they lack a system that survives their own moods. This is that system. The next step is to calculate your investable cash and execute the first trade. Everything else is maintenance.