So You Want to Start Investing and You Found a Guide
Most people look at the word walkthrough and think they're going to be handed a complete system that solves everything. That's not how this works. An Investing Beginner Guide Walkthrough is just a structured path that lays out the order of operations for getting from zero to your first position. It removes some guesswork but it does not remove the work itself. You still need to open a brokerage account, fund it, pick a vehicle, and then actually sit with the results when the market moves against you. The walk-through itself usually covers six steps, though not every source lists them the same way. Here is how the sequence actually plays out in practice. Step one: define what you are trying to do. This sounds obvious until you meet someone who spent eight months reading about dividend growth investing, opened a portfolio, and immediately bought a leveraged ETF because it looked exciting. Write down your goal, your time horizon, and how much money you can afford to lock away for at least five years. If the number you write down would leave you sleeping badly, you picked the wrong number.
Step two: clear any high-interest debt first. If you have credit card balances above nine percent, paying those off gives you a guaranteed return higher than almost any investment will deliver consistently. I watched a friend ignore this step during 2021, pile into individual stocks while carrying about $14,000 in card debt, and then panic-sell his positions during the correction to cover minimum payments. He lost on both sides. The math is not complicated. It just requires discipline most beginners do not have yet. Step three: set up the accounts. For most American investors that means a brokerage account, possibly a Roth IRA or traditional IRA depending on income and tax situation. Firms like Vanguard, Fidelity, and Schwab all let you open accounts in under ten minutes. Do not overthink the choice between them at this stage. Pick one, fund it, and move on. The differences at the beginner level are minor and the worst mistake you can make is staying paralyzed while waiting for the perfect platform. Step four: choose your investment vehicle. Beginners usually land on three options: broad index funds, individual stocks, or target-date funds. Index funds like VTI or VOO give you instant diversification. Target-date funds set the glide path for you and require almost no attention. Individual stocks are where most first-money gets damaged. Unless you have a real edge or enjoy reading balance sheets for fun, the other two options exist for a reason.
Step five: dollar-cost in and automate. One lump sum historically outperforms dollar-cost averaging about two-thirds of the time, but that stat means nothing if you are a person who needs to sleep at night. Automate a monthly contribution, even if it is only fifty or one hundred dollars. The habit matters more than the amount when you are learning. Step six: do not touch it for a while. This is the part nobody advertises. Checking your portfolio daily turns normal volatility into emotional trauma. Most beginners who check constantly either sell too early out of fear or buy too late out of greed. Keep your contributions automatic. Rebalance once a year if needed. Ignore the noise. I ran into a specific problem a few years ago that nobody warns you about. A reader was following a beginner walkthrough verbatim, bought a popular total-market fund, and then realized their employer's 401k already held an identical fund. They were getting zero diversification benefit from the second purchase and were paying duplicate expense ratios without noticing. The workaround was simple: pull up the prospectus for every holding across all accounts, merge overlapping funds into the lower-cost option, and redirect new contributions to whatever asset class was missing. It took about twenty minutes and saved them from a quiet compounding drag that would have been invisible for years.
Get the Full Details
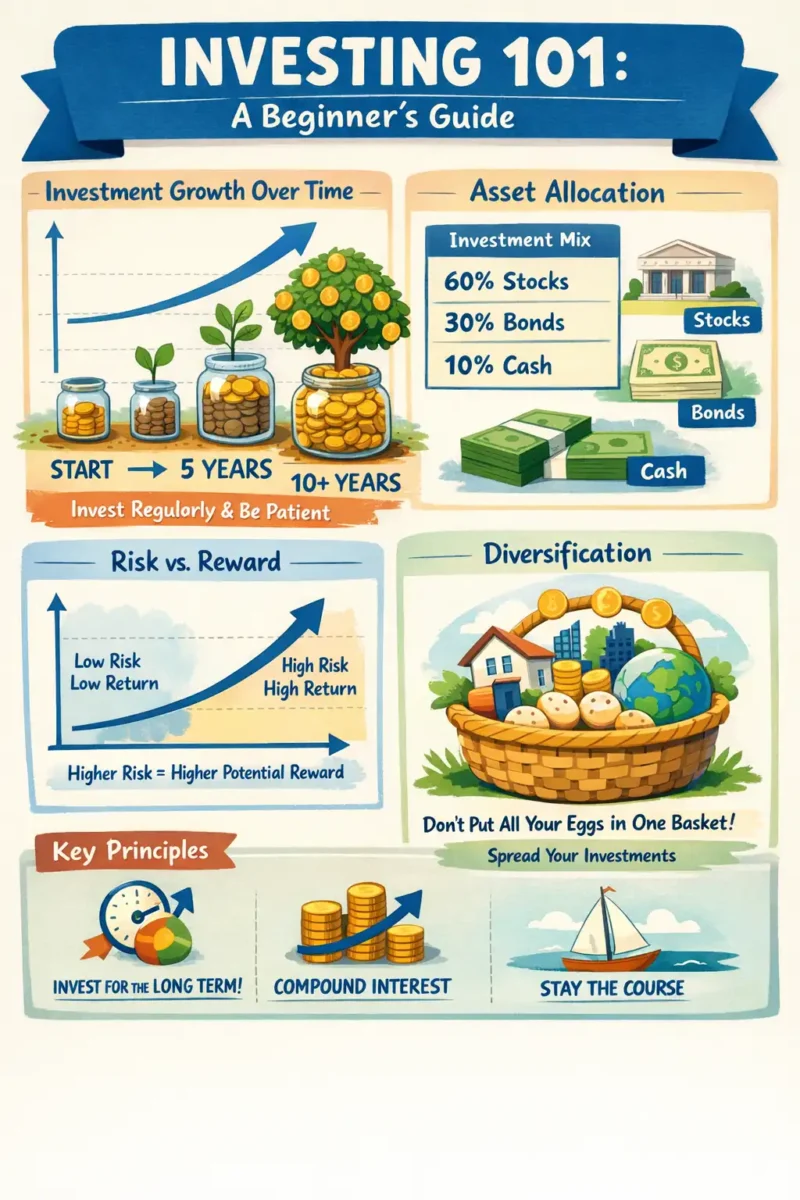
Here is something counter-intuitive that most guides skip: being diversified does not protect you from sequence-of-returns risk during retirement, and it does not stop you from making the same behavioral mistakes in different wrappers. You can hold twenty individual stocks and call yourself diversified while carrying enormous single-name risk. You can also hold a perfectly balanced portfolio and still underperform because you chased hot sectors, traded frequently, or bought during FOMO spikes. The math works in your favor only if the behavior stays boring. Another nuance beginners miss is the difference between gross expense ratio and total cost of ownership. A fund might advertise a 0.03 percent expense ratio, which sounds negligible, but if it has poor tax efficiency, high turnover, or tracks a niche segment with wider bid-ask spreads, your actual after-tax return drops further than the brochure suggests. For long-term holders, tax-efficient fund placement matters more than shaving two basis points off a total-stock index fund's fee. Put internationally developed markets and REITs in tax-advantaged accounts when you can. Keep broad US equity funds in taxable accounts. There are real downsides to treating a beginner walkthrough like a finished product. These guides assume you have some disposable income, access to a brokerage, and the ability to absorb short-term paper losses without panicking. If you are working two jobs with irregular income, a rigid monthly contribution plan will fail. In that case, a pay-it-as-you-can approach with a simple money-market or high-yield savings buffer alongside a tiny fractional share position is more realistic. Also, these walkthroughs rarely address the scenario where you inherit a messy portfolio or inherit accounts with cost-basis tracking issues. I had a client once who inherited a brokerage account with over sixty lots purchased at wildly different prices over twenty years. The walkthrough advice about buying and holding meant nothing until we spent three weekends reconstructing lot-level cost data and identifying wash-sale violations from prior years. It was a logistical nightmare that no beginner guide covers.
Performance expectations deserve blunt treatment. The S&P 500 has averaged roughly ten percent nominal annually over long periods, but that average includes periods where the index dropped forty percent or more. If you need the money within three years, equities are the wrong place for it. A high-yield savings account or short-term treasuries are more appropriate. The guide will tell you to invest. It should also tell you when not to. If you want a concrete next step, open a brokerage account this week, set up an automatic transfer for whatever amount feels survivable, buy a single low-cost total-market index fund or target-date fund matching your retirement horizon, and then close the app. Check back in six months. Read one decent book on behavioral finance instead of another tutorial. The gap between people who succeed at investing and people who fail is rarely a better guide. It is usually just someone who kept showing up without trying to outsmart the system.