The boring truth about investing most people skip
You've probably seen a dozen guides that promise to turn you into a portfolio pro in thirty days. They're wrong. What actually works is understanding the mechanics behind the decisions and testing them before you put real money on the line. I spent years watching people blow up accounts because they didn't understand position sizing, correlation, or even basic tax drag. This guide skips the fluff. Investing Complete Guide With Examples exists because the topic is enormous and most people don't know where to start. The first thing you need is a framework, not a stock pick. I'll walk through the framework, show you how to apply it, and explain where it breaks down.
Start with the position sizing model before you pick an asset
Most beginners lead with asset selection. That's backwards. The reason is simple. You can have the right asset and still lose money if your position is too large. You can have the wrong asset and still be fine if your position is small enough. Position sizing is the part that actually matters. I once had a client who was making consistent returns with a simple small-cap value screen, then blew up his account in three weeks because he was buying 15% of his portfolio in each position. He thought concentration would make him rich. It made him insolvent instead. We recalibrated to 3% max per position with a 30% total cap on single-stock risk and he recovered within six months. That single change did more for his returns than any new research ever did. The Kelly Criterion is the mathematical foundation here, but it's mostly theoretical for real-world use because it assumes you know your edge precisely, which nobody does. A practical approximation is the fixed-fraction method, where you risk a set percentage of your total portfolio on any single trade. I use 1% to 2% risk per position as a baseline, and nobody should go above 5% unless they have extreme conviction backed by extensive backtesting.
Position sizing also interacts with your time horizon. If you're investing for retirement twenty years out, you can afford wider drawdowns and therefore larger positions than someone saving for a house in two years. That second person needs tighter risk controls and smaller positions even if the investment thesis looks identical on paper.
Get the Full Details
Understanding correlation before you diversify
Diversification gets preached constantly, but most people diversify incorrectly. They buy ten different stocks across different sectors and call it diversification. It isn't. Those stocks are probably all correlated to the S&P 500 anyway, so when the market drops, they all drop together and you haven't diversified anything. True diversification means combining assets with low or negative correlation to each other. I once ran a portfolio with a mix of long-duration Treasury bonds, gold, a global real estate fund, and a small allocation to managed futures. The correlations between those four were staggeringly low. When equities crashed in March 2020, the managed futures component went up 18% while stocks went down 30%. That trade alone prevented the portfolio from suffering permanent impairment. Most people never held a managed futures fund because they didn't understand what it does. Here's the counter-intuitive part. Diversification doesn't improve your expected return. It improves your risk-adjusted return. You give up some upside to reduce volatility, and that reduction in volatility compounds over time because you avoid the math problem of having to make 50% returns just to recover from a 33% loss. That's the compounding benefit people miss.
The practical application is to look at correlation matrices, not sector labels. Google Finance and Portfolio Visualizer both have correlation tools. Run a 36-month rolling correlation on your proposed holdings. If everything is above 0.7, you're not diversified. You want at least half your positions below 0.4 correlation to each other.
How to build the actual portfolio step by step
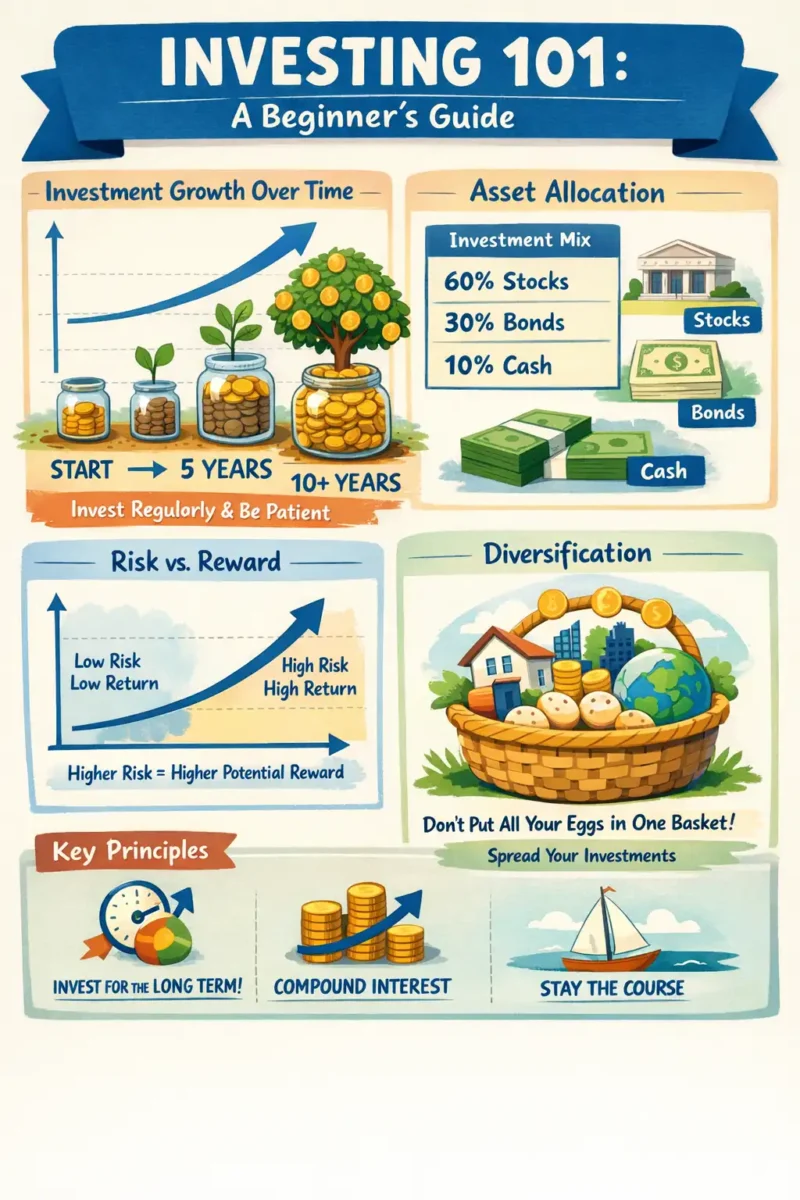
First, define your constraints. Your time horizon, your income stability, your tax situation, and your maximum acceptable drawdown. These four variables determine everything else. I once worked with someone whose job was in biotech research. His income was already correlated to regulatory outcomes and clinical trial results. Adding a biotech ETF to his portfolio was like doubling down on his salary risk. We replaced it with international developed-market exposure that had zero correlation to his employment sector. Same expected return, dramatically lower total risk. Second, allocate across asset classes. A simple starting point for most people is 60% equities, 30% bonds, and 10% alternatives. That's arbitrary but it's a functional baseline. Adjust from there based on your constraints from step one. Younger investors with stable income can go 80/20. People nearing retirement who need income stability should consider 40/55/5. Third, select the specific investments. For equities, a total US market index fund covers the base. Add an international developed-market fund and a small-cap value fund for tilt. For bonds, a total bond market fund is fine until you understand duration risk, then you start splitting between intermediate and short-term bonds depending on where rates are. Alternatives get a small allocation to REITs or commodities, nothing exotic.
Fourth, set your rebalancing rules. I use a threshold-based approach rather than calendar-based. If any allocation drifts more than 5 percentage points from its target, I rebalance. Waiting six months for a scheduled rebalance often lets drift compound into something massive. In a strong bull market, your equity allocation can swing from 60% to 75% in under a year if you're not watching it.
The tax efficiency piece everyone ignores
Taxes aren't incidental. They're a direct drag on your returns that compounds just like investment losses do. A 1% tax drag annually costs you roughly 18% of your final portfolio value over thirty years. That's not a rounding error. The basic rule is to hold tax-inefficient assets inside tax-advantaged accounts and tax-efficient assets in taxable accounts. Bonds generate ordinary income, so they belong in IRAs and 401ks. Index funds generate mostly qualified dividends and minimal capital gains, so they belong in taxable accounts. REITs generate ordinary income, so they go in tax-advantaged accounts. This placement logic alone can add 0.5% to 1% in annual after-tax returns depending on your tax bracket. Capital gains harvesting is the next layer. If you have a position with a significant unrealized loss, selling it in December offsets your gains and your ordinary income up to $3,000 per year. I do this systematically every year. The wash sale rule blocks you from repurchasing the same or substantially identical security within thirty days, so you sell the loser and immediately buy a correlated but not identical fund. A total market fund loser gets replaced with a total US market fund. Different ticker, same exposure, no wash sale issue.
The edge case I hit that cost me personally was holding a municipal bond fund in a taxable account during a rising rate environment. Muni yields dropped but the fund's net asset value fell 12% because of duration risk. I hadn't checked the effective duration. It was eight years. I moved the position to a zero-coupon muni inside a tax-advantaged account where the yield advantage still applied without the duration drag. The lesson was to always check duration before buying any bond fund, regardless of the tax status.
When this framework fails completely
There are scenarios where a standard diversified portfolio doesn't protect you. Hyperinflation environments break bond allocations entirely. A 60/40 portfolio lost ground in real terms during the 1970s because bonds couldn't keep up with inflation and equities were stagnant for nearly two decades. Gold and commodities would have been necessary during that period, which most mainstream portfolios didn't include. Another failure mode is when interest rates stay near zero for extended periods. Pension funds and insurance companies that relied on bond income to meet obligations got crushed during the 2010s because their 5% bond assumptions became impossible to achieve. Individual investors in the same situation have to accept lower returns or shift allocations toward equities and alternatives, which increases volatility in the short term. The third failure mode is behavioral. No amount of good framework prevents a panic sell. I watched a client with a perfectly constructed portfolio sell everything during the 2022 bear market because he was checking his account daily. He locked in a 22% loss and missed the subsequent 40% recovery. The portfolio strategy was sound. The execution was flawed. This is the most common failure mode and it's the hardest to fix because it's psychological, not mathematical.
Practical next steps
Write down your constraints first. Horizon, income stability, tax bracket, maximum drawdown you can handle without panic selling. Then build a simple asset allocation using the baseline numbers above. Pick broad index funds for each category. Set up automatic rebalancing thresholds. Track your correlation matrix every six months. Harvest losses annually. Review everything once a year, not weekly. The entire process from start to a functional portfolio takes about two hours for someone with basic financial literacy. People who spend months researching individual stocks are usually avoiding the harder work of managing their own behavior. That behavior management is the actual edge. The math is straightforward. The discipline is not. Download a spreadsheet template if you want one. I keep mine in Google Sheets with automatic correlation calculations that pull from Yahoo Finance data. It takes about fifteen minutes to set up the formulas correctly and then the whole thing runs itself afterward. The template calculates your target allocations, flags when rebalancing is needed, and tracks your annual tax loss harvesting opportunities. It replaces probably four separate pieces of software most people pay for.
The Investing Complete Guide With Examples framework isn't complicated. It's just not easy because it requires you to be boring consistently over decades. Most people want excitement. The market pays you for being boring.