What most people get wrong about building an investing guide
I spent about three years compiling what I thought was a solid pocket guide for everyday investors. The first version came out in 2018 and I immediately regretted it. Not because the content was wrong, but because it was written for a version of the market that barely exists anymore. The cost of entry has shifted. The psychology has shifted. The biggest mistakes people make when trying to build their own quick-reference investing material aren't about math. They're about comfort.
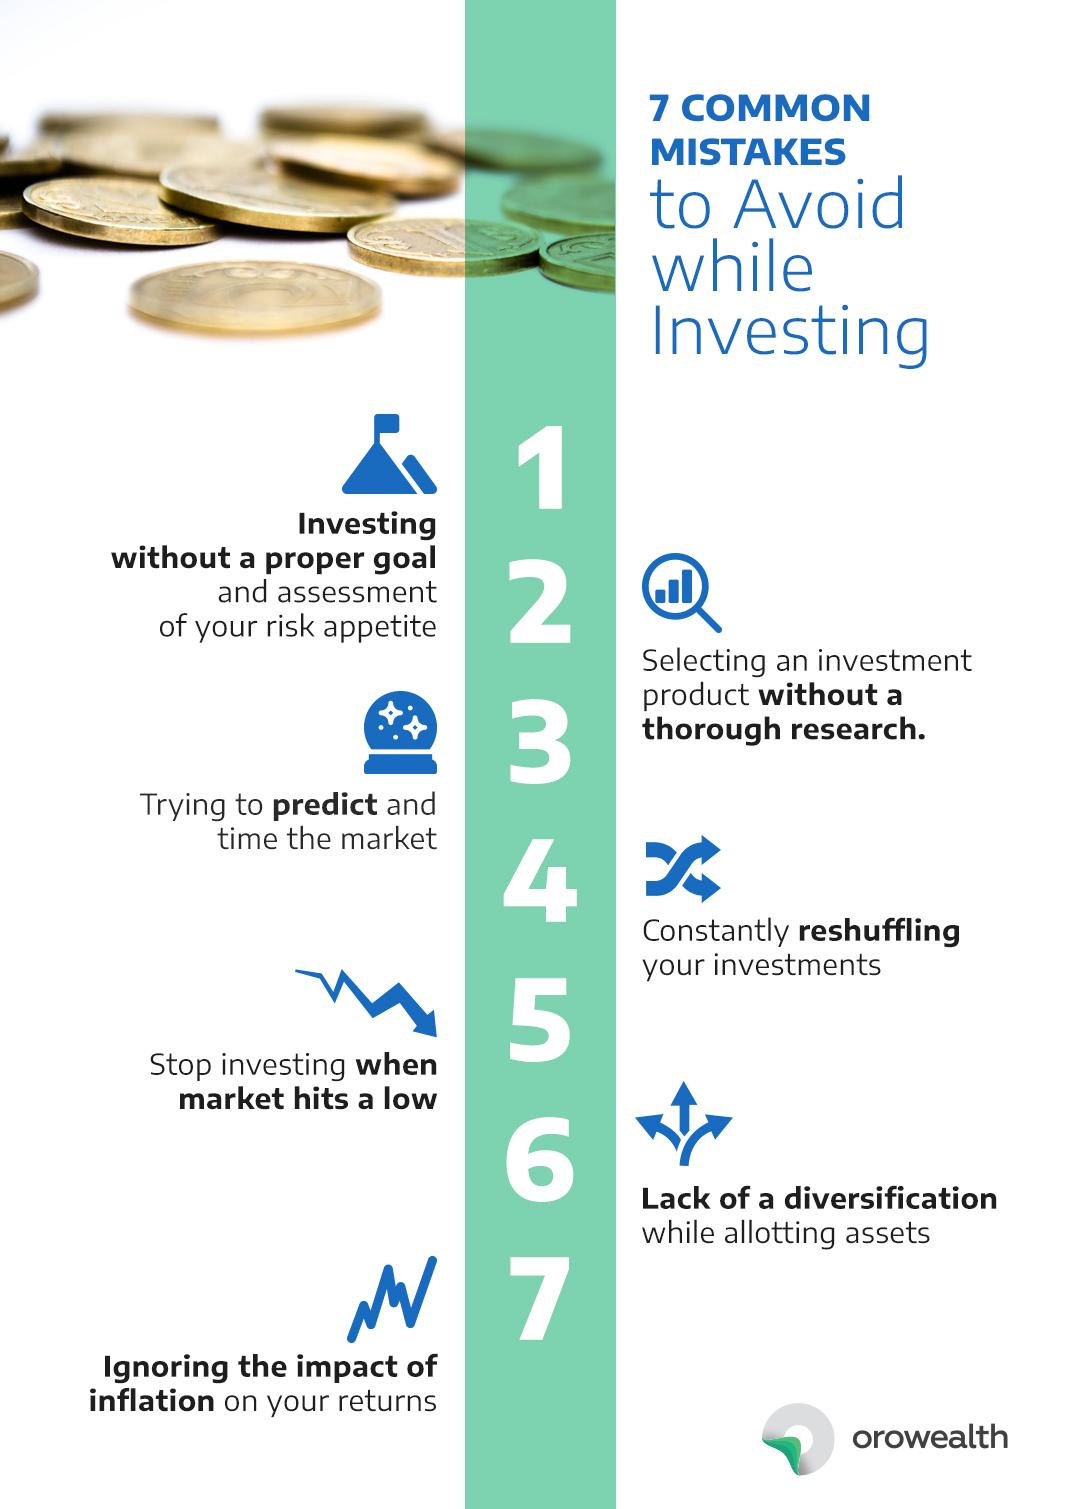
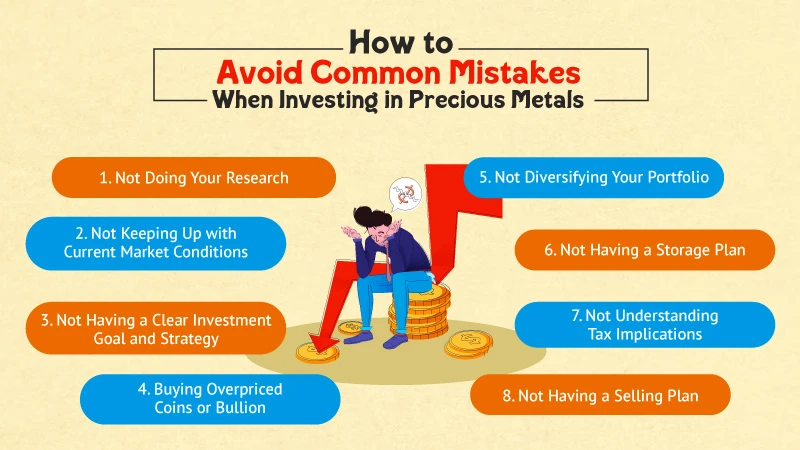
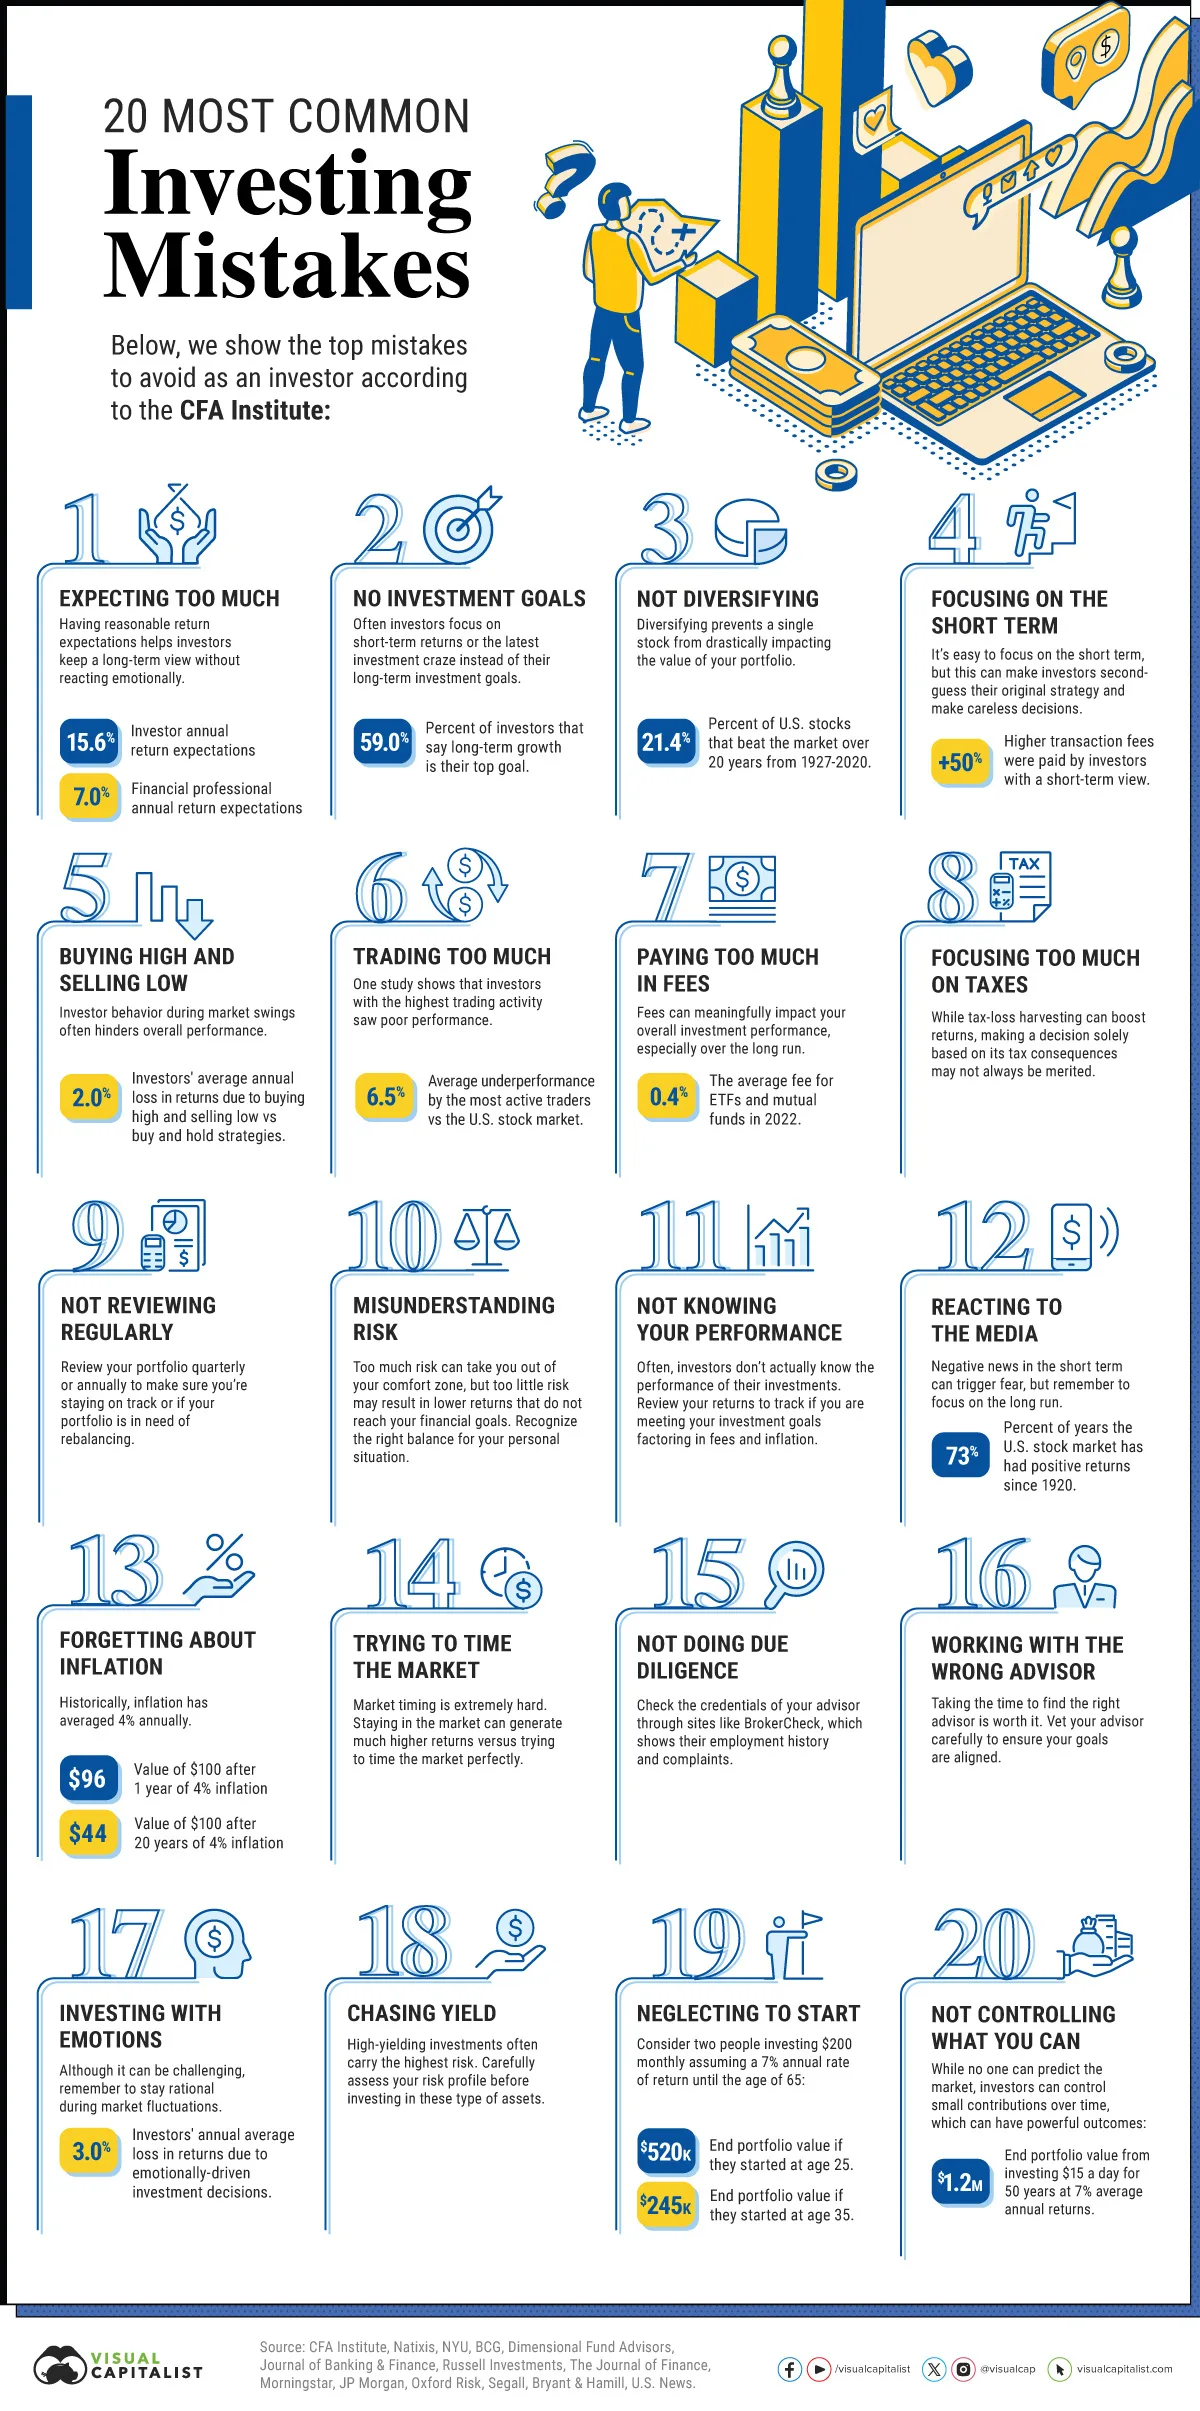
Investing Pocket Guide Common Mistakes To Avoid
Mistake one: treating all assets as if they behave the same way during a drawdown.I saw this repeatedly in my own notes. I would list bonds and dividend stocks side by side as "stable income." That's wrong. Bonds don't behave like dividend stocks in a rising rate environment. In 2022 I watched a portfolio that was supposedly "balanced" lose nearly 34 percent in a single year because the bond allocation moved in lockstep with equities during that particular inflation cycle. My guide still had them grouped together under the same risk bracket. I had to scrap the whole document and rebuild the framework. One workaround that actually stuck: I started categorizing holdings by their correlation profile rather than by asset class. It's more tedious. It means running a rolling 60-day correlation matrix between your largest positions. But the output is honest. Positions that move together under stress show up clearly instead of hiding behind different labels. Mistake two: writing the guide as if you'll ever need it during a crisis. Nobody reads their own investing notes while the market is down twenty percent. You grab your phone and do something impulsive. I learned this the hard way in early 2020 when I had a beautifully formatted PDF sitting in my cloud storage and I couldn't find it for forty minutes while panic selling through my brokerage app.
The fix is simpler than people think. Put your guide on paper. Physical notebooks are still faster to flip open than any digital file on a stressed device. I keep a single index card at the front of my primary notebook with the core rules that I refuse to break. Not a full guide. Just the absolute non-negotiables. That card has survived three market resets because it was already on my desk.
Structure mistakes that compound faster than fee drag
I used to organize guides by topic. Definitions, then examples, then procedures. Very clean. Very useless. The problem is that real investing decisions don't arrive in topic order. You get a headline. You get a fear signal. You get confused. A topical structure forces you to remember which section contains the answer you need under pressure.Get the Full Details

I switched to organizing by decision trigger instead. When your portfolio drops X percent, check this. When your allocation drifts beyond Y, do this. When you hear about a new asset class in the news, look here. It's uglier. It looks less like a traditional guide. But it actually matches how decisions happen in practice. Another structural error I keep seeing: including too many edge cases in the main text. Every exception you add slows down retrieval. I had a fifteen page section on tax loss harvesting in my first draft. By page eight, even I stopped reading ahead of time. I moved all the edge cases to an appendix and kept the main section to three pages with clear callouts. The appendix sits there for reference. Most people never need to go there.
The one mistake that costs real money
People treat their investing guide as advice rather than a process. There's a difference. Advice is a conclusion. A process is a sequence of steps that produces the conclusion. I watched a reader of one of my early posts try to follow a simplified version of my guidance during a sector rotation in 2021. He applied my recommended allocation targets directly without checking the time horizon filter first. He ended up overexposed to a sector that was already priced for perfection. The strategy wasn't wrong. The sequence was wrong. The workaround I use now is a mandatory gate checklist before any allocation decision. Three questions. Is this the right time horizon? Is the current valuation within one standard deviation of the trailing average? Is this decision driven by a rule I wrote or by a new piece of information that changes one of those three conditions? If the answer to all three is no, you don't act. This catches more false signals than almost anything else I've tried. It also catches the signals you actually care about when they arrive.
What to include and what to deliberately leave out
Your pocket guide should contain exactly three things: your personal risk parameters, your rebalancing rules, and your emergency exit criteria. Everything else is noise. Risk parameters should be written as hard numbers, not ranges. "I tolerate a maximum drawdown of twelve percent" is better than "I can handle moderate volatility." Rebalancing rules need a trigger and a method. A common trigger is allocation drift exceeding five percentage points from target. The method is either partial rebalance back to target or full rebalance, and you should pick one and write it down. Most people switch between methods depending on mood. That's not a system. That's gambling with extra steps.
Emergency exit criteria are the hardest section to write honestly. I recommend listing specific price levels or fundamental thresholds that would force a position sale regardless of sentiment. The moment you define these in advance, you remove the emotional component from the moment it matters.
When the guide fails and what to do instead
No pocket guide works during a liquidity crisis. The correlation structure changes, historical averages become meaningless, and your own risk parameters become irrelevant because the market stops respecting them. I experienced this firsthand during the March 2020 liquidity event. My own rebalancing triggers would have forced me to sell into a market that was already pricing in tail risk. The guide said one thing. The market was doing something completely different.The only safeguard that helped was keeping a cash buffer that was large enough to absorb the initial shock without touching investment positions. I size this buffer as a separate allocation, not as leftover change. Twenty percent in short-term instruments was my minimum threshold after that episode. It reduces compounding during normal periods. It prevents permanent loss during abnormal ones. If you find yourself writing a guide that runs longer than twenty pages, cut it. The length itself is a signal that you've included information you don't actually need. Compression forces you to identify what is essential versus what feels important. Essential wins every time.
Download note
I do not distribute a single downloadable file for this material because the guide needs to reflect your actual risk parameters, which I cannot know. The framework above is the structure. Fill in the numbers yourself. Update the document quarterly. If a section hasn't been relevant in two years, delete it. A living guide is worth more than a polished PDF that nobody reads.