Portfolio Construction Without the Fluff
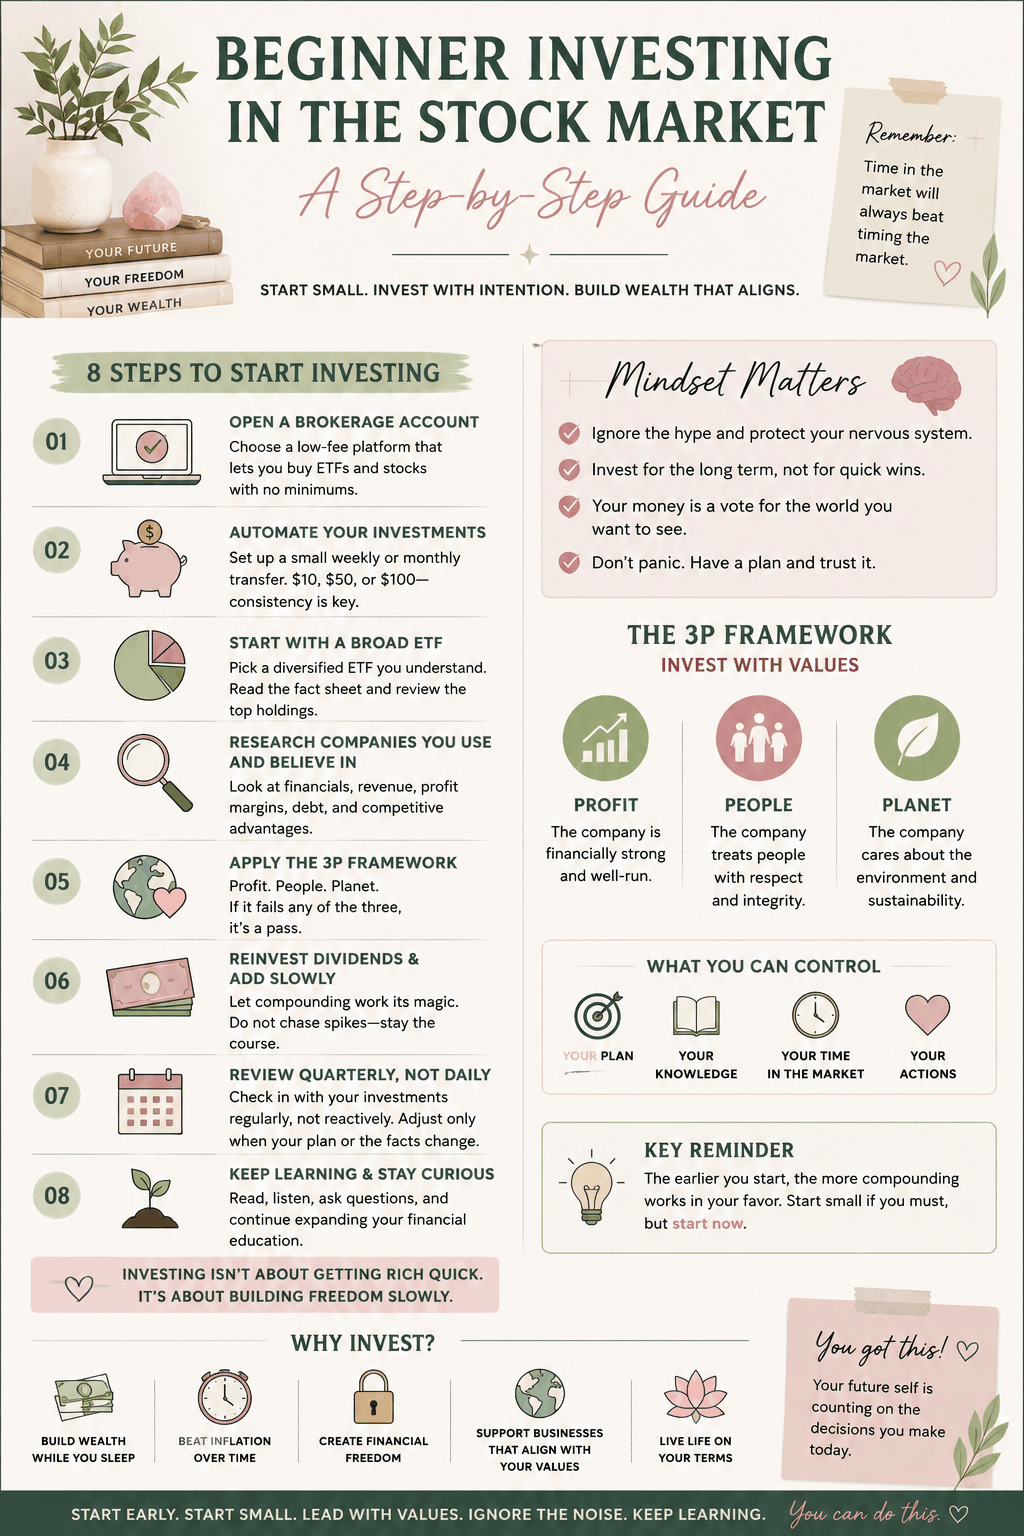
Most people start investing by Googling which stocks to buy. That approach ignores the part that actually determines whether you finish with money or not. A structured framework beats picking individual names every time, mostly because behavioral mistakes destroy more wealth than bad asset selection. Here is the practical breakdown I use when someone asks me to walk them through setting up a portfolio from scratch.Investing Step By Step Guide Cheat Sheet
Step 1: Emergency Fund (Do This First) Before any investment dollar moves, you need three to six months of bare-bones living expenses sitting in a high-yield savings account. I cannot stress this enough because I watched a friend liquidate half his 401k during the 2020 crash to cover rent when his income disappeared. The penalty, the market timing loss, the psychological damage — it was avoidable. Keep this money separate. Do not confuse your emergency fund with a "just in case" bucket tied to your brokerage. Step 2: Close High-Interest Debt
If you carry credit card debt above eight percent, paying it down is a guaranteed return higher than anything available in the market. I know it feels counterintuitive to invest while owing money, but the math does not care about your optimism. Once that debt is gone, redirect those monthly payments into investing. Step 3: Capture the Employer Match This is free money and the single highest-return move available. Contribute enough to your workplace retirement plan to get the full employer match. If your company matches 50 percent up to six percent of salary, you contribute six percent. Anything less and you are walking away from a 50 percent return on that portion. I have seen people skip this for years and then wonder why their retirement balances look pathetic compared to peers.
Step 4: Max Out Tax-Advantaged Accounts After the match, push into whatever account structure makes sense for your situation. The priority order for most people is Roth IRA, then maxing the 401k or 403b, then back to a Roth IRA if there is room. The Roth pathway is usually smarter for younger investors because your tax bracket is likely lower now than it will be at retirement. Converting later costs more in taxes than you save. If you are in a high bracket now, a traditional 401k may make more sense. Run the numbers for your specific situation before choosing. Step 5: Asset Allocation (The Part That Matters)
Get the Full Details
Here is where the cheat sheet approach actually helps. You do not need to pick stocks. You need to decide on a split between stocks and bonds, then execute with broad index funds. A common starting point for someone in their 30s is 80 percent stocks and 20 percent bonds. For someone in their 50s, 60/40 is more typical. The exact percentages matter far less than having a plan and sticking to it through market cycles. I held 90/10 during the early 2000s because my employer plan was heavy on the S&P 500 index fund and I did not bother shifting until I lost sleep over the drawdowns. That was a mistake. A 50/50 split would have kept me invested instead of selling low out of anxiety. Step 6: Broad Market Index Funds Buy one total US stock market index fund, one total international stock index fund, and one total bond index fund. The VTI, VXUS, and BND combo covers roughly 95 percent of investable global markets with three funds and an expense ratio below 0.10 percent combined. You do not need seven sector funds or twelve international holdings. Simplicity reduces both your tax bill and the chance you will fumble the portfolio during a panic. I once managed a portfolio with twenty-two holdings because someone convinced me more was better. It took four hours a month to rebalance and produced worse returns than a three-fund portfolio after costs and taxes.
Step 7: Automatic Contributions and Rebalancing Set up automatic monthly contributions. Then rebalance twice a year or whenever any allocation drifts more than five percentage points from your target. Automated rebalancing through your brokerage eliminates the emotional component. Do it on a calendar reminder or let the platform handle it. The key is consistency, not precision.
Edge Cases That Break the Standard Advice
The standard guide assumes a straightforward W2 employee with a basic 401k. It does not account for a self-employed person with a solo 401k who also runs an LLC, or a dual-income household where one spouse has a pension and the other does not. I had a client last year who made $140,000 as a freelance graphic designer with no employer plan. The standard Roth IRA contribution limit applied, but he was hitting the income phase-out for direct Roth contributions. I routed him into a backdoor Roth strategy instead, which required careful tracking of his basis in pre-tax accounts to avoid the pro-rata rule eating his tax advantage. Most DIY guides do not mention this trap, and IRS Form 8606 is not intuitive. If you are in a similar situation, consult a CPA before attempting a backdoor Roth on your own. Another overlooked scenario: people who inherit a traditional IRA from a parent. Required minimum distributions force taxable income whether you need the money or not, and the stretch beneficiary rules changed significantly after the SECURE Act passed in 2019. The default ten-year distribution window can push you into a much higher tax bracket. I worked with someone who inherited $280,000 and took the entire amount in year three, landing them in the 37 percent bracket for that year. They would have been better off spreading distributions across the full ten years, even though the math felt painful watching the balance sit untouched.

What This Approach Does Not Do
A step-by-step cheat sheet will not help you time the market. It will not generate alpha. It will not protect you from a 40 percent drawdown if you are emotionally unprepared. The entire system depends on your ability to keep contributing during bear markets, and that is the hardest part. I have watched competent people break their own rules during sharp corrections. The portfolio design is only as good as the discipline behind it. If you find yourself checking your balance daily or selling when the S&P drops 10 percent, you need a simpler allocation and possibly a financial advisor who can enforce the plan when you cannot enforce it yourself. The alternative to this structured approach is picking individual stocks based on headlines and social media, which produces outcomes consistent with gambling, not investing. You will occasionally win. The expected value works against you over any meaningful time horizon. The three-fund portfolio is boring because it is designed to avoid behavioral disaster, not because it is optimal for excitement. If you want excitement, put money in a casino. If you want retirement security, follow the steps, rebalance annually, and ignore the noise. One more thing most guides skip: insurance. Term life, disability, and umbrella liability should be in place before you start deploying large sums into taxable accounts. A single bad fall or a lawsuit can wipe out five years of compound growth faster than any market crash. I lost a client's portfolio to a medical liability claim that would have been covered by a twenty-dollar-thousand umbrella policy. The check was written before he ever opened a brokerage account. Do not make the same mistake.