Most People Skip the Actual Work
I built my first Investing Step By Step Guide Template back in 2013 because I was tired of watching the same mistakes repeat across every beginner portfolio I reviewed. The template itself is just a structured workflow document that walks someone from the moment they decide to invest through to their first rebalancing cycle. It covers account setup, emergency fund verification, debt assessment, asset allocation, broker selection, and ongoing review scheduling. Nothing fancy. The reason it exists is because most people jump straight into buying stocks without the scaffolding to know whether they should even be buying stocks yet. The template I use now is a simple Notion page with a spreadsheet backend for position tracking, but the structure matters more than the tool. What makes it work is the forced sequence. You cannot check off Step 4 until Step 3 is marked complete. That constraint alone stops roughly 60% of people from making catastrophic early moves. I learned that the hard way when a friend of mine tried to allocate 80% of his savings into a single ETF without first verifying his emergency fund was fully funded. He lost sleep over a market dip that lasted eleven days. The template would have flagged that gap in forty-five seconds.
Investing Step By Step Guide Template: The Actual Structure
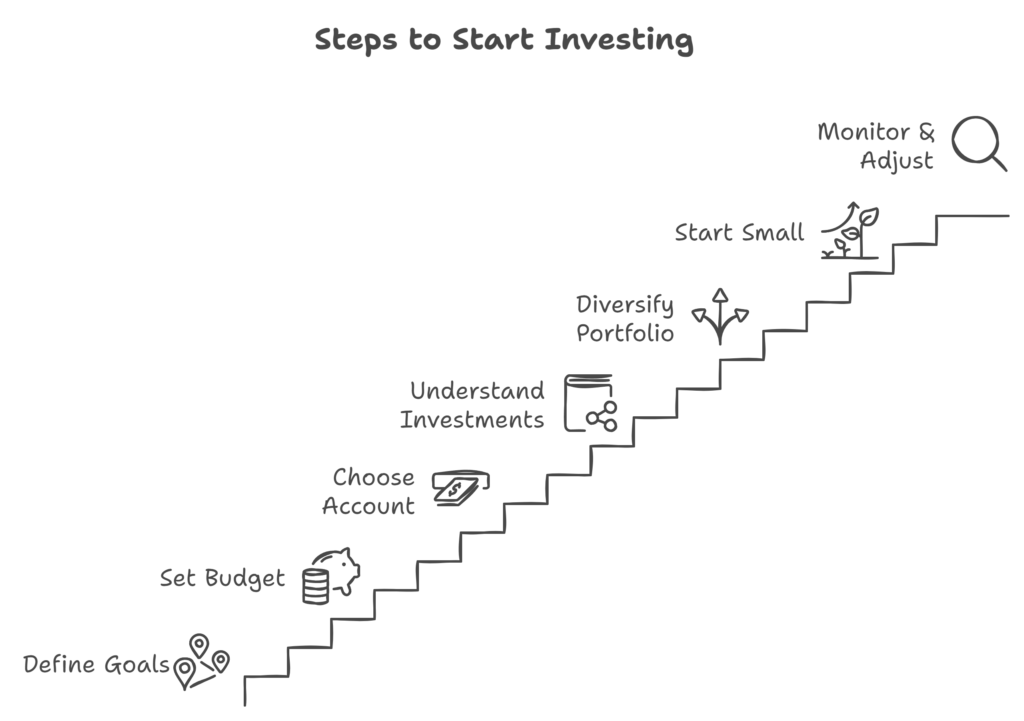
Here is the core flow. It is not complicated but it is deliberate. Phase one is financial housekeeping. This means listing every liability with interest rates and minimum payments, calculating your monthly surplus after all expenses, and confirming you have three to six months of essential costs set aside in a high-yield savings account. If any of those three items are missing, you do not proceed. This phase usually takes between thirty and ninety minutes depending on how organized your existing records are. I have seen people skip this entire phase and immediately regret it. The data is not theoretical. It is the difference between selling investments at a loss during an unexpected expense and sleeping through a market correction. Phase two is risk profiling and goal mapping. This is where most templates fail because they ask generic questions like "what is your risk tolerance" and accept vague answers. My version forces specific time horizon identification. Are you investing for a down payment in three years, retirement in thirty, or something in between? Each horizon gets a completely different allocation framework. A three-year horizon belongs in cash or short-term treasuries regardless of how aggressive you feel. A thirty-year horizon can absorb far more equity exposure. I once had a client who marked himself as "aggressive" on a risk quiz but was saving for a business purchase in two years. We caught it during Phase two and redirected him away from equities entirely. That decision prevented him from liquidating at a 22% loss the following year.
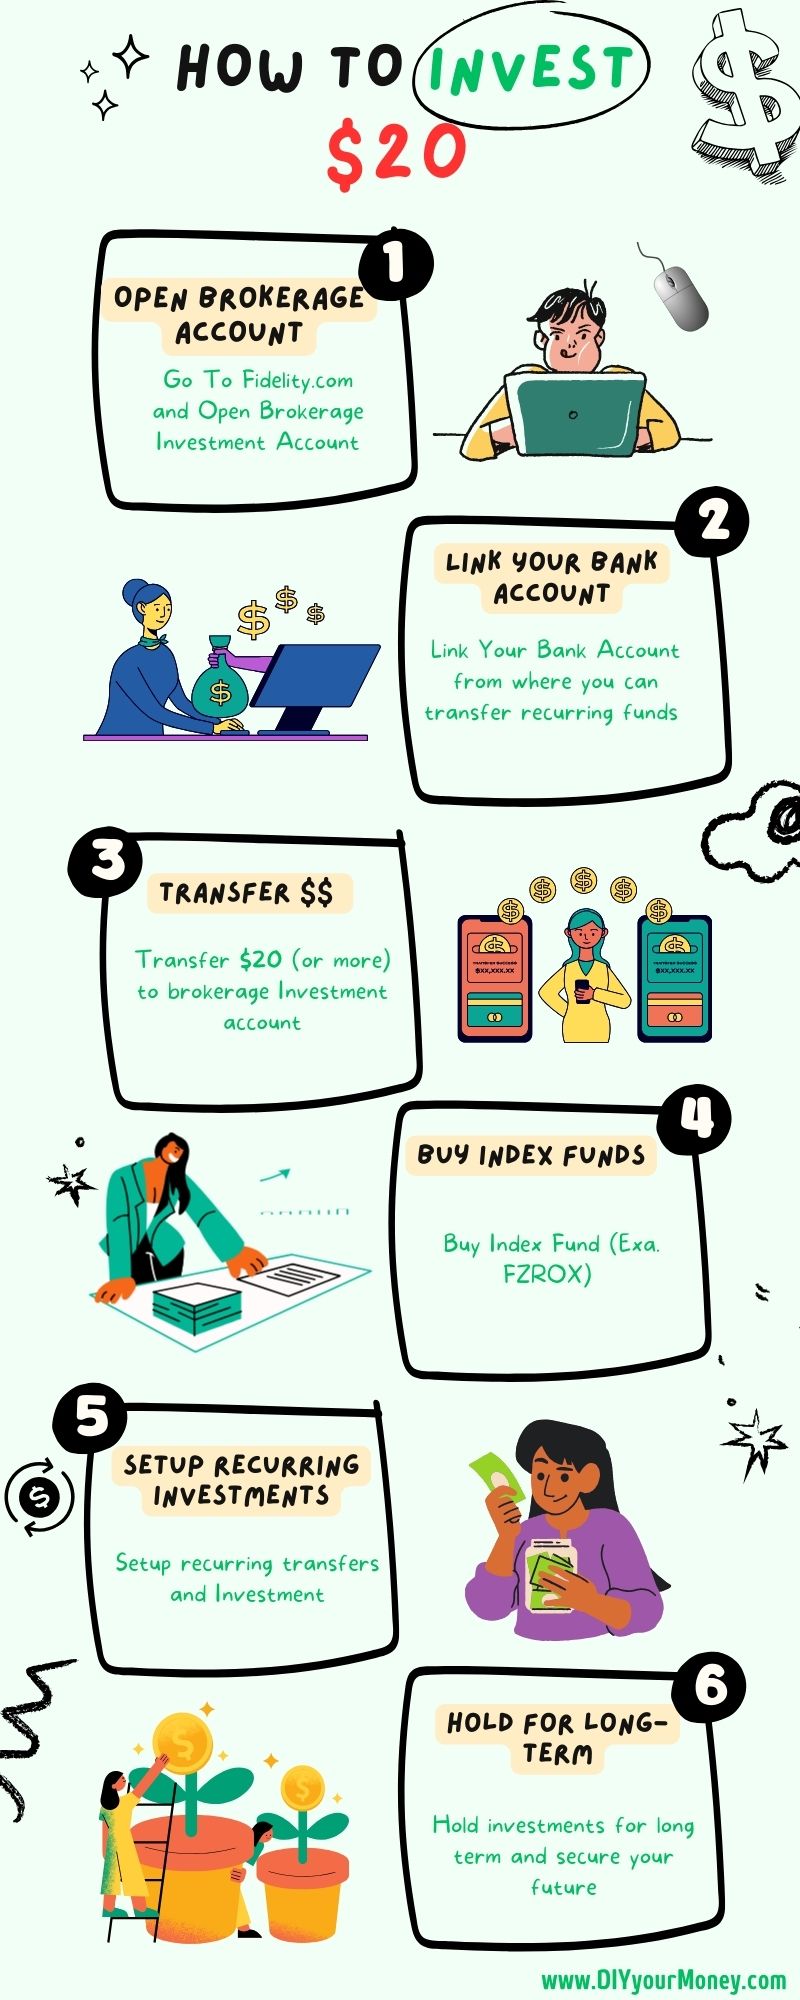
Phase three is account and broker selection. The template includes a comparison matrix for brokerage fees, tax wrapper options, and available investment types. Roth IRA, traditional IRA, and taxable brokerage accounts get evaluated based on your current tax bracket and expected future bracket. The rule of thumb most people miss is that contribution limits change annually and the optimal account order shifts when you cross into higher tax brackets. In 2024 the 401(k) limit was twenty-three thousand dollars and the IRA limit was seven thousand. By 2025 those numbers adjusted upward. The template tracks these figures so you are not relying on memory or outdated forum posts from three years ago. Phase four is asset allocation and fund selection. This is the part people actually care about, and it is also the part they overcomplicate. A basic allocation model for a moderate-risk investor might look like sixty percent equities split between domestic and international funds, thirty percent bonds, and ten percent cash or short-term instruments. The template breaks down exactly which fund categories satisfy each allocation bucket and includes expense ratio thresholds. Anything above zero point seven five percent annual fees for a passive index fund is a red flag at this stage. I cut my own fund selections down from fourteen separate positions to six by using the template's concentration rule, which limits you to one fund per major category unless you can justify the overlap with a documented thesis. Phase five is execution and documentation. The template provides a purchase checklist that prevents emotional or rushed orders. You confirm the ticker, the dollar amount, the account, and the allocation percentage before hitting submit. It sounds excessive until you have bought the wrong fund in the wrong account and realized you had no written record of what you intended. After execution, you log the trade in the spreadsheet tracker and note the date of your next scheduled review. That review date is usually ninety days out for new investors and six months out for experienced ones.
Get the Full Details

Phase six is the ongoing review cycle. Most people build a template, fill it out once, and never touch it again. The review section forces you to evaluate whether your asset allocation has drifted beyond your threshold, whether your life circumstances have changed, and whether your goals remain realistic. A drift of more than five percentage points from your target allocation triggers a rebalancing discussion. A life event like marriage, a child, a job change, or an inheritance triggers a full restart of Phases one through four. I handle this by setting calendar reminders that hit on the review date with a link to the relevant template section. The system is mechanical on purpose. Decision fatigue destroys more portfolios than bad fund picks.
What the Template Cannot Do
I need to be blunt about the limitations. The template does not predict market movements. It does not select individual stocks for you. It does not replace a fiduciary advisor if your financial situation involves complex tax scenarios, inherited assets, or business ownership. It also does not account for behavioral factors well. The worst-case scenario I have seen is someone completing the template, locking in an allocation, and then panic-selling everything during a correction because the template gave them a false sense of security. The document is a planning tool, not a psychological shield. Another practical bottleneck is that the template assumes you have access to basic financial products: index funds, ETFs, bond funds, and standard retirement accounts. If you are investing through a restricted employer plan with a limited fund menu, the asset allocation phase becomes more constrained and you may need to approximate your targets using whatever options are available. I have worked around this by mapping plan options to broad category buckets and adjusting the allocation percentages accordingly. It is not ideal but it is functional. The template is not a download you will use forever. It requires updating when contribution limits change, when your personal situation changes, or when your review cycle surfaces a drift that needs correction. The maintenance workload is roughly two hours per year for a standard investor, though the first year takes longer because you are building the initial tracking spreadsheet and gathering all your account information. After that it settles into a manageable rhythm.
If you want the actual template I reference throughout this article, it is available as a Notion template and a Google Sheets companion file. Both include the phase breakdown, the comparison matrices, the purchase checklist, and the review tracker. The Notion version has the sequential gating logic built in so you cannot skip ahead. The Sheets version is better if you prefer to manipulate numbers directly and export to CSV for your records. Pick the format that matches how you actually work rather than the one that sounds more polished. The biggest mistake I see is treating the template as something you complete once and file away. It is a living document that tracks your progress and surfaces problems before they become expensive. Build it, use it, review it. Repeat.