How I Actually Screen Stocks Without Losing My Mind
I spent years building stock screening systems before I realized most of them were garbage. Not because the math was wrong, but because the assumptions baked into the filters were almost always backwards. When I finally stopped trying to find the perfect screener and started treating stock selection as a process of narrowing down candidates through rejection rather than finding gold, everything changed. This Investing Stock Selection Guide won't teach you to pick winners. It'll teach you how to not pick losers, which is actually the harder skill. Let me start with the framework I use, then talk about where people go wrong. The workflow itself isn't revolutionary, but the order matters more than most people think. You need qualitative filters first, then quantitative ones, then price action confirmation. Most retail investors do it backwards. They screen on P/E ratios and earnings growth first, then maybe glance at the business model if they feel like it. That's why they end up owning companies with great ratios that are also fundamentally broken.
The Practical Investing Stock Selection Guide Workflow
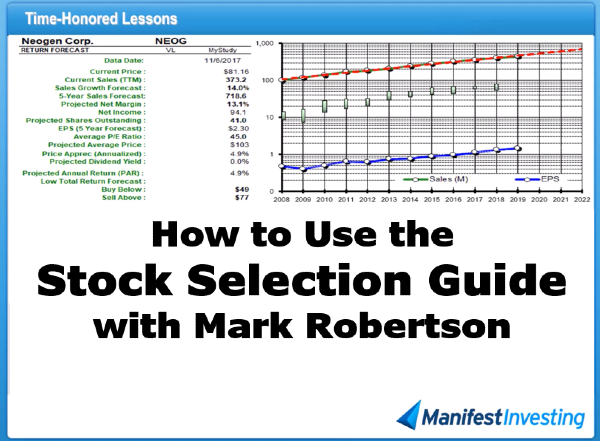
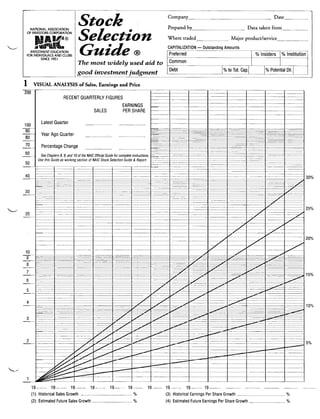
The process takes about 45 minutes per stock if you're efficient. The first pass with all seven filters typically weeds out 90% of what you throw at it. That leaves you with maybe three or four candidates worth a deeper dive. Here's how it actually works. I start by narrowing to sectors I understand and market caps between two billion and one hundred billion dollars. Below two billion and liquidity becomes a nightmare. Wide spreads, thin order books, manipulation risks. Above one hundred billion and you're mostly chasing yield, not growth. The sweet spot for what I'm looking for sits right in between. I skip financials and utilities because their balance sheets work differently. Their leverage ratios mean something else entirely. I also avoid energy unless I'm genuinely interested in the commodity cycle because those dynamics operate on a completely different timeline. Now I'm checking five years of data. Revenue needs to have grown at least eight percent annually on a compound basis. Not just the last year. The compounding matters. Earnings per share should follow the same trajectory with a minimum ten percent CAGR. The key thing here is consistency, not peaks. I'm looking for a company that can sustain growth, not one that had a lucky quarter where they sold an asset or got a one-time tax benefit. If revenue is growing but earnings aren't, that's margin compression. I don't want to deal with that until I understand why.
Debt to equity ratio below point five for non-financial companies. Current ratio above point five. Free cash flow positive for at least four of the last five years. I'm not looking for a debt-free company. That's rare and often means they're not using leverage intelligently. But a debt-to-equity ratio above point five in a slow-growth business is a red flag. Free cash flow is where most companies lie. Earnings can be manipulated with accounting choices. Depreciation schedules, stock-based compensation, inventory write-downs. Free cash flow is harder to fake. It's what actually pays dividends and funds buybacks. The formula is straightforward: operating cash flow minus capital expenditures. If a company reports $200 million in net income but negative free cash flow for three consecutive years, walk away. Something is wrong. I check whether insiders have been buying or selling over the past twelve months. Net insider buying is a strong signal. Net selling isn't automatically bad, especially if it's diversification after an IPO lockup expires. But I pay attention to the pattern. Selling every quarter at the same price level? That's not diversification. That's a lack of conviction. Institutional ownership between forty percent and eighty percent is my target zone. Below forty and there might be a reason nobody wants it. Above eighty and you've got less upside from multiple expansion because everyone who wanted in already did. Price to earnings below the sector median, or if the company is growing faster than the sector average, a slightly higher P/E can be justified. Price to free cash flow below twenty is another useful benchmark. I'm not looking for the cheapest stock. I'm looking for reasonable price relative to the quality of the business. A great company at a fair price beats a fair company at a great price over time. This sounds obvious until you've seen someone buy a stock because it's trading at eight times earnings and then watch it go to zero because the business model was collapsing.
Get the Full Details
This is the part most people skip because it's harder to quantify. I'm looking for one of three things: a network effect where the product gets better as more people use it, a cost advantage that's structurally embedded rather than temporary, or high switching costs that make it painful for customers to leave. I read the annual report's risk factors section. Companies are required to disclose what could go wrong. That section often reveals the competitive position better than any bull case presentation. If the risk factors mention "intense competition" three times and never mention a unique advantage, that's your answer. The stock should be above its two hundred-day moving average. Ideally pulling back from recent highs rather than breaking out to new ones. I'm not trying to catch the absolute bottom. I'm looking for a reasonable entry point on an otherwise solid business. Buying at all-time highs isn't necessarily wrong. It increases your risk of a mean reversion pullback in the near term, but a strong trend can persist longer than you expect. The key is having a plan for both outcomes. I ran into a specific issue with this process that taught me something important. I screened a mid-cap healthcare company that checked every single box. Revenue growth, earnings growth, strong balance sheet, insider buying, reasonable valuation. I was two days away from placing the order when I noticed the revenue growth was entirely acquisition-driven. The organic revenue was actually declining. The company was buying growth instead of building it. If I'd stopped at the top-line number and moved forward, I would've owned a company with a shrinking core business and mounting integration risk. Now I always drill into organic versus inorganic revenue before moving past the initial filter. It adds maybe five minutes to the process but prevents exactly this kind of mistake.
Here are the things that catch people up. Relying on analyst consensus estimates for forward earnings when those estimates are often stale or overly optimistic. The consensus is an average, and averages hide divergence. If five analysts say twelve dollars per share and two say six, the consensus looks fine until you dig into it. Screening for low P/E ratios without checking whether the earnings are sustainable or just temporarily elevated. This creates the classic value trap. A company with a P/E of six might be cheap because the market expects earnings to collapse next year. Ignoring the quality of earnings. Specifically the ratio of free cash flow to net income. This should ideally be above point eight. If net income is one hundred million dollars but free cash flow is only forty million, the earnings quality is questionable and I move on. Most screening tools don't show this ratio by default. You have to calculate it yourself. This system has real limitations. It misses early-stage growth companies that haven't proven profitability yet. If you're only looking at current earnings, you'll never own the next Adobe or the next Nvidia in their early years. It's backward-looking by nature. The data you're screening on has already been reported. It struggles with companies at inflection points where the data hasn't caught up to the thesis. And in heavily shorted or distressed situations, the fundamentals can look terrible even when the recovery is imminent. For those cases I use a completely different approach focused on catalyst analysis and situational awareness rather than traditional screening. This Investing Stock Selection Guide works best for established businesses with visible competitive positions. It is not a universal solution. My go-to tools are Finviz for the initial quantitative screen since it lets you layer multiple conditions together quickly. The SEC's EDGAR database for pulling actual filings directly. And Yahoo Finance for basic historical data when I need to verify something fast. I also use Koyfin for deeper fundamental analysis when a stock passes the initial filters. It's not free but the free tier covers most of what I need. The Screening Stock Tools interface has improved significantly over the past few years. Most platforms now let you save custom screens and set up alerts when stocks meet or lose criteria. That alone saves about fifteen minutes per screening session compared to manual checking.
The whole process takes about thirty-five minutes for the full workflow. You can trim it to twenty minutes once you've developed familiarity with the sectors you track. The real time investment isn't in the screening itself. It's in the ongoing monitoring after you own the position. Most people spend too much time screening and not enough time tracking whether their thesis is still intact. A stock that looked good three months ago can look very different after an earnings report, a guidance change, or a competitive shift. Set reminders to review your holdings quarterly at minimum. Revisit the seven-step process on each one. If it no longer passes, the question isn't whether to hold. The question is whether to hold while looking for an exit or to exit immediately.