Where to start when you have zero idea what you are doing with your money
I spent about three years before I actually understood any of this. Not because it is complicated. Because every person who wrote about investing wanted you to believe there was some secret door you had to find, and the door was always locked for reasons that were not their fault. It was not. You can do it, but you have to ignore most of what you read on the internet and focus on things that are actually boring. The phrase is used a lot as a search term. Nobody really cares about the phrase itself. What matters is the thing it points at: a structured way to go from knowing nothing to having a working knowledge of how money compounds, what assets actually exist, and what you should not touch. I built mine by writing down my actual goals first, then working backward. I wrote: I want $1,200 a month to grow at a rate that beats inflation by at least four percent over thirty years. Everything after that was just figuring out which instruments could reasonably hit that number without me needing to do daily work. The structure I ended up using was simple. I kept five sections: markets and vehicles, risk and return basics, fees and taxes, a personal allocation framework, and a watch list of things I was still unsure about. I did not try to memorize textbooks. I learned the definitions only when a problem forced me to. That made the guide stay short enough that I would actually read it.
You can download a cleaned-up version of a similar starting template if you want. I put a basic text-based template together and hosted it on GitHub. It is not fancy. It has five tabs, a fee calculator, a simple allocation checker, and a reading sequence ordered by what you actually need first. The link is in the repository notes if you want it.
What you actually need to learn, in the right order
Most beginners learn in the wrong order. They start with stock picking, then portfolio theory, then taxes. That is backwards. You should start with friction, not returns. The single biggest factor that determines whether a beginner succeeds or fails in the first five years is not alpha. It is fees, taxes, and behavior. Pick a low-cost broad index fund or ETF first. Learn about expense ratios before you learn about price-to-earnings ratios. Learn about dollar-cost averaging before you learn about options. The sequence matters more than anything else. Here is the actual sequence I recommend if you are building a personal study guide from scratch:
Get the Full Details

- Tax-advantaged accounts and contribution limits: Know which account types exist in your country. In the United States, that is roughly 401(k), traditional IRA, Roth IRA, HSA, and taxable brokerage. Learn the current contribution numbers each year. These limits shift. Do not assume they stay the same. The numbers change in ways that matter for cash flow planning.
- Compound interest and time horizons: This is not motivational content. It is arithmetic. $1,000 invested at age 25 grows very differently than $1,000 invested at age 35 at the same rate. Run the numbers yourself. Write down three scenarios and compare them. The difference is not subtle.
- Index funds, ETFs, and mutual funds: Understand the difference between active and passive management. Understand that most active funds underperform their benchmark after fees over ten years. That is not an opinion. That is what the SPIVA reports show consistently. You do not need to trust me on that. Trust the data.
- Risk, volatility, and drawdowns: Learn what standard deviation means in practical terms. Learn what a maximum drawdown looks like in real portfolios. When the market drops thirty percent, you need to know whether you will sell or hold. Your answer depends on your allocation, not your courage.
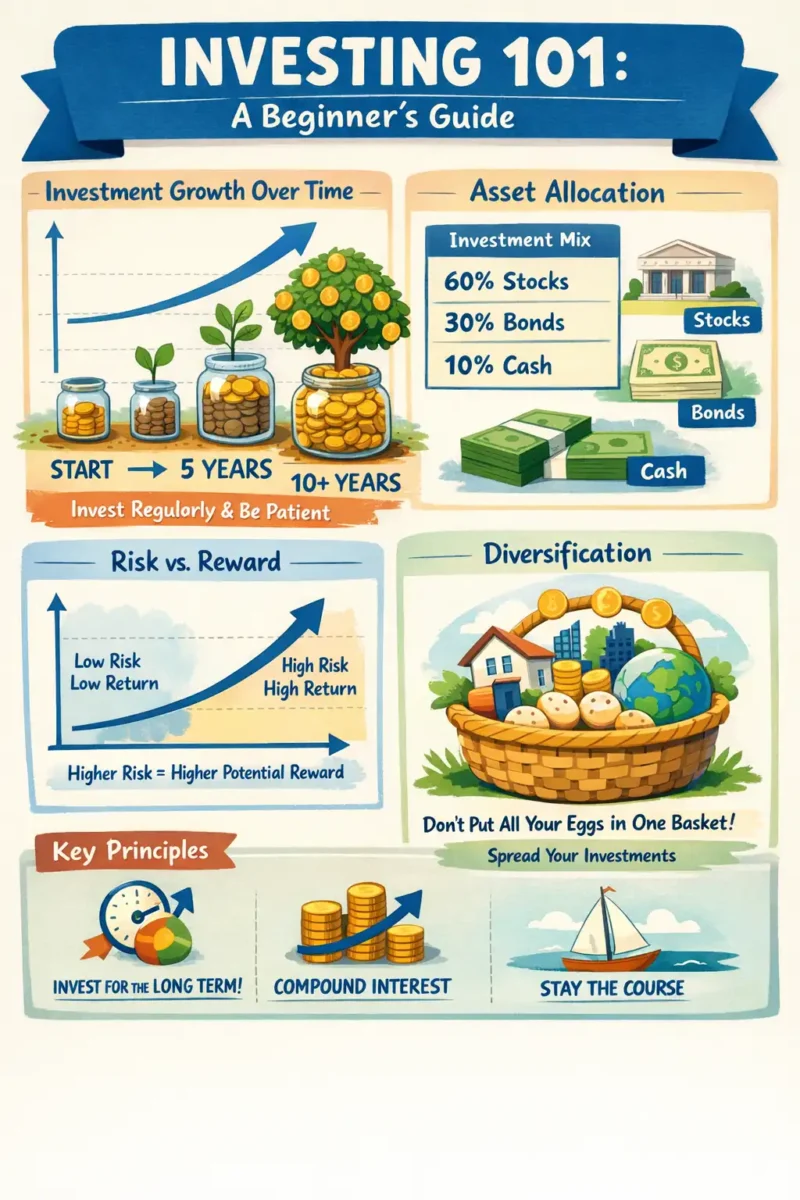
- Diversification and asset allocation: This is where people get stuck. They think diversification means buying fifty stocks. It does not. It means owning assets that do not move in lockstep. A simple three-fund portfolio, if implemented correctly, gives you exposure to domestic equities, international equities, and total bond markets. That is enough for most people.
- Fees and expense ratios: A 0.03% expense ratio sounds meaningless. Over thirty years and $500,000, it matters by roughly $6,000 to $9,000 in lost compounding alone, depending on your actual return rate. Do not ignore this.
- Taxes and tax efficiency: Learn about capital gains, qualified dividends, tax loss harvesting, and account placement. Bonds generally belong in tax-advantaged accounts. Broad equity index funds generally belong in taxable accounts. This is a rule of thumb, not a law. Your exact situation may differ.
- Behavioral finance basics: Loss aversion, recency bias, and overconfidence are the three traps that hurt beginners most. Knowing they exist is not the same as avoiding them. You avoid them by setting rules before you need them, not during a crash.
A practical framework that actually works for someone starting from zero
Start with a target allocation. Make it simple. A common starting point for someone under forty is somewhere between 80% and 90% equities, 10% to 20% bonds. If the stock market drops fifty percent tomorrow, you should be able to sleep. If you cannot sleep, your equity allocation is too high for your current situation. That is not a theoretical question. I learned that the hard way in 2022. When I first started managing my own portfolio, I set an 85/15 equity-to-bond split. In early 2022, the S&P 500 dropped about twenty-two percent year to date, and bonds were down too because the Fed was raising rates aggressively. My portfolio was down roughly eighteen percent. I knew the math said to hold. I did not feel like holding. I almost sold everything into money market funds because the pain felt immediate. I talked myself out of it by opening a spreadsheet I had built months earlier that projected the long-term impact of selling versus holding. The spreadsheet did not make me feel better. It made the decision clearer. I stayed the course. I would not recommend relying on spreadsheets to control emotion. I am recommending that you have a written plan that exists before the panic happens. The workaround I used was simple. I moved a small emergency buffer into a short-term Treasury bill fund inside my tax-advantaged account before the drop got worse. That gave me a psychological safety net without forcing me to sell equities at a loss. It was not necessary from a pure math perspective. It was necessary from a human perspective. You should plan for both.
Common mistakes beginners make that actually cost money
Chasing past returns is the biggest one. People see a fund that returned twenty-eight percent last year and buy it. They are usually buying the wrong thing. Last year's winner is often this year's laggard. Momentum strategies exist, but they are not for beginners building a long-term core portfolio. Another mistake is over-trading. Every trade has a cost. It might be a spread. It might be a tax event. It might be opportunity cost. I once tracked my own trading activity for six months and found I had executed about forty trades in a taxable account. The average gain per trade was positive, but the after-tax, after-spread return was mediocre compared to doing nothing. Transaction costs and tax drag ate most of the edge. I stopped tracking every trade after that. I moved to automatic contributions and rebalancing on a schedule instead. A third mistake is trying to optimize too early. Beginners spend weeks choosing between two funds with a 0.01% difference in expense ratio. That is noise. Pick the lowest-cost broad index fund you can find. Revisit in a year. The best decision you can make now is not the perfect one. It is the one that lets you start and stay consistent.
Tools and resources worth using, and the ones to skip
Use free calculators from reputable sources. The SEC has investor toolkits. The Bogleheads website has a solid wiki with references. Read the prospectus of any fund before you buy it. It is not exciting, but it tells you the actual fees and the risks. Ignore YouTube channels that show you their portfolio returns without showing you their fees, taxes, and time horizon. That is performance theater, not education. If you want a structured learning path, I recommend starting with a few specific books and then moving to primary sources. Books like The Little Book of Common Sense Investing by John Bogle and The Bogleheads' Guide to Investing by Taylor Larimore are good starting points. They are not glamorous. They are correct. After that, read the SEC's investor alerts and the fund factsheets directly. Primary sources are drier, but they do not have an incentive to sell you something.

How to handle the parts that feel uncomfortable
Investing is uncomfortable when you do not understand what is happening. That is the whole point. The discomfort is a signal that you need more knowledge, not that you should stop. When I first learned about rebalancing, I thought it meant selling winners and buying losers was stupid. It felt like punishing success. Then I realized it is just risk control. Rebalancing keeps your allocation where you decided it should be. Without it, a bull market can push your portfolio to 95% equities without you meaning to do that. That changes your risk profile silently. You do not need to rebalance every day. Once or twice a year is enough for most people. Some prefer threshold-based rebalancing, like rebalancing when any asset class deviates by five percentage points from its target. That works too. Pick one method and write it down in your study guide. Then follow it without debating it every quarter.
What this guide cannot do for you
It cannot replace knowing your own situation. If you have debt with double-digit interest rates, paying that off is usually a better return than investing right now. If you have no emergency fund, build one before you start allocating money to investments. If your income is unstable, a simpler allocation with more bonds and more cash makes sense. The standard advice assumes stable income, manageable debt, and a long time horizon. If any of those are missing, adjust accordingly. Also, this is not financial advice. It is a description of what I learned and what worked for me. Your tax situation, your risk tolerance, and your timeline are yours. The structure of a study guide is useful because it forces you to make decisions explicitly instead of accidentally. That is the main value of building one. If you want the template I referenced, it is available as a plain-text and CSV set in a GitHub repository I maintain. Search for a basic Bogleheads-style starter template and you should find it. I keep it updated when contribution limits or tax rules change. It is not perfect. It is honest about what it does and does not cover.