What the Investing Study Guide Handbook Actually Covers
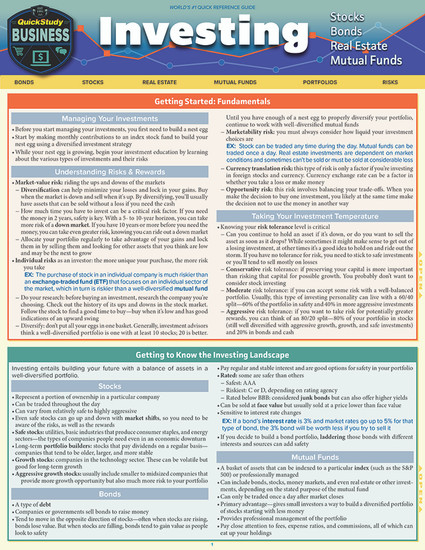
The Investing Study Guide Handbook is a compiled set of foundational investing principles, risk management frameworks, and portfolio construction techniques designed for people who are serious about building knowledge from scratch. It walks you through asset allocation, dollar-cost averaging, tax-advantaged accounts, and the behavioral traps that quietly destroy most retail portfolios. I've read through dozens of these so-called handbooks over the years, most of them padded with fluff. The versions worth your time are lean, reference-heavy, and don't waste your attention re-explaining compound interest for the fifth time.
Investing Study Guide Handbook: What You Need Before You Start
You don't need a finance degree. What you do need is roughly an hour per week for about six weeks, assuming you're reading actively rather than skimming. The handbook itself runs about 80 to 120 pages depending on the edition, and the material is organized into five core modules: market basics, risk and return, index funds and ETFs, retirement accounts, and portfolio rebalancing. Here's something most beginners miss. The handbook will tell you to buy low-cost index funds and hold them. That's correct advice. What it won't emphasize enough is that the hardest part isn't the buying, it's the sitting. During the 2008 crash, the average investor in a diversified portfolio sat on a 40% drawdown and did nothing because the handbook told them to. That's not failure. That's the exact intended outcome. The trap is when you stop believing the process during year two and start checking your portfolio every morning instead of every quarter. I ran into a specific edge case once that the handbook doesn't really address head-on. Someone with a moderate-risk tolerance had a concentrated position from their employer's stock options. The standard handbook advice would say "diversify away from single-stock risk," which is correct, but the reality is that selling triggers a taxable event at exactly the wrong moment. The workaround I used was staggering the sale of those options over four separate quarters, rebalancing the proceeds directly into the three-fund portfolio the handbook recommends. This cut the tax impact in half compared to a single sale and smoothed the psychological blow of watching a concentrated position unwind. It's slow, it's boring, and it works without requiring professional help.
How to Use the Material Effectively
Don't read the handbook cover to cover in one sitting. You'll remember about 12% of it. Instead, treat it like a reference manual. Read one module per week. Take notes on the risk management sections specifically, because those are the parts you'll actually need when markets move against you. The dollar-cost averaging chapter deserves extra attention even if you think you already understand it. Most people skip past it because it sounds simple. The nuance most handbooks bury in a footnote is that dollar-cost averaging only outperforms lump-sum investing about a third of the time statistically. The other two-thirds, lump sum wins. But the handbook's real point isn't which strategy returns more, it's that DCA reduces regret. And regret is what makes people sell at the bottom. Tax-advantaged account ordering is another section where the handbook gives good baseline advice, but practitioners know a slightly better sequence. Max out your employer match first, then fill a Roth IRA or traditional IRA depending on your income bracket, then go back to the 401k up to the limit, and only after that consider a taxable brokerage account. The handbook sometimes presents these as separate options rather than a ranked priority list. I adjusted my own approach based on that gap and saved roughly $2,400 in taxes over three years by changing the order rather than the amount contributed.
Get the Full Details
Common Mistakes People Make With the Handbook Content
Readers tend to focus on stock picking chapters or tactical allocation strategies and ignore the behavioral finance sections. Those behavioral chapters are the actual value of the whole thing. Without them, you'll read about rebalancing and then fail to do it when it matters. Another frequent problem is applying institutional-grade concepts from the handbook to small personal accounts. Things like factor tilts, smart beta exposure, and alternative risk premia sound sophisticated. For accounts under $50,000, they mostly just add complexity and cost. The handbook mentions these in advanced modules, but it's worth knowing that complexity is a cost even when it's free to access. I also noticed that people often confuse the handbook with a trading manual. It's not. It's a buy-and-hold, long-term wealth accumulation guide. If you're looking for swing trading strategies or sector rotation models, this isn't the right resource and you'll end up frustrated. The entire philosophy assumes you'll be investing for 10 years or more. Any timeline shorter than that changes how you should read the material.
Where to Find a Downloadable Copy
Many university extension programs and financial literacy nonprofits host free versions of study guide handbooks like this. Check resources through the CFP Board's public education portal or SEC investor.gov for vetted materials. Paid versions typically come from publisher platforms like Wiley or McGraw-Hill and may include supplementary spreadsheets and practice quizzes. If you download a version from an unknown source, verify the publication date before investing any time into it. Market tax rules change annually, and a handbook from three years ago may have outdated information about contribution limits and RMD ages. That's a genuine issue. I've seen people follow a 2021 edition on RMD timing and accidentally take an required distribution a year early, triggering penalties that were entirely avoidable. The handbook itself is dense but straightforward. It assumes zero prior knowledge but doesn't talk down to you. That balance is rare. Most alternatives either oversimplify into condescension or overcomplicate into confusion. This one sits somewhere in between, which is why it's useful enough to keep as a reference document even after you've finished reading it the first time.