What Actually Keeps You Alive in Investing
The investing world is full of people who lost money following someone else's plan. Most didn't lack intelligence. They lacked a system that acknowledged how much they don't know. An Investing Survival Guide Step By Step exists for exactly that reason — not to make you rich, but to stop you from making the same mistakes that emptied accounts every single year. Before getting into tactics, you need to understand what this guide actually covers. It is not a stock picking manual. It does not tell you which ticker to buy or when to sell. The framework focuses on the structural foundation — the parts of investing that most beginners ignore because they seem boring, but the ones that separate people who keep their money from people who lose it to fees, taxes, and emotional decisions. I built my first real portfolio in 2008, right in the middle of the crash. I had no guidance. I bought what I had heard about on forums. Some positions dropped 60 percent. Others went nowhere for three years. I learned two things that day: diversification without a plan is just gambling with extra steps, and the structure of your portfolio matters more than any individual pick.
The Actual Steps That Matter
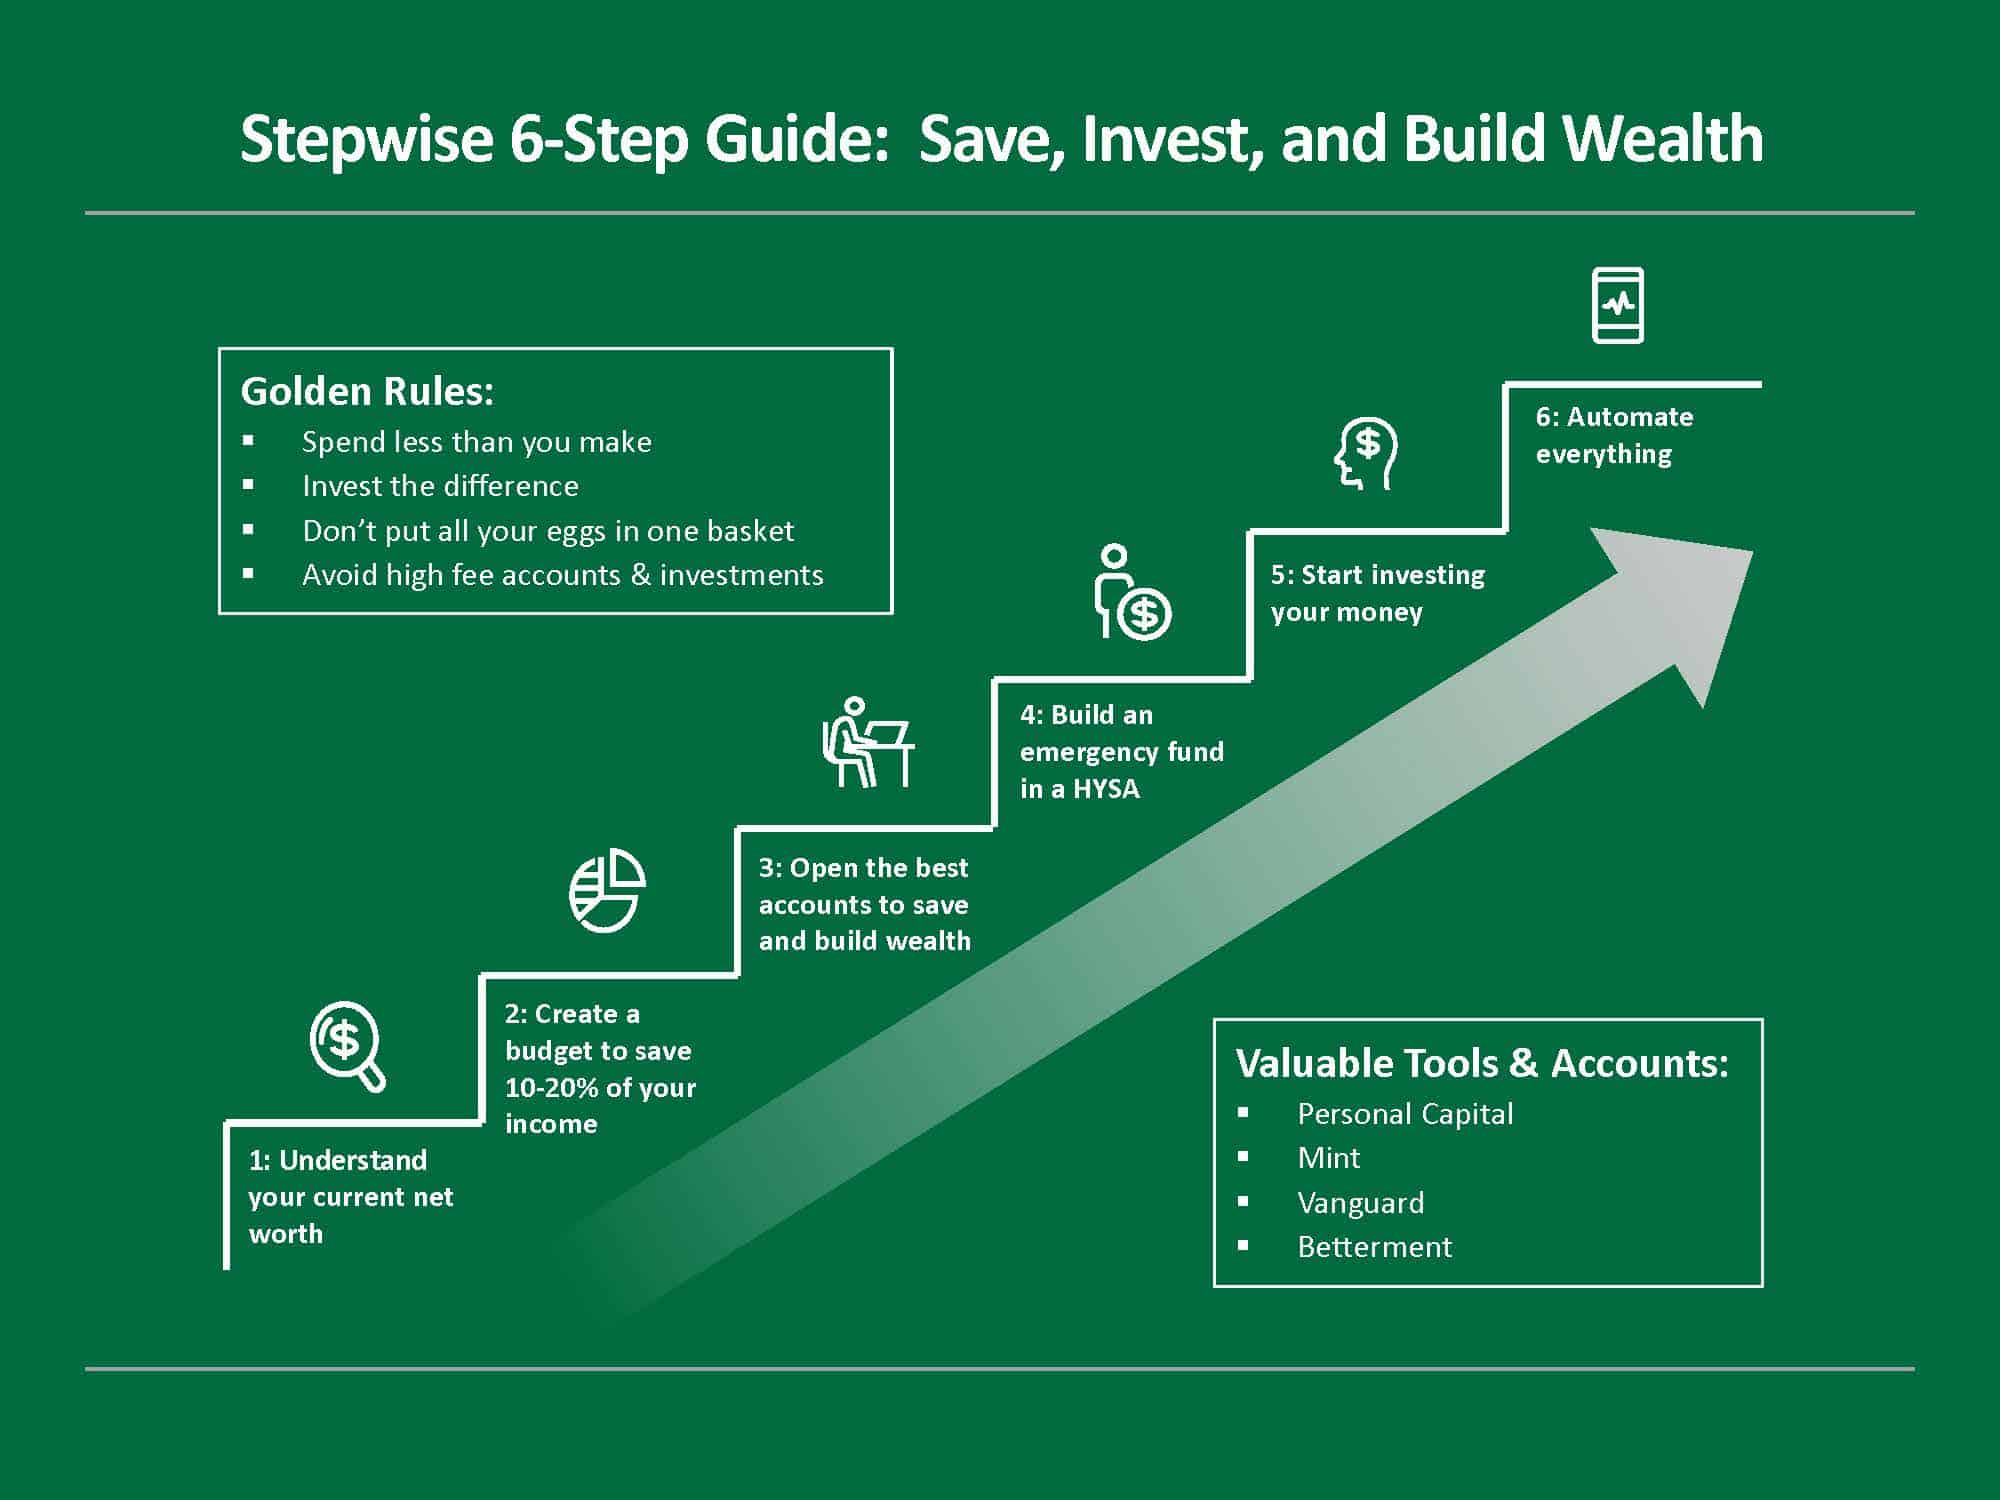
Here is the order I actually follow now. It has changed over the years, but the core sequence has stayed the same. This sounds obvious, but most people skip it. You need to know when you will actually need the money. Money needed in under three years does not belong in equities. Not even a little. It belongs in high-yield savings, Treasury bills, or short-term CDs. The after-tax return difference between a 5 percent HYSA and a volatile portfolio during a downturn can be the difference between having enough for a down payment or having to delay your plans by two years. I learned this the hard way when a client in their late forties had sixty percent of their retirement savings in a tech-heavy portfolio. They lost nearly forty percent in the 2022 bear market. They needed to retire in eighteen months. We had to restructure everything at the worst possible time. It cost them roughly eighty thousand dollars in permanent losses and a delayed retirement timeline.
Step Two: Emergency Fund First
Before you invest a single dollar beyond your emergency fund, cover six to twelve months of essential expenses in cash. This is not conservative advice. This is damage control. If you get laid off during a market downturn and you do not have cash reserves, you are forced to sell investments at a loss to pay bills. That locks in losses and removes your ability to recover when the market eventually rebounds. The typical emergency fund sits somewhere between three and twelve months depending on income stability. Freelancers and commission-based workers should lean toward the higher end. Someone with a government job might manage with three months. The exact number matters less than having the number decided and written down.
Get the Full Details

Step Three: Capture the Free Money
If your employer offers a retirement match, contribute at least enough to get the full match before doing anything else. A 50 percent instant return on your contribution is mathematically impossible to beat consistently in the open market. Skipping this is like walking past a free $100 bill because you are busy looking for a $101 bill elsewhere. After the match, max out any available HSA if you are eligible. The triple tax advantage — tax-deductible contributions, tax-free growth, and tax-free withdrawals for qualified medical expenses — is one of the most overlooked benefits in personal finance. I had a friend who ignored this for ten years because he thought he would never have significant medical expenses. He ended up using HSA funds for a major dental procedure at age fifty-two. Without the account, that expense would have been fully taxable income.
Step Four: Choose Your Core Holdings
This is where most guides go wrong. They push individual stocks or complex strategies. The reality is that for the vast majority of investors, a low-cost broad-market index fund or ETF is the correct answer. Vanguard Total Stock Market (VTI), Fidelity Zero Extended Market (FXAIX), or a simple S&P 500 fund like VOO will outperform most actively managed portfolios over any ten-year period after fees. The median actively managed large-cap fund underperforms its benchmark by about 1 to 2 percent annually after fees, according to SPIVA data. Over twenty years, that compounds into tens or hundreds of thousands of dollars in underperformance. I have seen this play out repeatedly with clients who switched from active management to passive index funds. The difference was not dramatic in any single year. It accumulated silently until someone ran the numbers.
Step Five: Set Your Asset Allocation and Rebalance
Your asset allocation is the single most important decision you will make as an investor. Studies by Brinson, Hood,, and Beebower found that asset allocation explains about 90 percent of the variability in portfolio returns. Individual stock selection and market timing account for the remaining 10 percent. A simple allocation might look like 60 percent stocks and 40 percent bonds for someone in their thirties, shifting toward 40 percent stocks and 60 percent bonds as you approach retirement. The exact percentages depend on your risk tolerance, which is different from your risk capacity. Risk tolerance is how much volatility you can handle emotionally. Risk capacity is how much volatility you can afford given your time horizon and financial situation. Most people conflate the two, and it leads to poor decisions. Rebalancing once or twice a year, or when your allocation drifts by more than five percentage points from your target, keeps your risk profile aligned with your plan. I use a simple spreadsheet that calculates drift automatically. It takes about ten minutes and prevents the emotional decision-making that happens when portfolios become overweight in whatever asset happened to perform well recently.
Step Six: Automate Everything
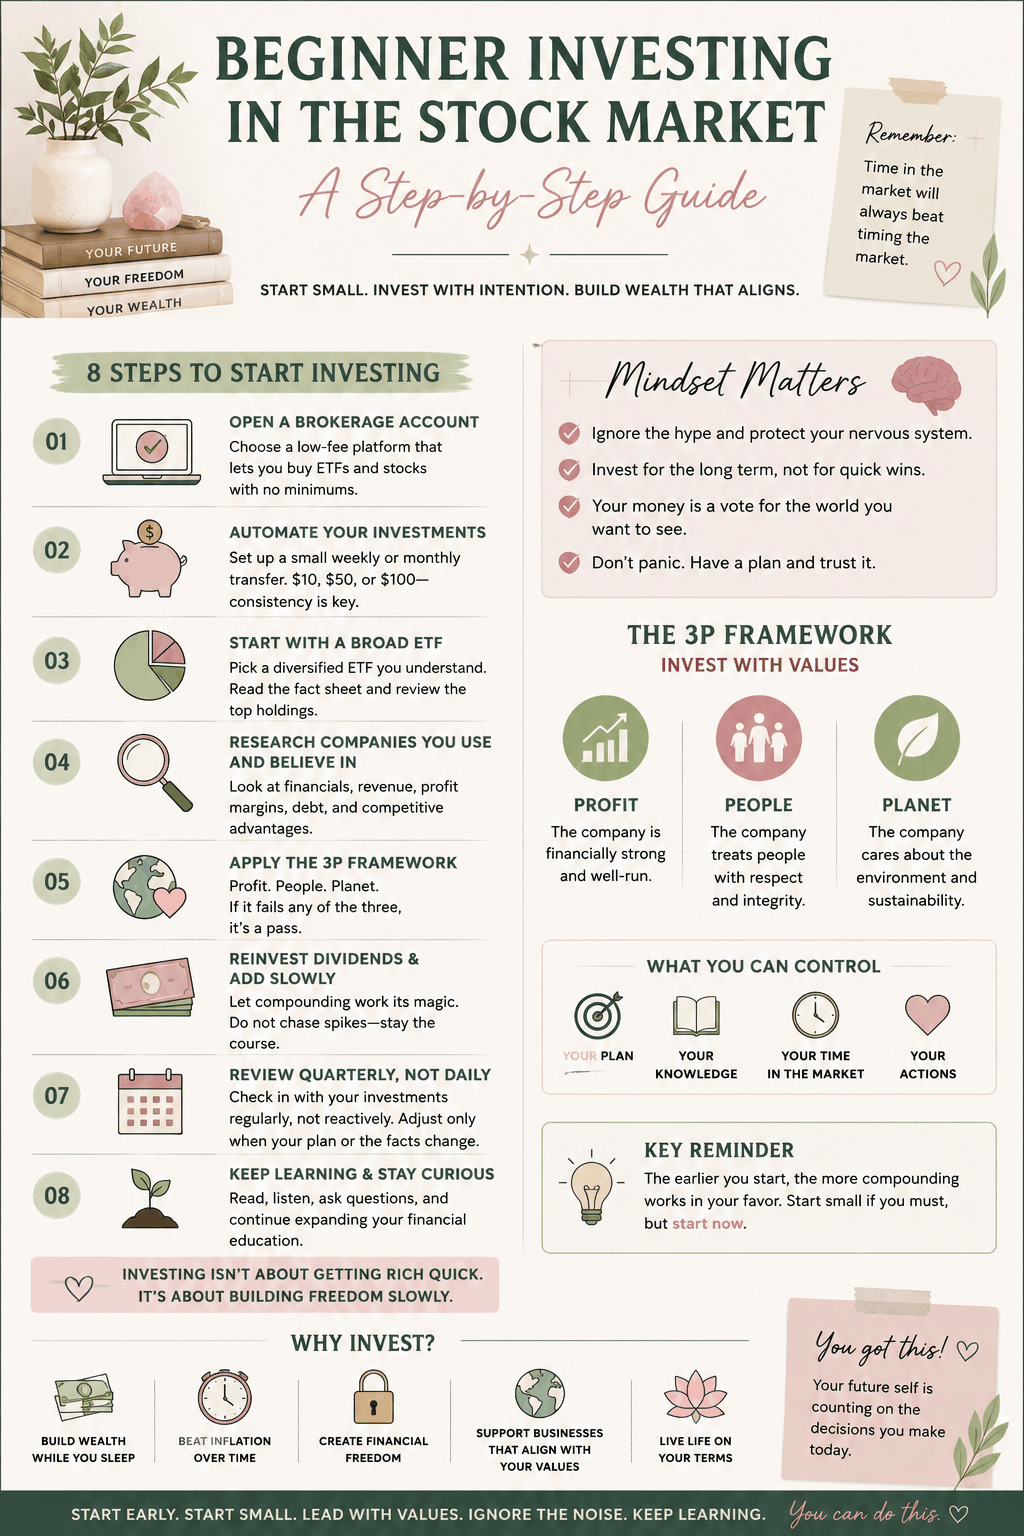
Set up automatic contributions to your investment accounts. Remove the decision from the equation. Human beings are terrible at consistently making rational financial decisions without external structure. Automatic contributions ensure you invest before you spend, not after you regret spending. I also automate rebalancing reminders and tax-loss harvesting checks. This has reduced the time I spend managing my own portfolio from about three hours per quarter to roughly twenty minutes. The automation handles the mechanical tasks while I focus on the occasional strategic review.
What This Approach Cannot Do
An Investing Survival Guide Step By Step will not make you wealthy quickly. It will not help you pick the next Nvidia or catch the next meme stock rally. It deliberately avoids those activities because they introduce variance that is statistically unfavorable for most people over the long term. The main limitation of this approach is opportunity cost during bull markets. When the market rallies 25 percent in a year, your diversified index fund might only return 18 percent. Someone who concentrated in winning stocks might return 40 percent or more. This feels like a loss in the moment. But the concentration that produces those outlier gains also produces outlier losses. The survival-first approach accepts slightly lower upside in exchange for significantly lower downside risk. Another limitation is that this framework assumes you have surplus income to invest. If you are carrying high-interest debt above 8 or 9 percent, paying that down provides a guaranteed return that competing investments rarely match. I see people constantly argue about whether to invest or pay off debt. The answer is usually both, but weighted heavily toward debt elimination if the rates are painful.
Advanced: The Tax Efficiency Layer
Once your basic structure is in place, tax efficiency becomes the next lever. Place bonds in tax-advantaged accounts where their interest income is sheltered. Keep equities in taxable accounts where you benefit from favorable capital gains treatment. This placement strategy alone can add roughly 0.25 to 0.50 percent to your annual after-tax return, which is meaningful over decades. Tax-loss harvesting is another tool worth understanding. Selling losing positions to offset gains or up to $3,000 of ordinary income per year is straightforward in principle but requires attention to the wash-sale rule, which prohibits repurchasing a substantially identical security within thirty days. I keep a log of all harvested losses and monitor the thirty-day window manually. Automated tools exist but often miss edge cases that a careful human review catches.

Common Mistakes I See Repeatedly
People chase performance. They buy what went up last year and sell what went down. This is the exact opposite of what works. Buying high and selling low is the primary mechanism by which retail investors destroy their own returns. Another mistake is overcomplicating the portfolio. I had a client who had twelve different funds across four different accounts. Managing that required constant rebalancing and created unnecessary tax complications. We simplified it to three funds: one total US stock market fund, one total international stock market fund, and one total bond market fund. The portfolio performed identically to his old setup but required twenty minutes of work per quarter instead of two hours. Finally, people let emotions drive timing decisions. Market crashes are terrifying. Good portfolios are usually constructed during them, not before them. The hardest part of this entire process is staying the course when everything around you screams that something is wrong. The structure of a simple, automated, diversified portfolio exists precisely to help you resist that urge.
Following a disciplined, step-by-step approach to investing is not exciting. It will not give you stories to tell at dinner parties. But it will likely keep more money in your account than any strategy you could pick up from a newsletter or a social media feed. That is the point.